Tag: sterling — InterMarketEdge

Tag: sterling

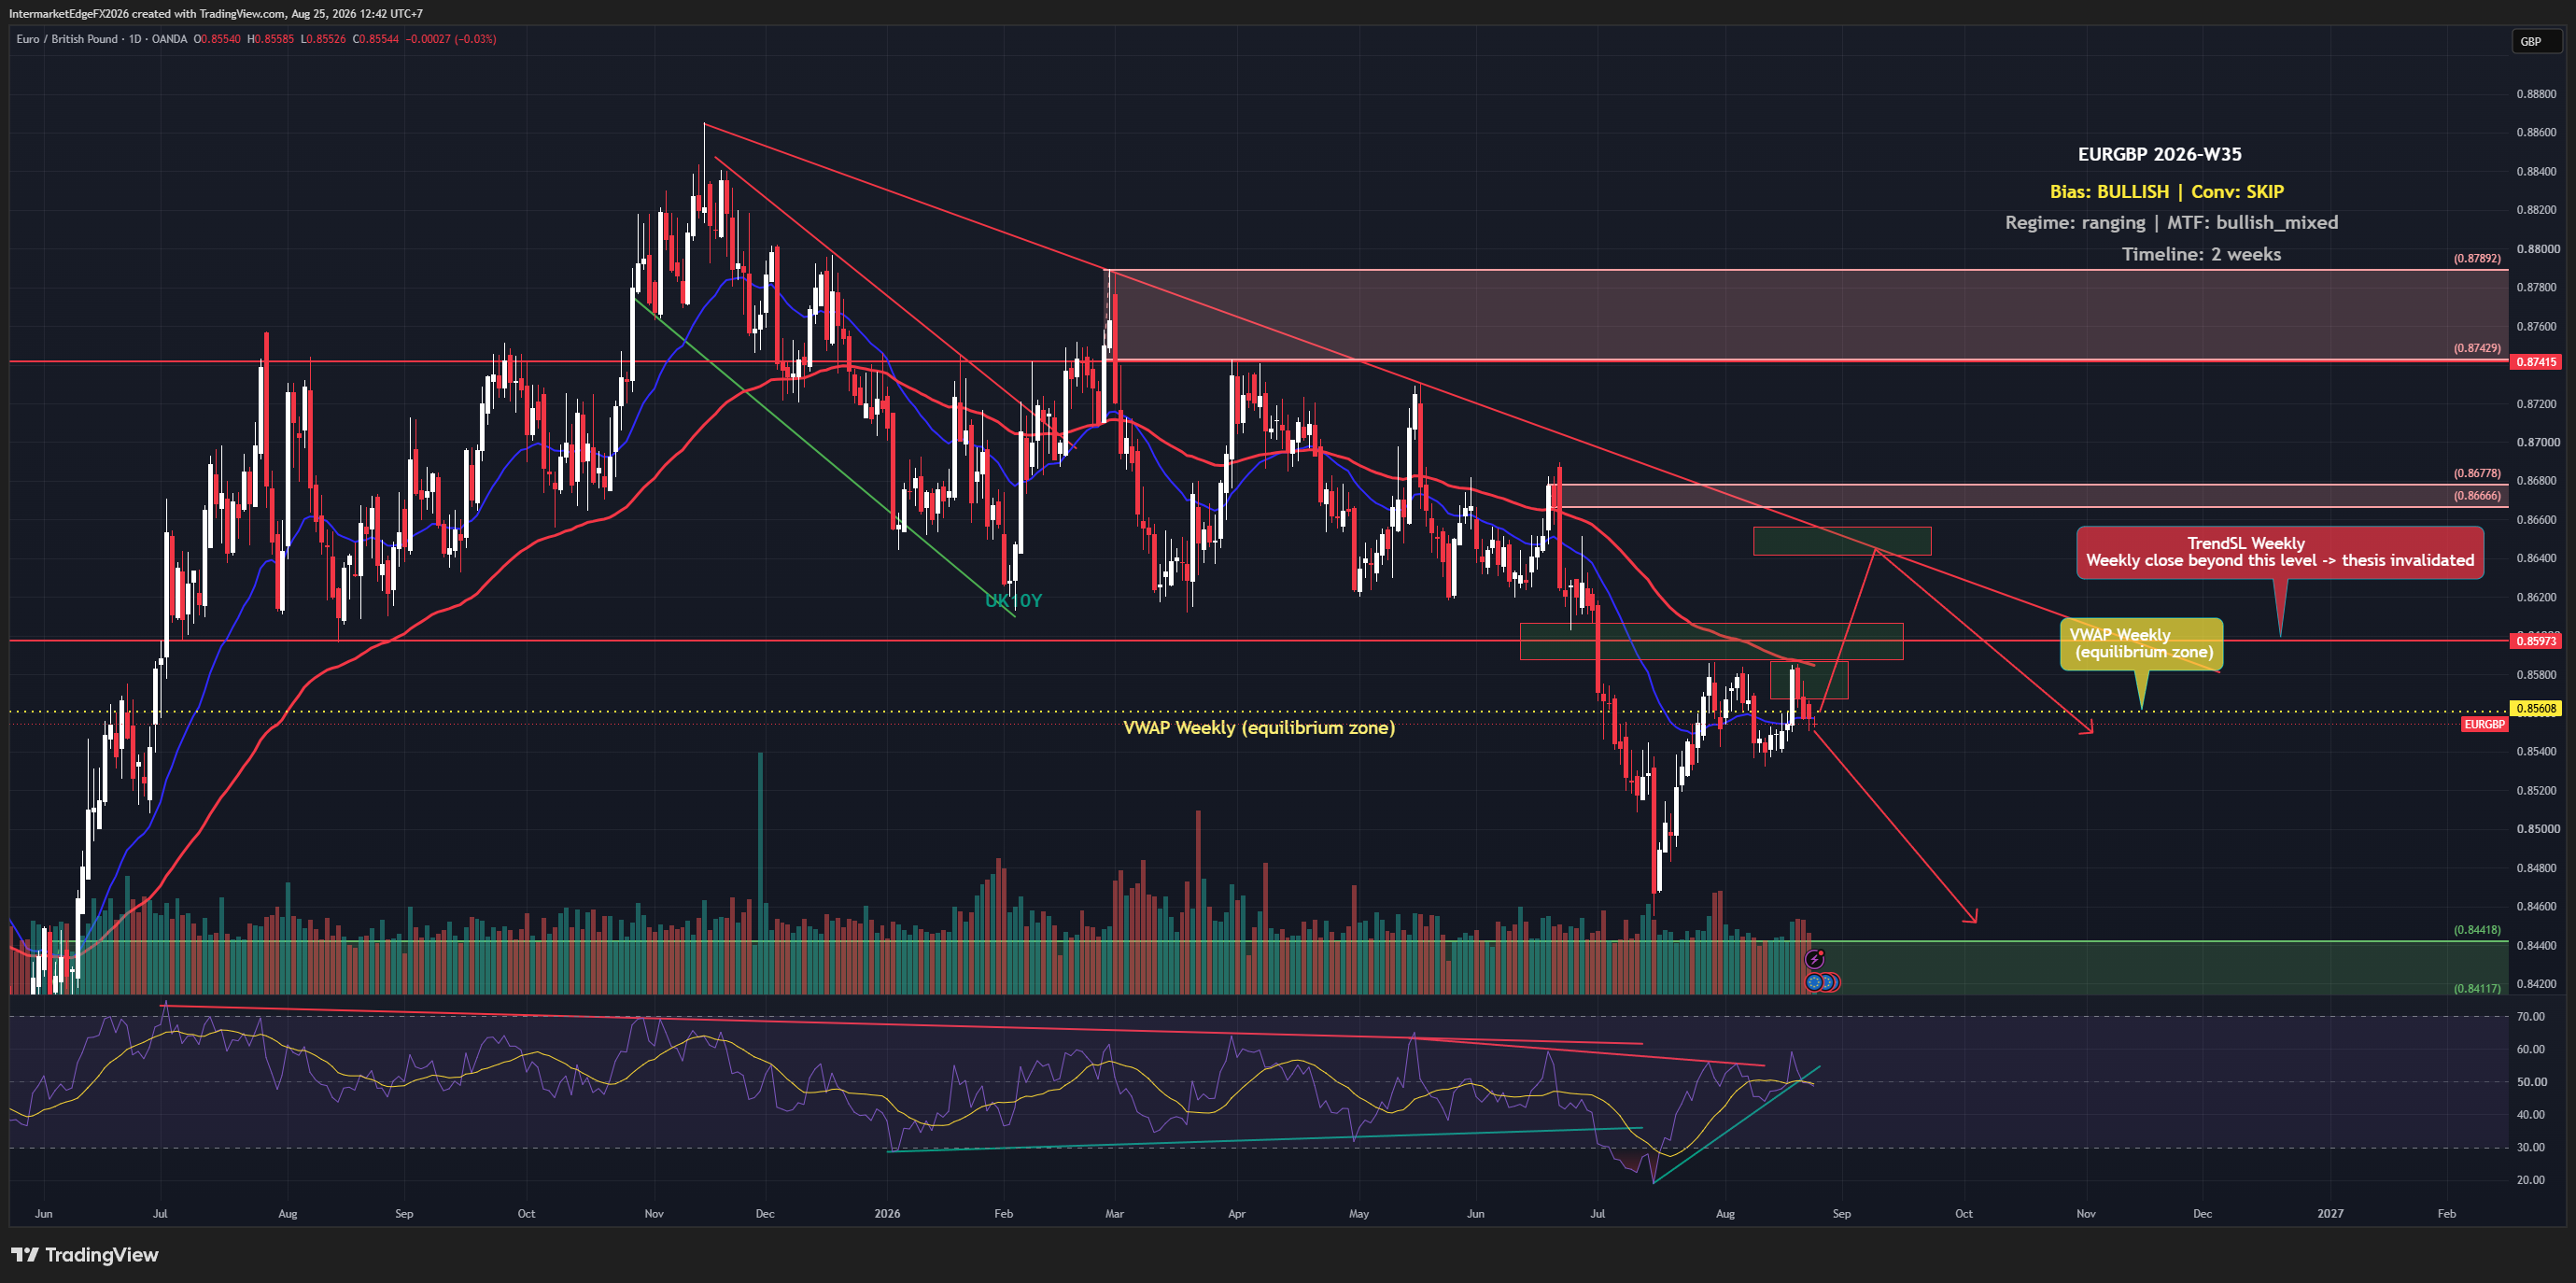
EURGBP Week W35-2026: Sterling Pauses Its Four-Week Rally, but the Bullish Case Sits Below Every Key Level

EURGBP Week W35-2026: Sterling Pauses Its Four-Week Rally, but the Bullish Case Sits Below Every Key Level

EURGBP is sitting below its weekly VWAP of 0.85608 as of Tuesday, 25 August 2026, and the technical structure already contradicts the tentative bullish lean this week carries. Sterling just paused a four-week rally as investors repositioned around US sanctions on Iran, while the ECB is signaling caution on rates even as the eurozone shows unexpected resilience. The pair is caught between two central banks pulling in different directions, and right now, neither side has won. The framework labels EURGBP bullish for the two-week horizon beginning W35-2026, but the honest description of that label is that it rests on a single thin pillar: price action alone. Every other input, positioning data, macro signals, liquidity conditions, sentiment, is neutral and contributing nothing to the directional call. That kind of setup, where one source carries the entire argument, is precisely where conviction becomes a problem, and this analysis treats it as such. The decision here is deliberately to stand aside rather than size a position, because the evidence is not yet convincing enough to justify the directional risk. The stated primary driver is the ECB versus Bank of England rate differential, the practical meaning of which is that when the ECB is expected to hold or cut while the BOE is expected to hike, Sterling strengthens relative to the euro, pushing EURGBP down, and vice versa. But here is the disconnect that matters: no rate-specific or macro-specific signals have actually fired in support of the bullish label. The driver is named but not confirmed by the inputs. Compounding that, the structural or longer-term bias is neutral, which conflicts with the short-term bullish lean. -- Intermarket Edge
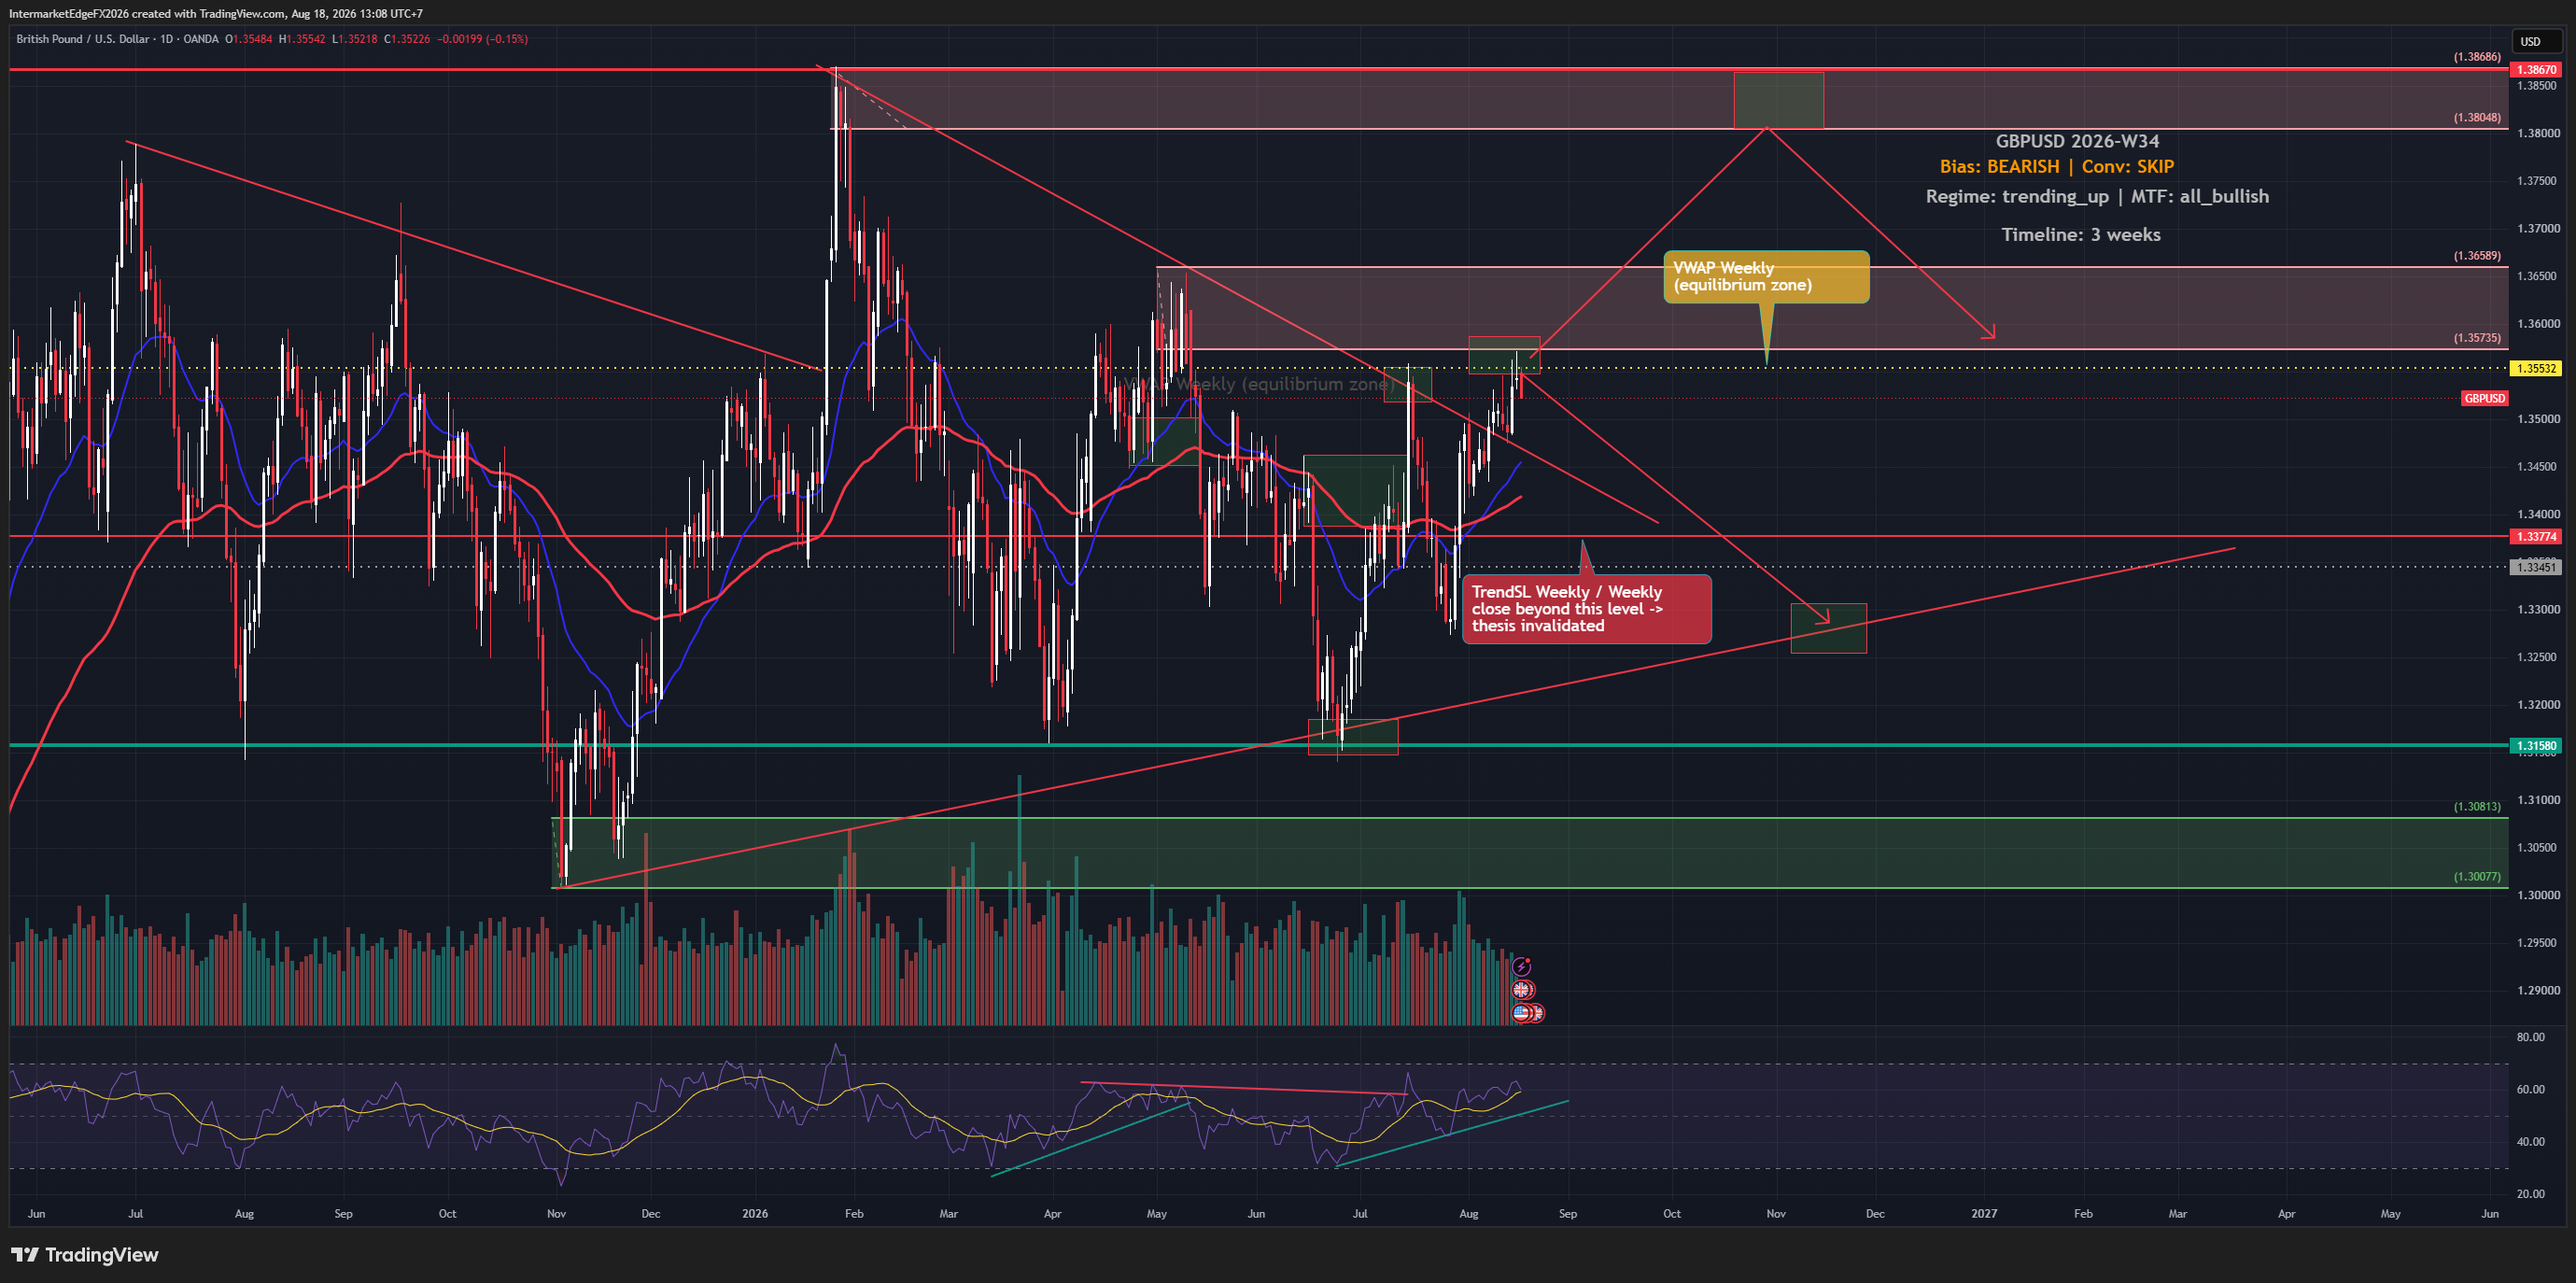
GBPUSD Week W34-2026: Pound Climbs Toward $1.36 as UK Inflation Test Looms, but Crowded Longs Warn of a Trap

GBPUSD Week W34-2026: Pound Climbs Toward $1.36 as UK Inflation Test Looms, but Crowded Longs Warn of a Trap

GBPUSD is trading at 1.35421 as of Tuesday, 18 August 2026, 06:14 UTC, trading below the weekly VWAP at 1.35532 while remaining above weekly TrendSL at 1.33774. The broader technical structure remains bullish, but price has lost the weekly VWAP in the short term. The available COT summary points to crowded long positioning, but it lacks the report week, release date, and exact net-position figure. Treat it as a directional risk flag, not standalone proof. The macro headwind from Fed real yields at 2.39% hasn't gone away. The framework carries a bearish bias on GBPUSD for the next three weeks, but the evidence supporting that bearish label is not currently strong enough to act on, and that distinction matters enormously. The primary bearish driver is the BOE-versus-Fed rate differential, where rising US real yields at 2.39% create structural pressure on GBPUSD by making dollar-denominated assets more attractive on a return-adjusted basis. A hawkish Fed, one that keeps real yields elevated even as nominal rate hike bets fluctuate, sustains that pressure without needing an outright rate increase. Layered on top is a qualified COT crowding risk: the available summary leans toward heavy sterling longs, but missing provenance prevents treating that description as a standalone statistic. When everyone is already long, the fuel for the next leg higher is thin, and any negative catalyst, a hot CPI that reprices UK rate cuts, or FOMC Minutes more hawkish than expected, can trigger a carry unwind, where traders exit leveraged long positions simultaneously, accelerating the move down far faster than fundamentals alone would justify. However, the higher-timeframe structure remains aligned bullish. Price remains above weekly TrendSL at 1.33774, but it has slipped below weekly VWAP at 1.35532. Short-term momentum now supports the bearish warning while the broader trend still conflicts with it. That technical structure directly contradicts the bearish label. -- Intermarket Edge (

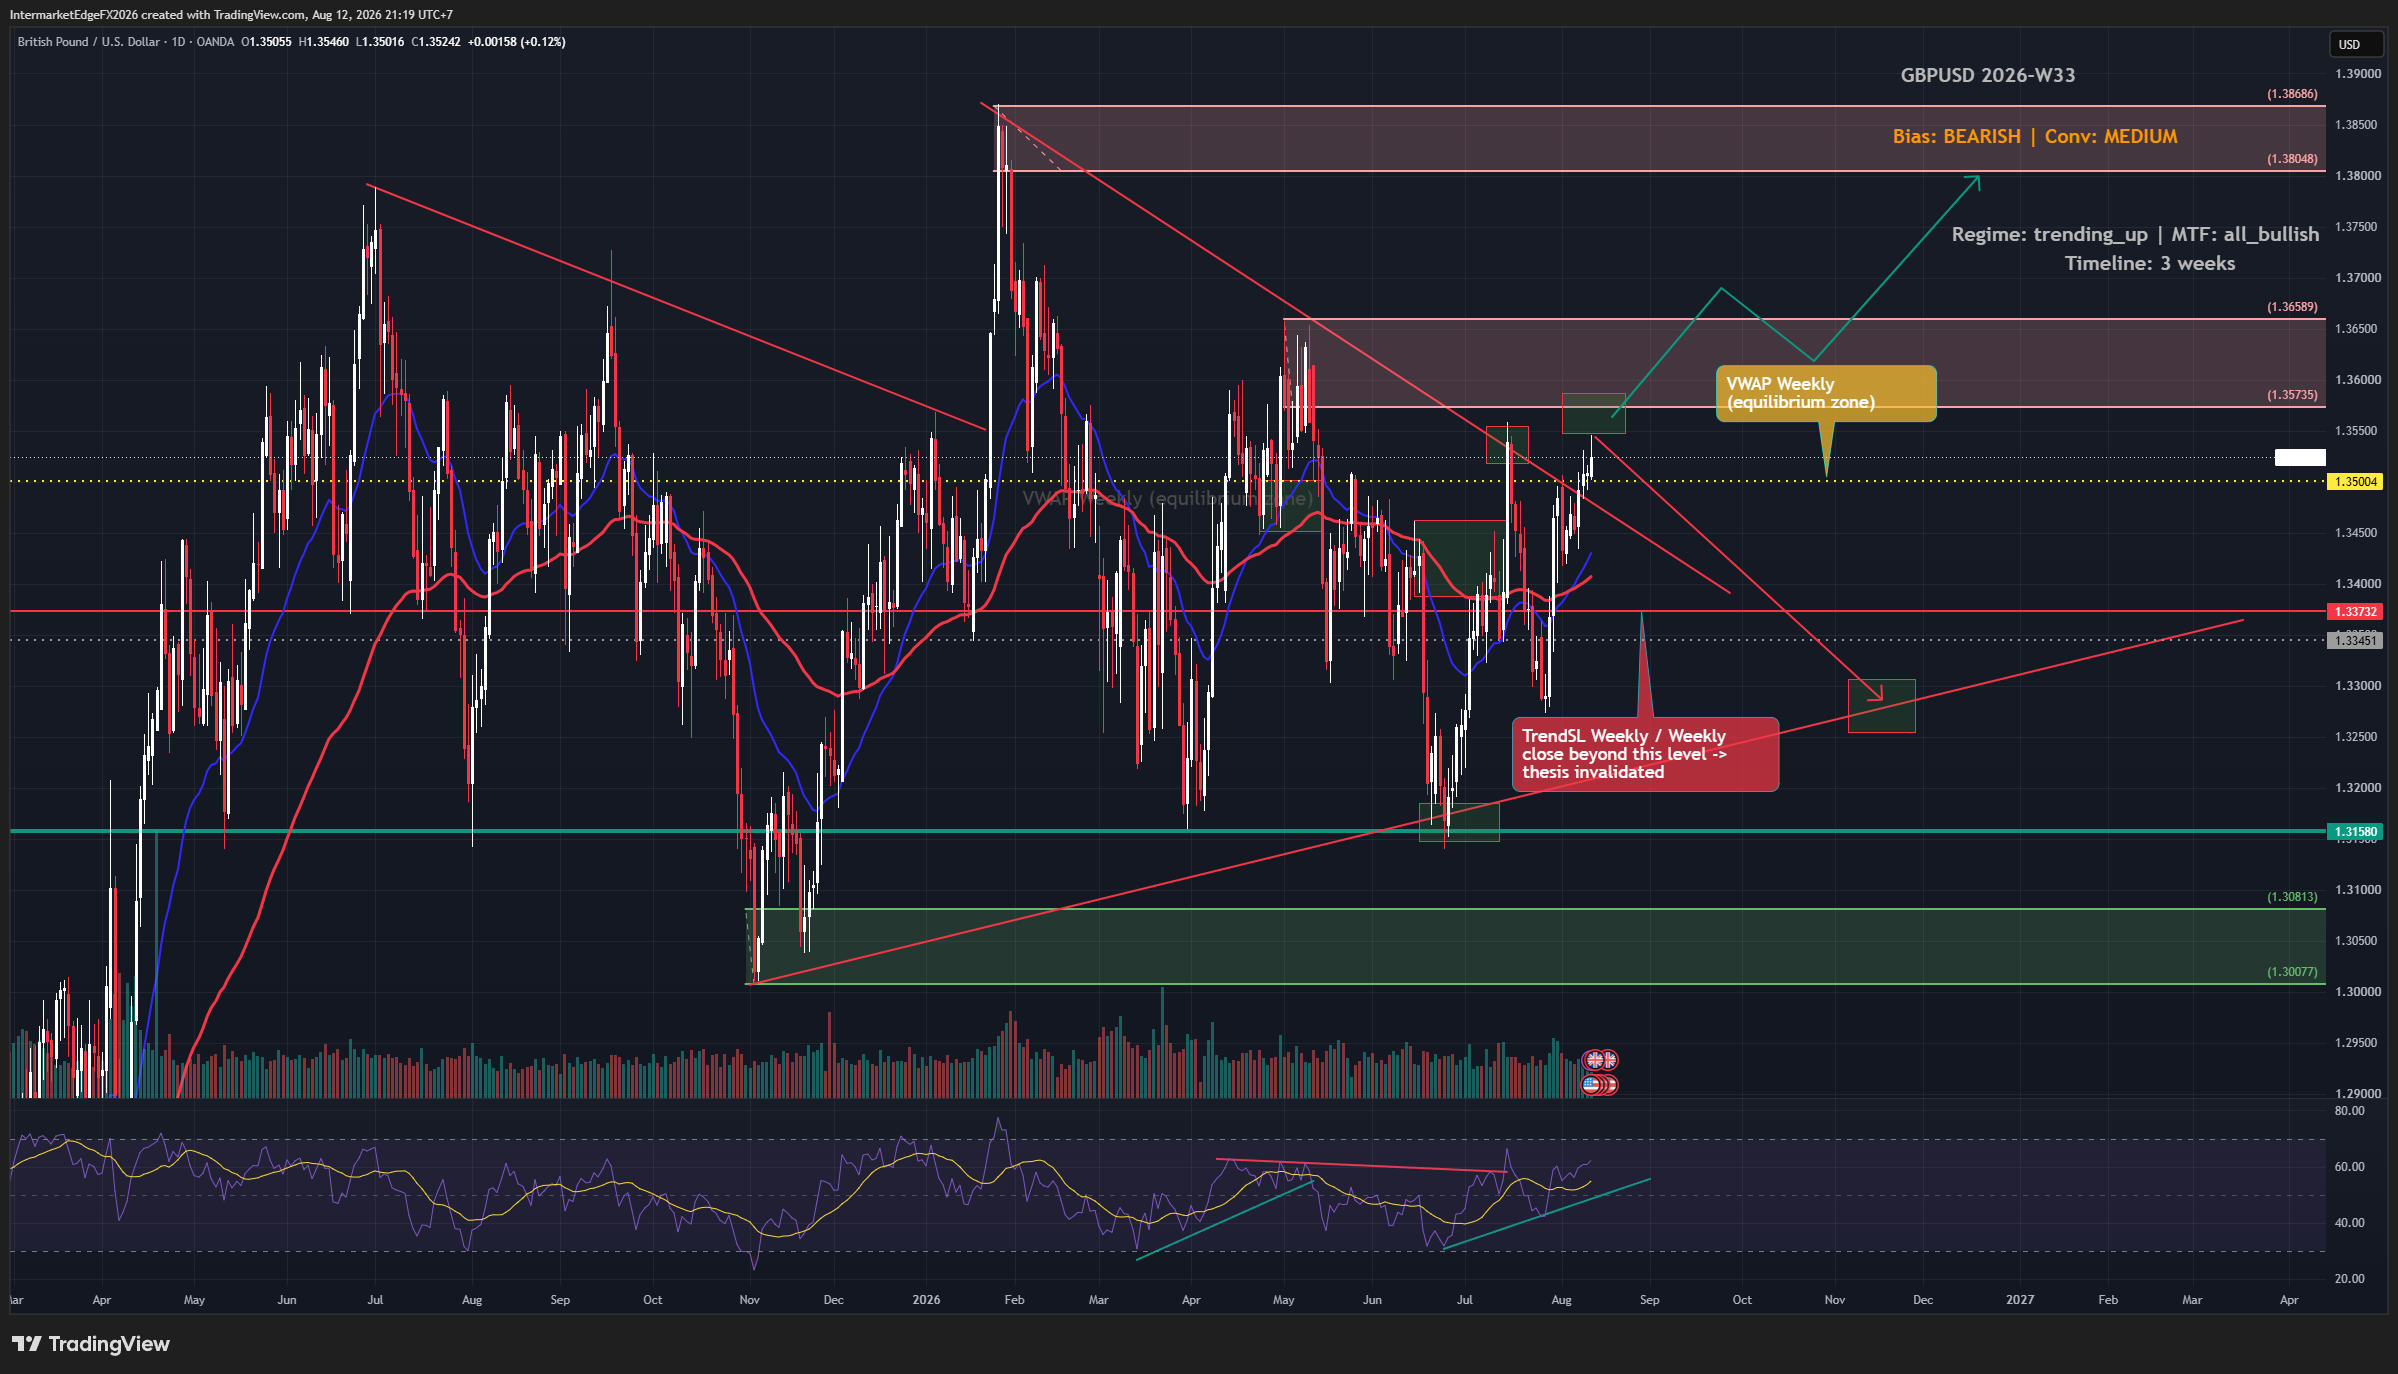
GBPUSD Week W33-2026: Sterling Climbs to a One-Month High While the Bearish Macro Case Quietly Builds Against It

GBPUSD Week W33-2026: Sterling Climbs to a One-Month High While the Bearish Macro Case Quietly Builds Against It

GBPUSD is trading at 1.35276 as of Wednesday, 12 August 2026, sitting above its weekly VWAP at 1.35004 and hovering near a one-month high for Sterling. A surprise Core CPI miss-actual 0.0% against a 0.2% forecast-briefly knocked the dollar's footing, but the broader macro argument for USD strength through elevated real yields hasn't structurally changed. The tension between what price is doing right now and what the macro environment implies is exactly the kind of setup that quietly catches traders off-guard. The framework's overall bias for GBPUSD this week is bearish over a three-week horizon, driven primarily by the BOE-versus-Fed rate differential-the gap between where each central bank's policy rate sits and where markets expect it to go-which currently favors the dollar because the Fed's commitment to restrictive policy is backed by real yields that remain historically elevated. When real yields are positive and rising, as the 2.4% US 10-year real yield suggests, capital tends to seek dollar exposure, which mechanically pressures currency pairs where the dollar is the quote side, like GBPUSD. Several reinforcing causal chains support this logic: Fed hawkishness sustains USD demand, and a DXY that finds its footing would directly compound downward pressure on Cable. The critical caveat-and it is not a minor one-is that the price-based and positioning-based evidence is pointing in the opposite direction. COT data (directional evidence only; the brief does not specify the report week, net-position figure, or release date, so treat this as a sentiment lean rather than a precise citable statistic) is reading bullish on Cable positioning. -- Intermarket Edge

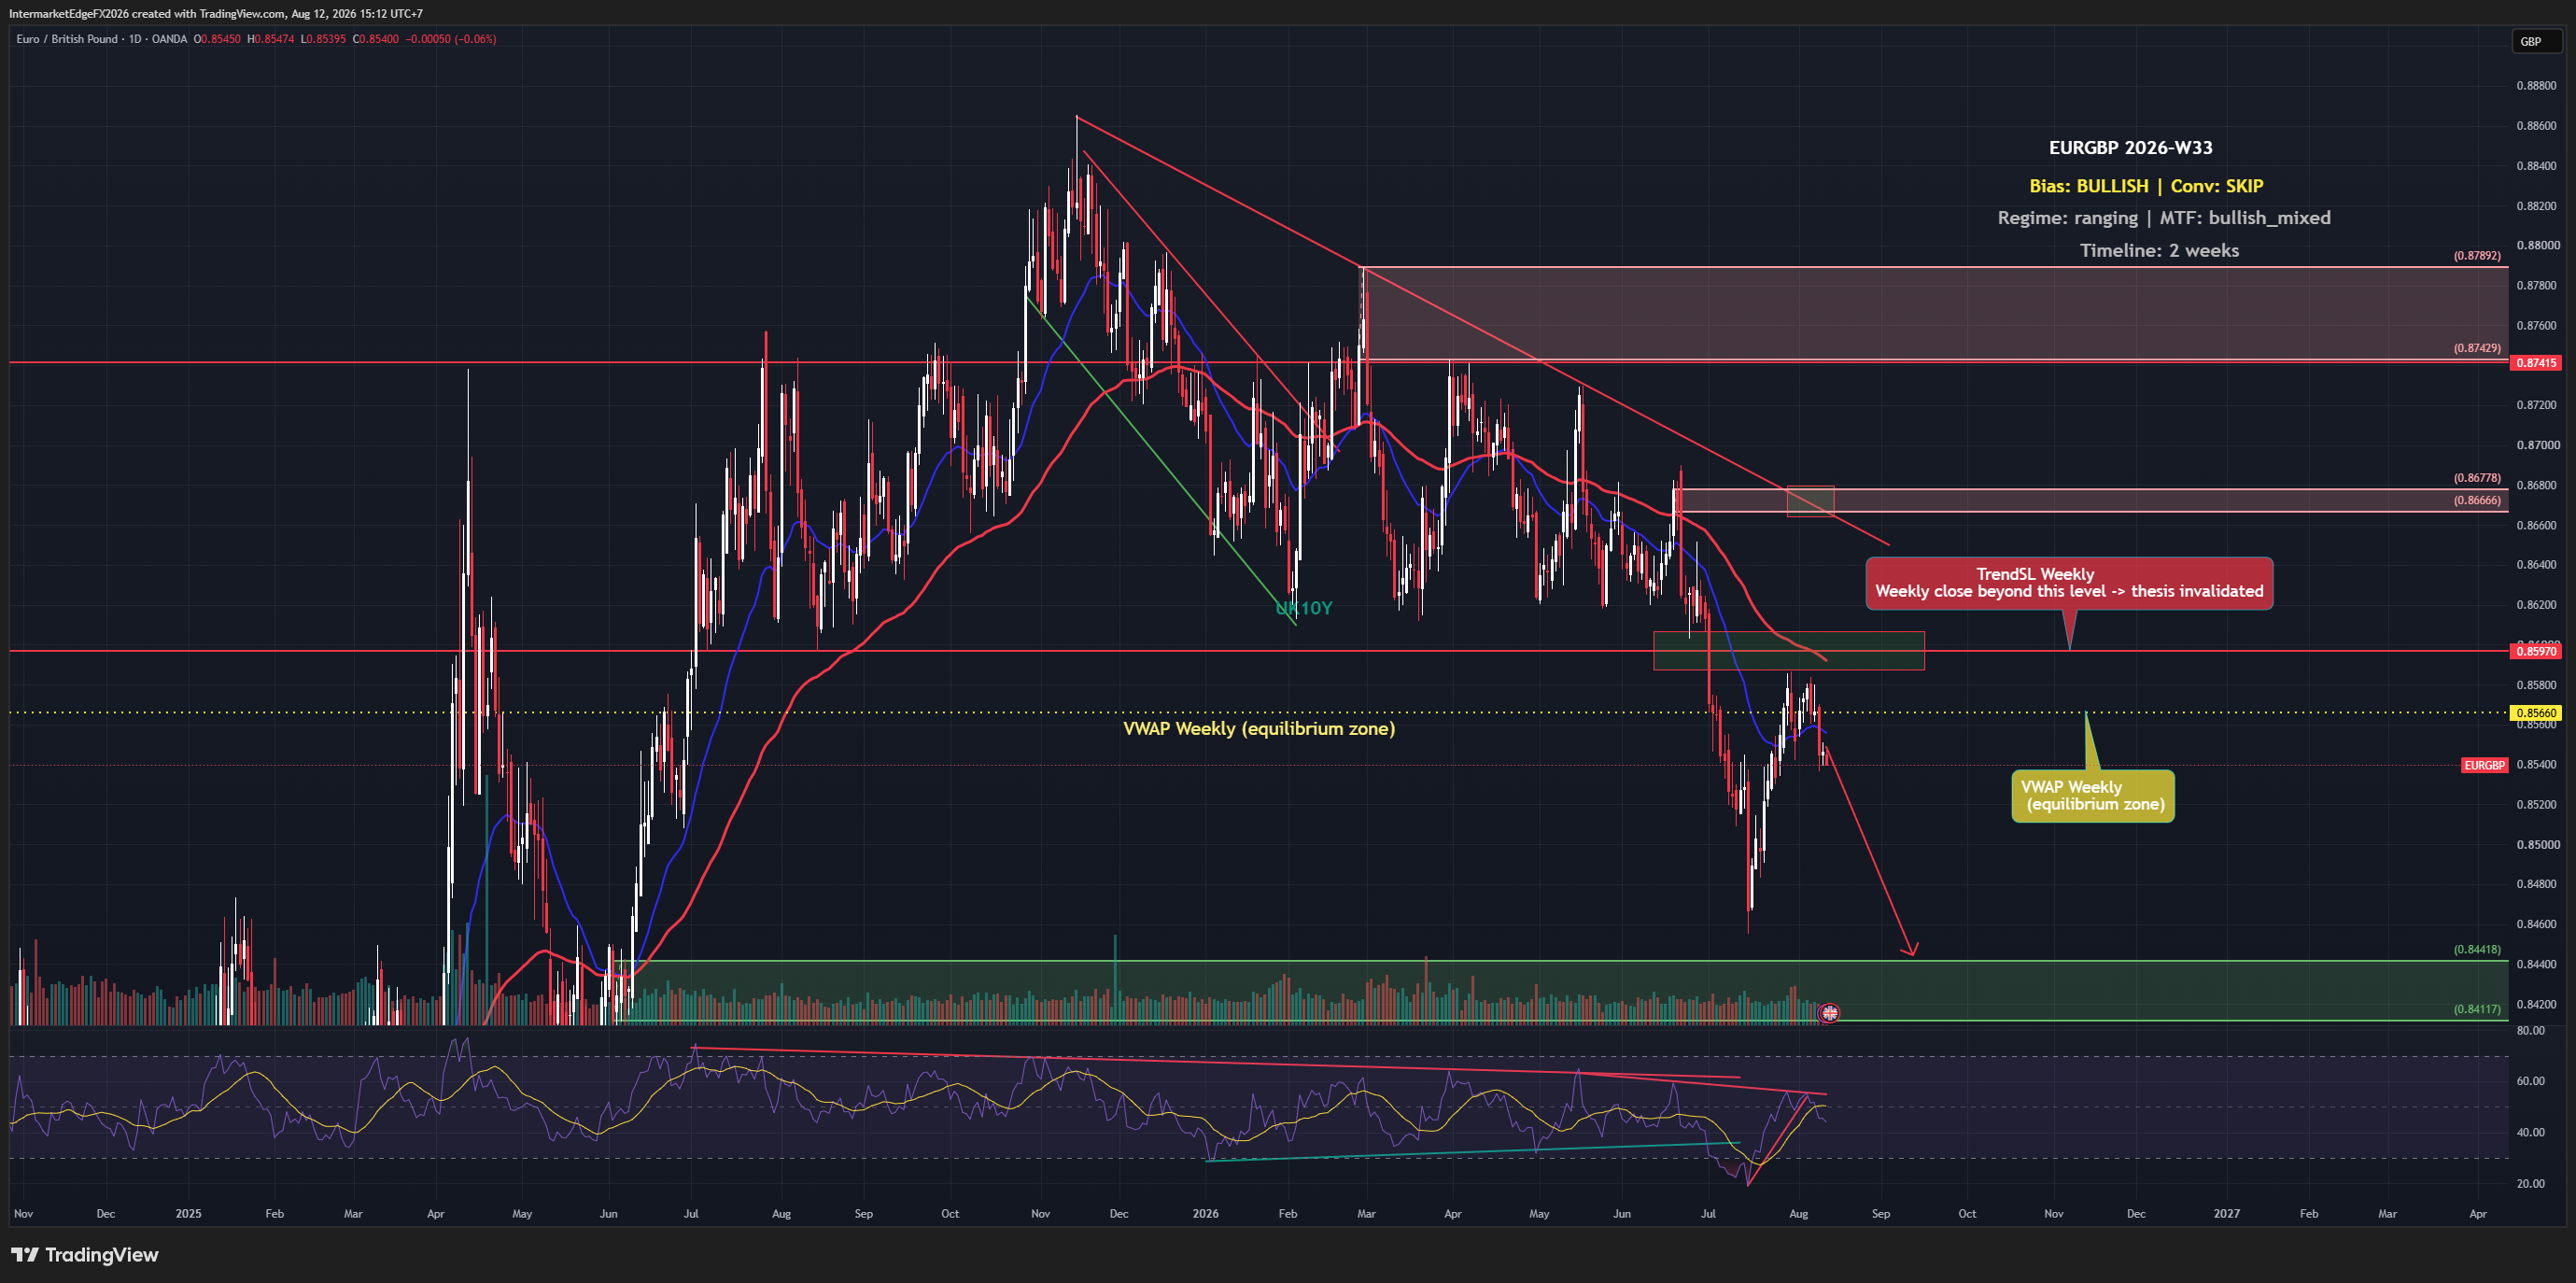
EURGBP Week W33-2026: BOE Holds at 3.75% But Sterling Fights Back, Leaving Bulls Stranded Below 0.8566

EURGBP Week W33-2026: BOE Holds at 3.75% But Sterling Fights Back, Leaving Bulls Stranded Below 0.8566

EURGBP is technically labelled bullish this week, yet as of Wednesday 12 August 2026, price at 0.85407 is sitting below the weekly VWAP at 0.8566, testing from underneath rather than pushing through it. That gap between the label and the price reality is exactly the kind of setup where traders get caught leaning on a bias that the market itself hasn't confirmed yet. With a BOE divided 6-3 on holding rates and a Euro-area CPI miss already in the books, neither side has a clean fundamental edge right now. The framework arrives at a weak bullish lean on EURGBP for this two-week window, but it is important to understand precisely how thin that lean is. The only active signal driving the bullish label comes from price action itself; positioning data, macro rules, liquidity signals, and sentiment indicators all contribute nothing, they fired no confirming evidence. A bias resting on a single source with no corroboration from other analytical layers is, by design, a low-confidence read that demands a correspondingly cautious posture. The analysis explicitly flags a structural conflict at the heart of the thesis: the overall directional label is bullish, but the structural bias is neutral, meaning the two core components of the framework are not pointing the same way. That internal contradiction is not a rounding error, it is a direct signal that the environment has not yet organised itself into a tradeable directional setup. The ECB-versus-BOE rate differential is cited as the primary fundamental narrative, the idea being that if ECB policy holds firmer relative to BOE policy, euro support should outpace sterling support over time. But no macro rule within the analysis has fired to validate that narrative in a quantifiable way this week, so it remains a story rather than a confirmed driver. What this means practically: the bullish label should be read as a directional lean, not a conviction call. -- Intermarket Edge

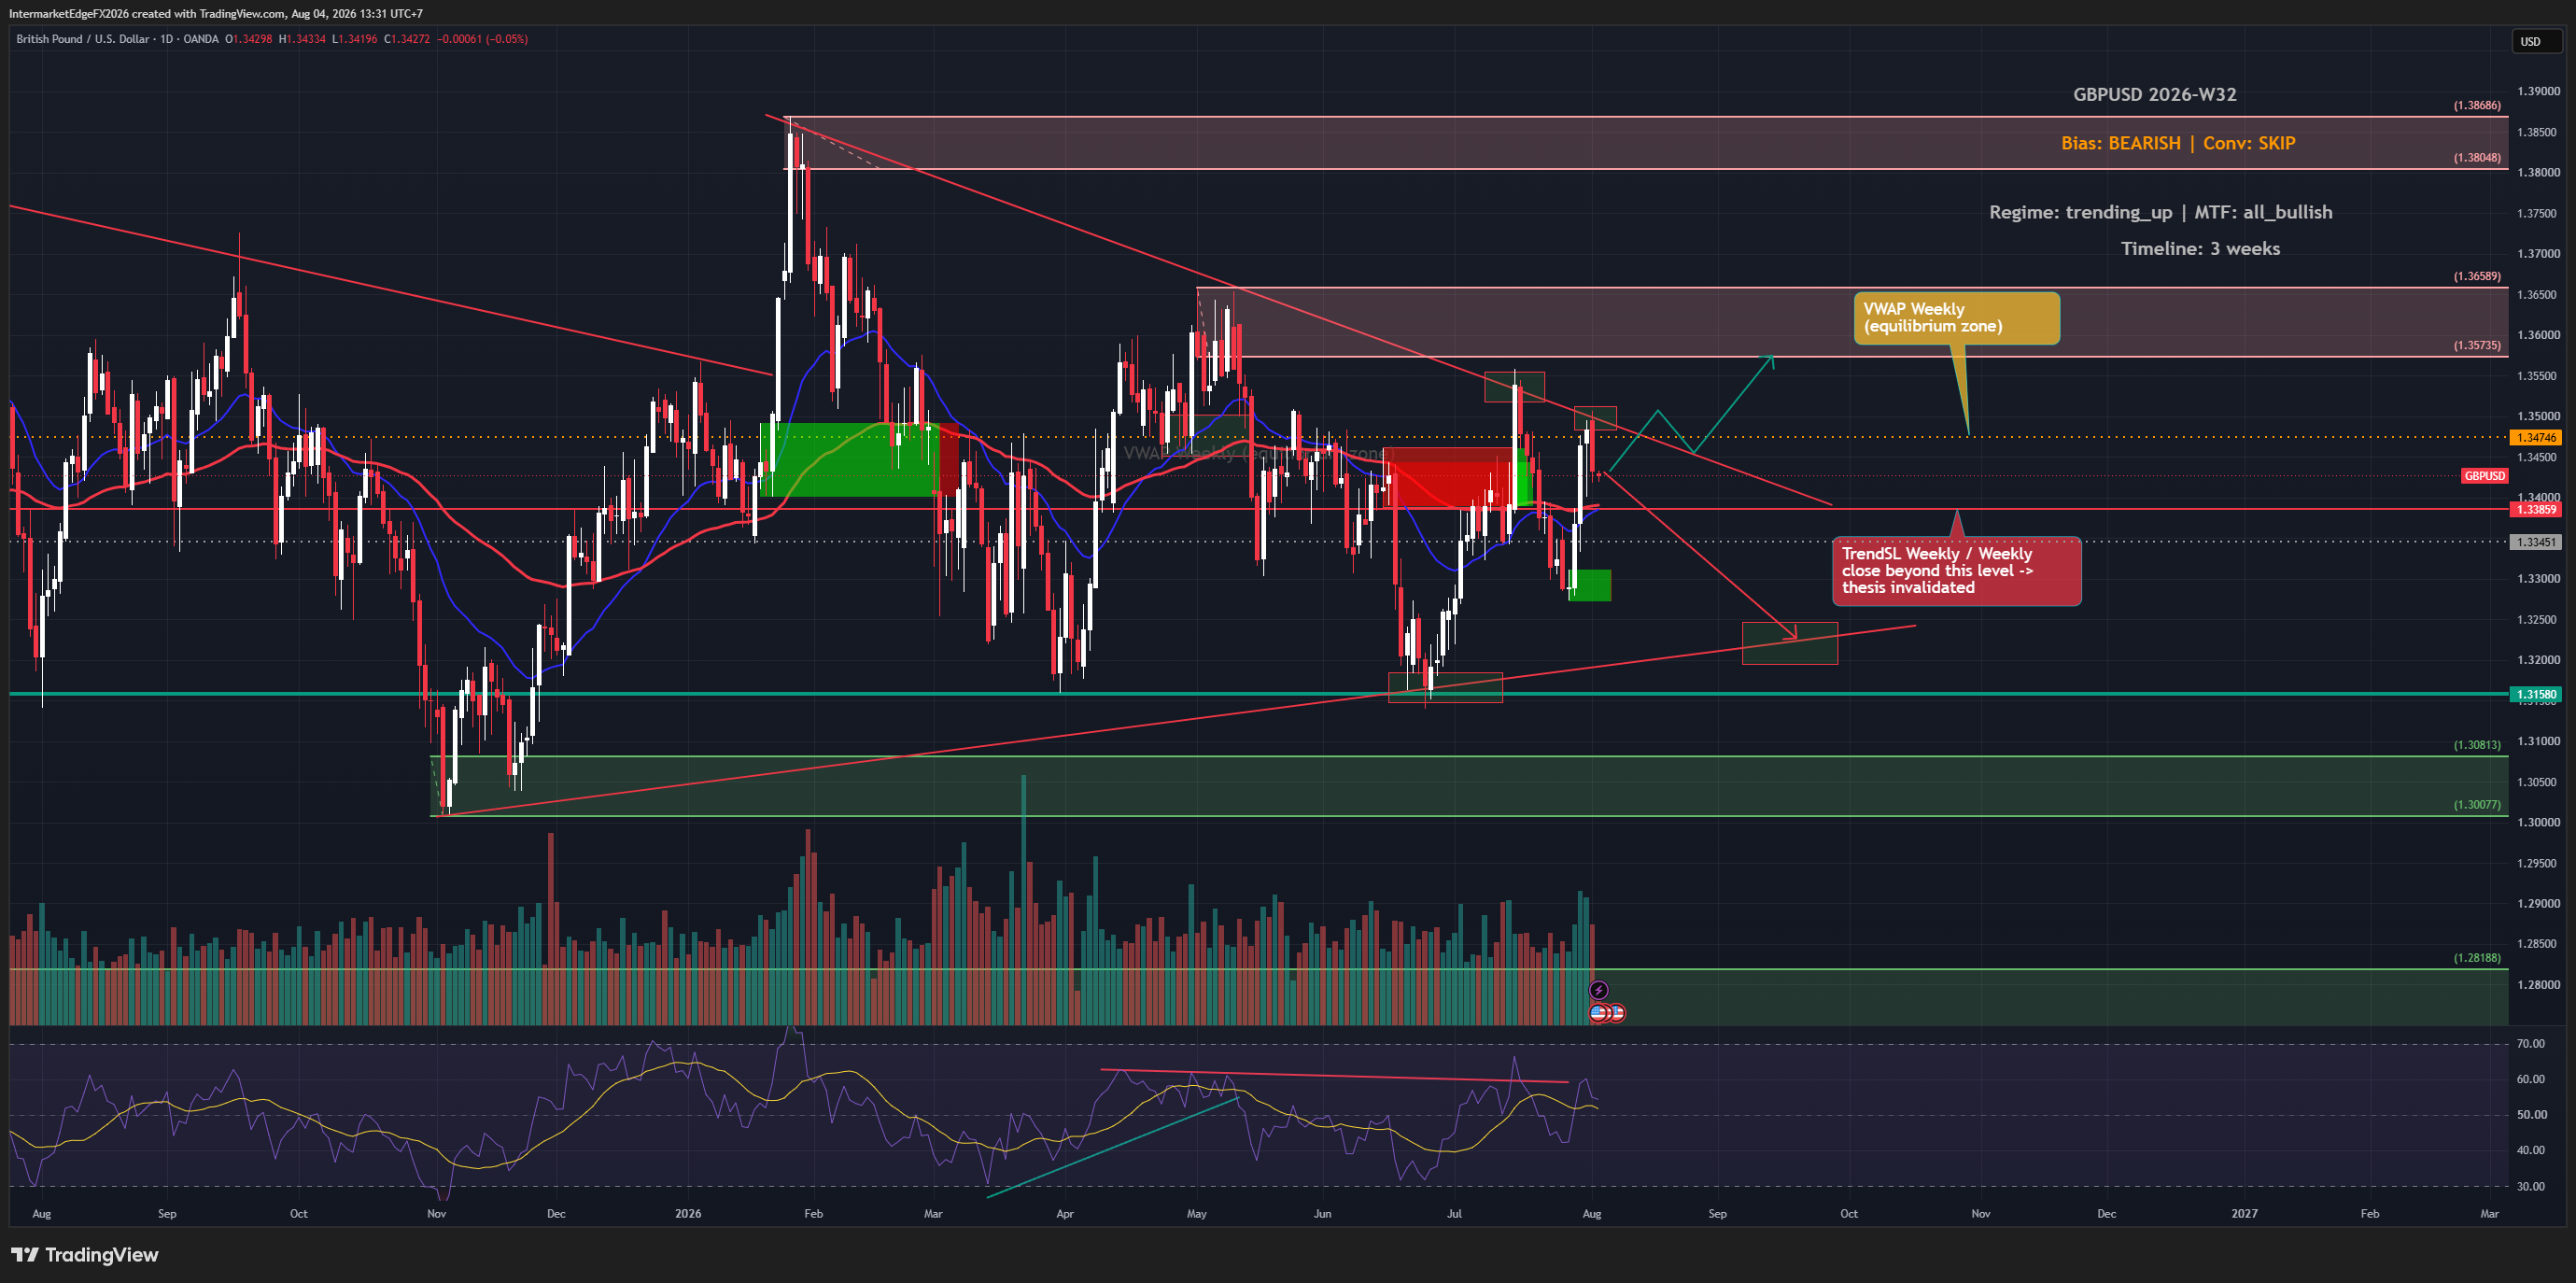
GBPUSD Week W32-2026: Sterling Slips Below 1.35 Despite Broad Dollar Weakness, Bearish Label Undercut by All-Bullish Technical Alignment Above TrendSL 1.33859

GBPUSD Week W32-2026: Sterling Slips Below 1.35 Despite Broad Dollar Weakness, Bearish Label Undercut by All-Bullish Technical Alignment Above TrendSL 1.33859

GBPUSD is caught in a genuine tug-of-war this week. The pound has slipped below 1.3500 despite broader dollar weakness, and the technical regime remains firmly bullish, yet macro headwinds from a hawkish Fed, rising real yields, and crowded long positioning in the futures market are building a credible case for downside. The honest read here is that this setup is too conflicted for a clean directional trade, and forcing a bias in either direction would be a mistake. The formal bias on GBPUSD for Week W32-2026 is bearish, but the conviction level is explicitly rated as skip, meaning this is not a setup where a position is warranted, and traders should treat that designation seriously rather than looking for a way to rationalize an entry. The bearish case rests on three macro causal chains that each carry meaningful weight: a hawkish Fed posture pushing USD higher, the core CPI miss notwithstanding; the structural linkage between DXY strength and GBPUSD downside; and Treasury General Account refill dynamics that drain liquidity from the banking system and tighten credit conditions, creating an indirect headwind for risk-correlated assets including sterling. The rate differential between the BoE and the Fed remains a focal point, if the Fed holds rates elevated while the BoE pivots or pauses, the interest rate carry shifts against GBP/USD longs over a multi-week horizon. That said, the bullish signals are not noise to be dismissed. Multi-timeframe alignment is fully bullish, price action over the recent sessions has been constructive, and the macro read independently scores bullish given pound strength driven by lingering rate-hike expectations. COT data shows speculator positioning leaning bearish, but the brief does not specify the exact report week, net-position figure, or release date, so this should be read as directional evidence rather than a precise, citable statistic. -- Intermarket Edge

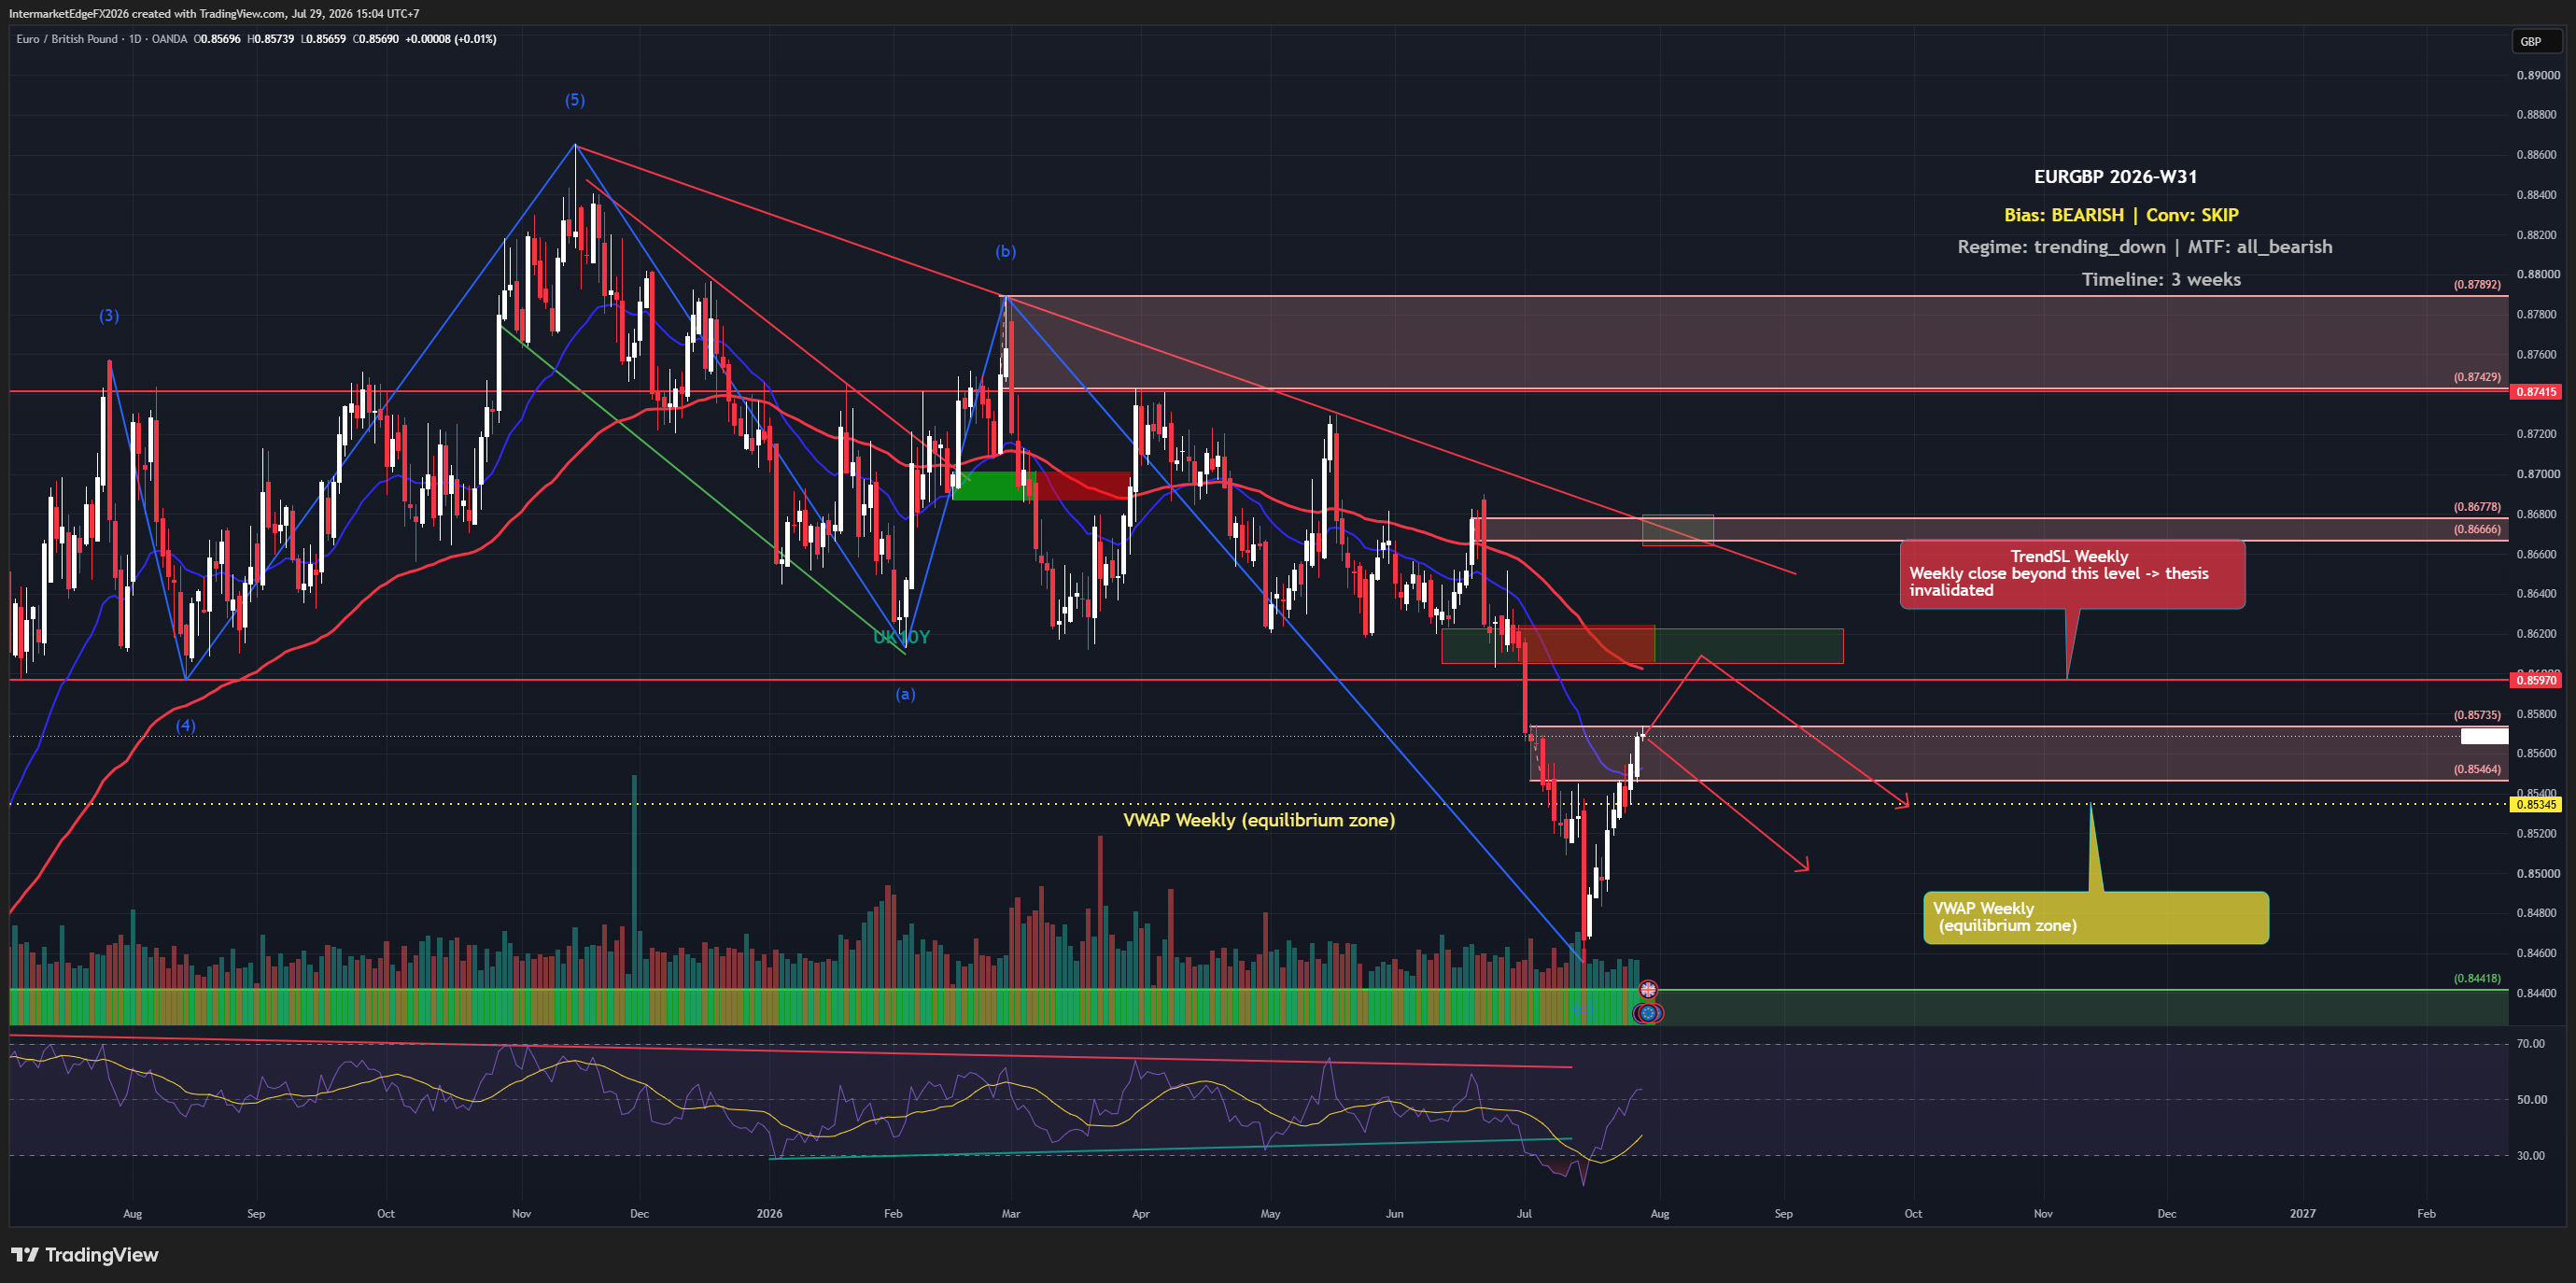
EURGBP Week W31-2026: Price Pushes Above VWAP at 0.85345 as BoE Decision Looms and ECB's Lane Flags Oil as a Medium-Sized Shock

EURGBP Week W31-2026: Price Pushes Above VWAP at 0.85345 as BoE Decision Looms and ECB's Lane Flags Oil as a Medium-Sized Shock

EURGBP is trading at 0.85703 as of Wednesday, 29 July 2026, above the weekly VWAP of 0.85345 and pressing up toward the trend stop-loss at 0.8597. The broader trend regime remains down, multi-timeframe alignment is fully bearish, and the ECB just printed a softer-than-expected core CPI reading. Yet the near-term price action is running directly against the directional bias, and conviction is low enough that sitting on the sidelines is the disciplined call right now. The structural bias for EURGBP during the week of 2026-W31 is bearish, sitting within a confirmed trending-down regime where multi-timeframe alignment is fully bearish across all measured timeframes. In a clean trending environment, the appropriate FX implication is trend-following, meaning the directional lean is to sell rallies rather than chase breakdowns. However, and this is the critical caveat that shapes the entire week's approach: conviction is too low to justify entering a directional trade at this time. The sole active signal driving any conviction this week comes from price action itself, and it is pointing bullish, running directly against the stated bearish bias. All other inputs that would normally reinforce a short case, including positioning data, macro rules, liquidity conditions, and sentiment readings, are producing no active signals at all this week. That vacuum means the bearish thesis rests almost entirely on regime classification rather than on converging, real-time evidence. The structural driver cited for the pair remains the ECB versus Bank of England rate differential, but no macro rules are currently firing to quantify or confirm how that differential is expressing itself in price this week. The ECB's softer-than-expected core CPI miss modestly shifts the rate-differential calculus in favour of sterling over the euro on the margin, which is consistent with the short-term price pressure we are observing. -- Intermarket Edge

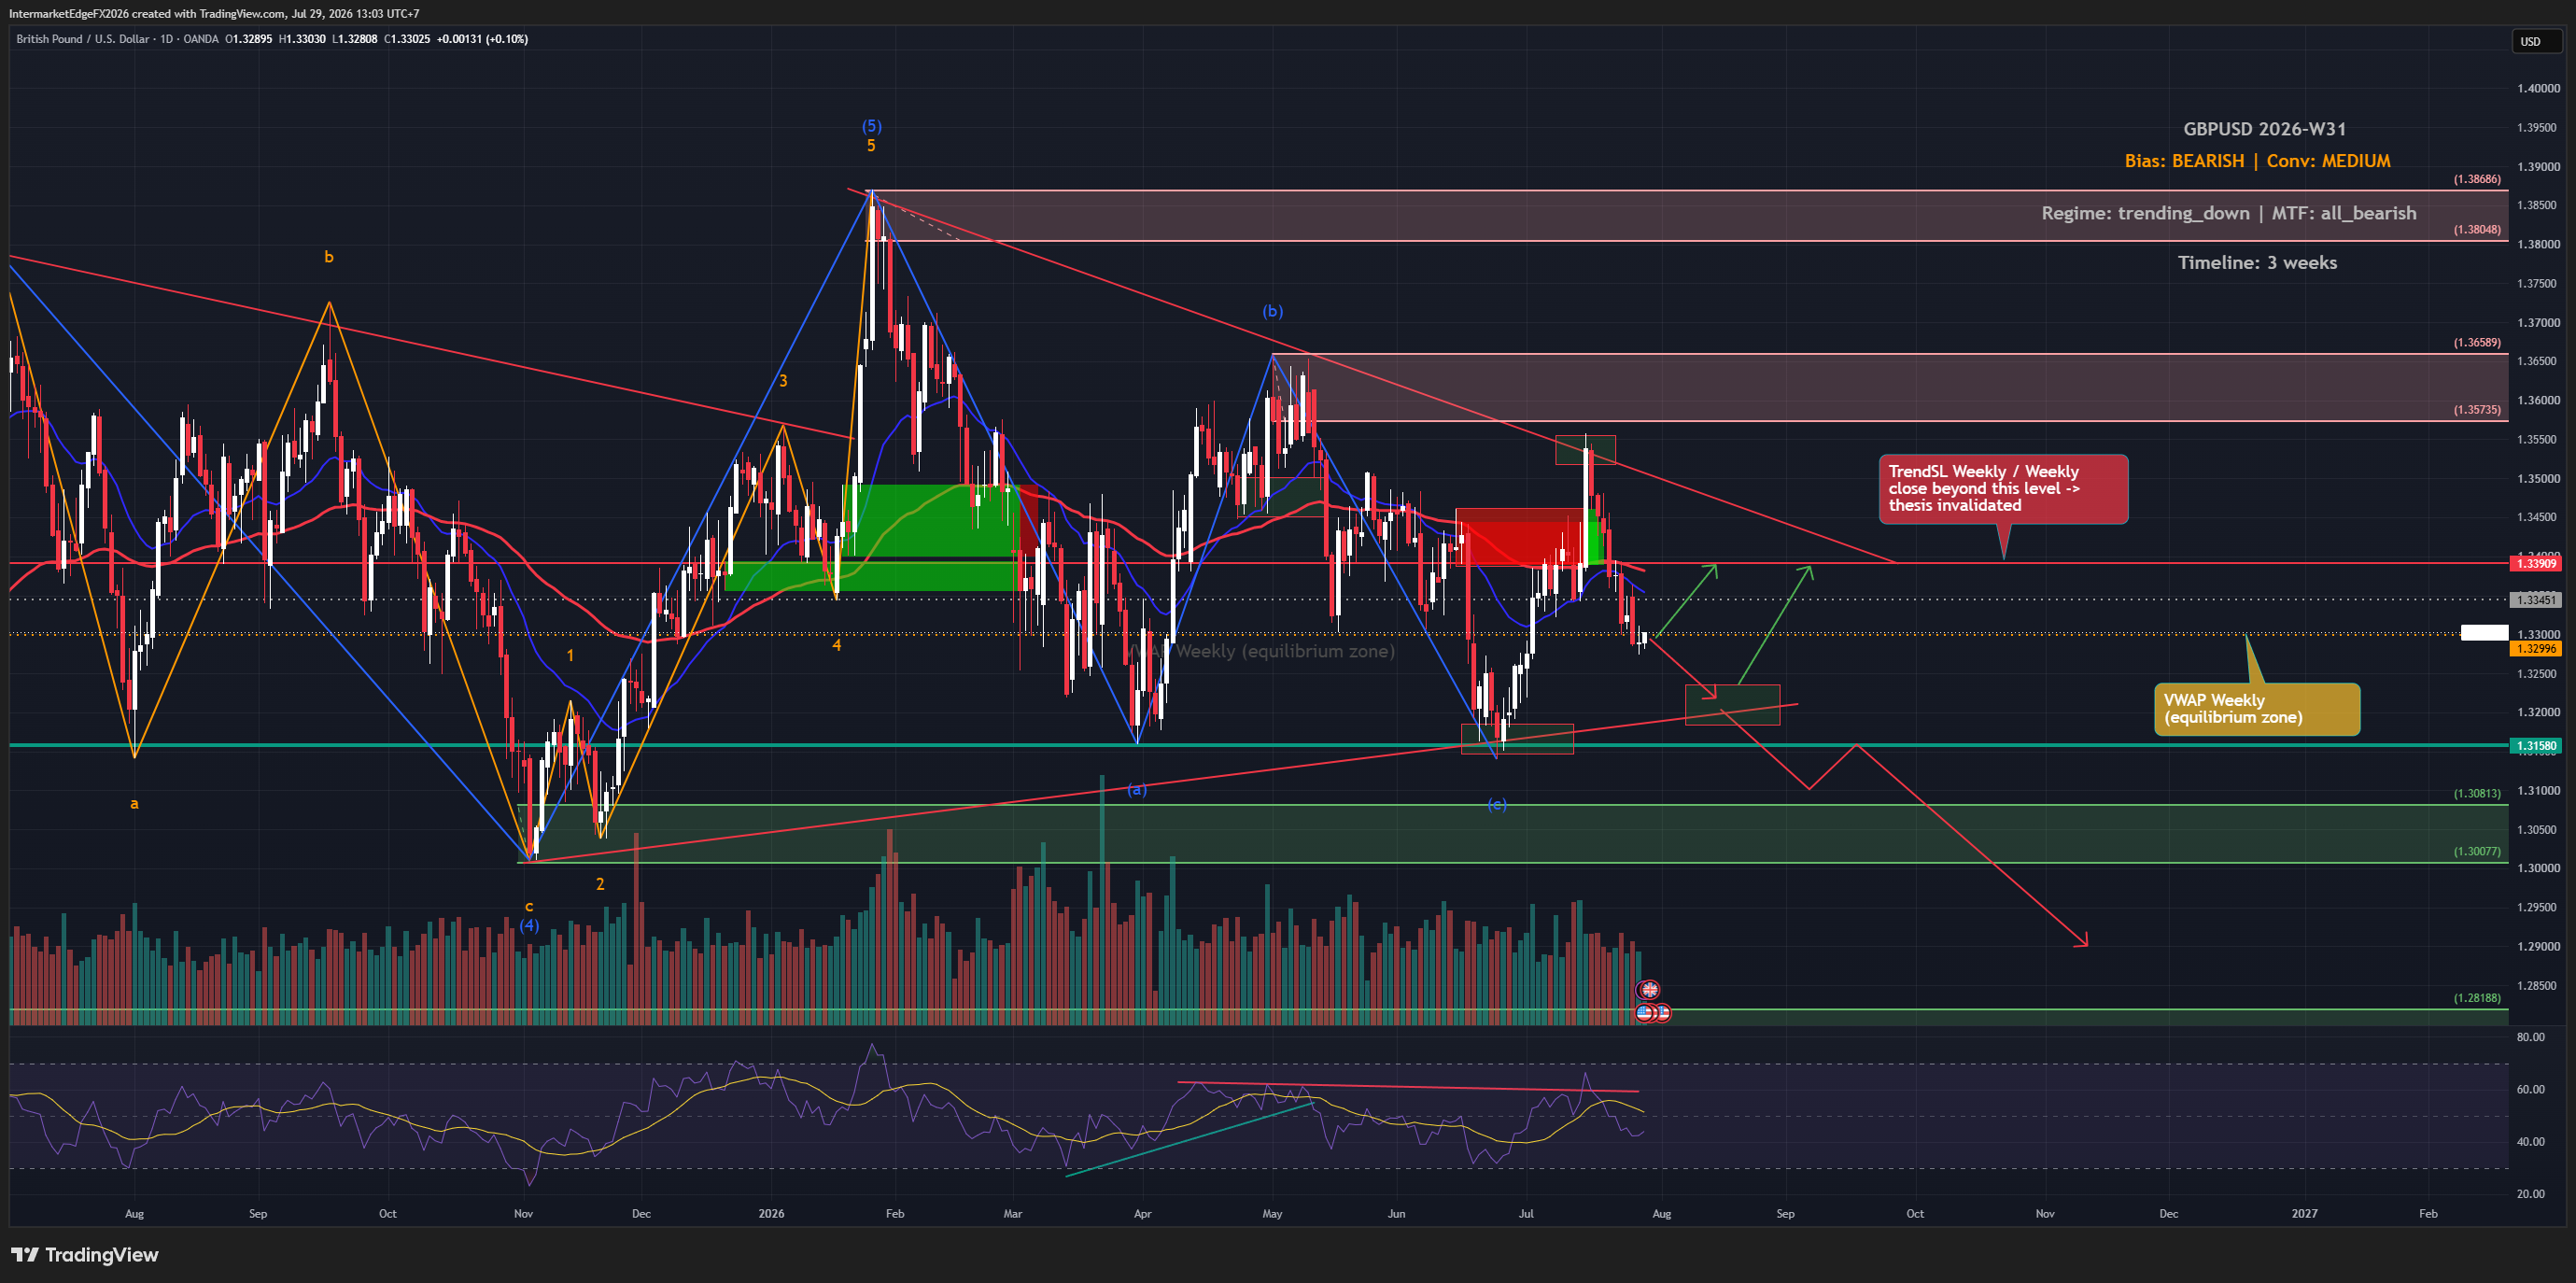
GBPUSD Week W31-2026: Sellers Push Price to Lowest Since July 2 as Fed Decision Looms and Rate Differential Widens Against Sterling

GBPUSD Week W31-2026: Sellers Push Price to Lowest Since July 2 as Fed Decision Looms and Rate Differential Widens Against Sterling

GBPUSD is trading at 1.32988 as of Wednesday, 29 July 2026 at 05:39 UTC, testing from underneath its weekly VWAP at 1.32996, a technically fragile position heading into one of the most catalyst-dense 48-hour windows of the quarter. The Fed decision, BOE rate announcement, UK GDP, and US Core PCE all land within two sessions. With multi-timeframe alignment firmly bearish and the macro rate-differential story still pointing toward USD strength, the setup demands discipline over conviction. The core bearish thesis on GBPUSD rests on a rate-differential argument: the BOE versus Fed policy divergence currently favors USD strength, with the Fed maintaining a restrictive stance anchored by elevated real yields while the Bank of England faces a more ambiguous inflation and growth environment. The Fed hawkish causal chain is the dominant driver here, a tightening bias from the Fed mechanically supports the dollar (USD bullish) and, as the quote currency in GBPUSD, exerts downward pressure on the pair. DXY bullish pressure adds a compounding secondary vector, reinforcing the USD-strength narrative from a broader basket perspective. Multi-timeframe alignment is uniformly bearish, which increases trend-follow confidence when price and structure agree with the macro backdrop. That said, the conviction level here is medium, not high, and the reason matters: there is a genuine signal conflict that traders should not dismiss. Both price action and COT positioning (directional survey data, note the brief does not specify report week, net-position figures, or release date, so this should be read as indicative rather than a precise citable statistic) are reading bullish. This means you have institutional-grade positioning and near-term price momentum potentially working against the bearish macro thesis. The practical implication is clear: this is not a setup to chase aggressively. -- Intermarket Edge

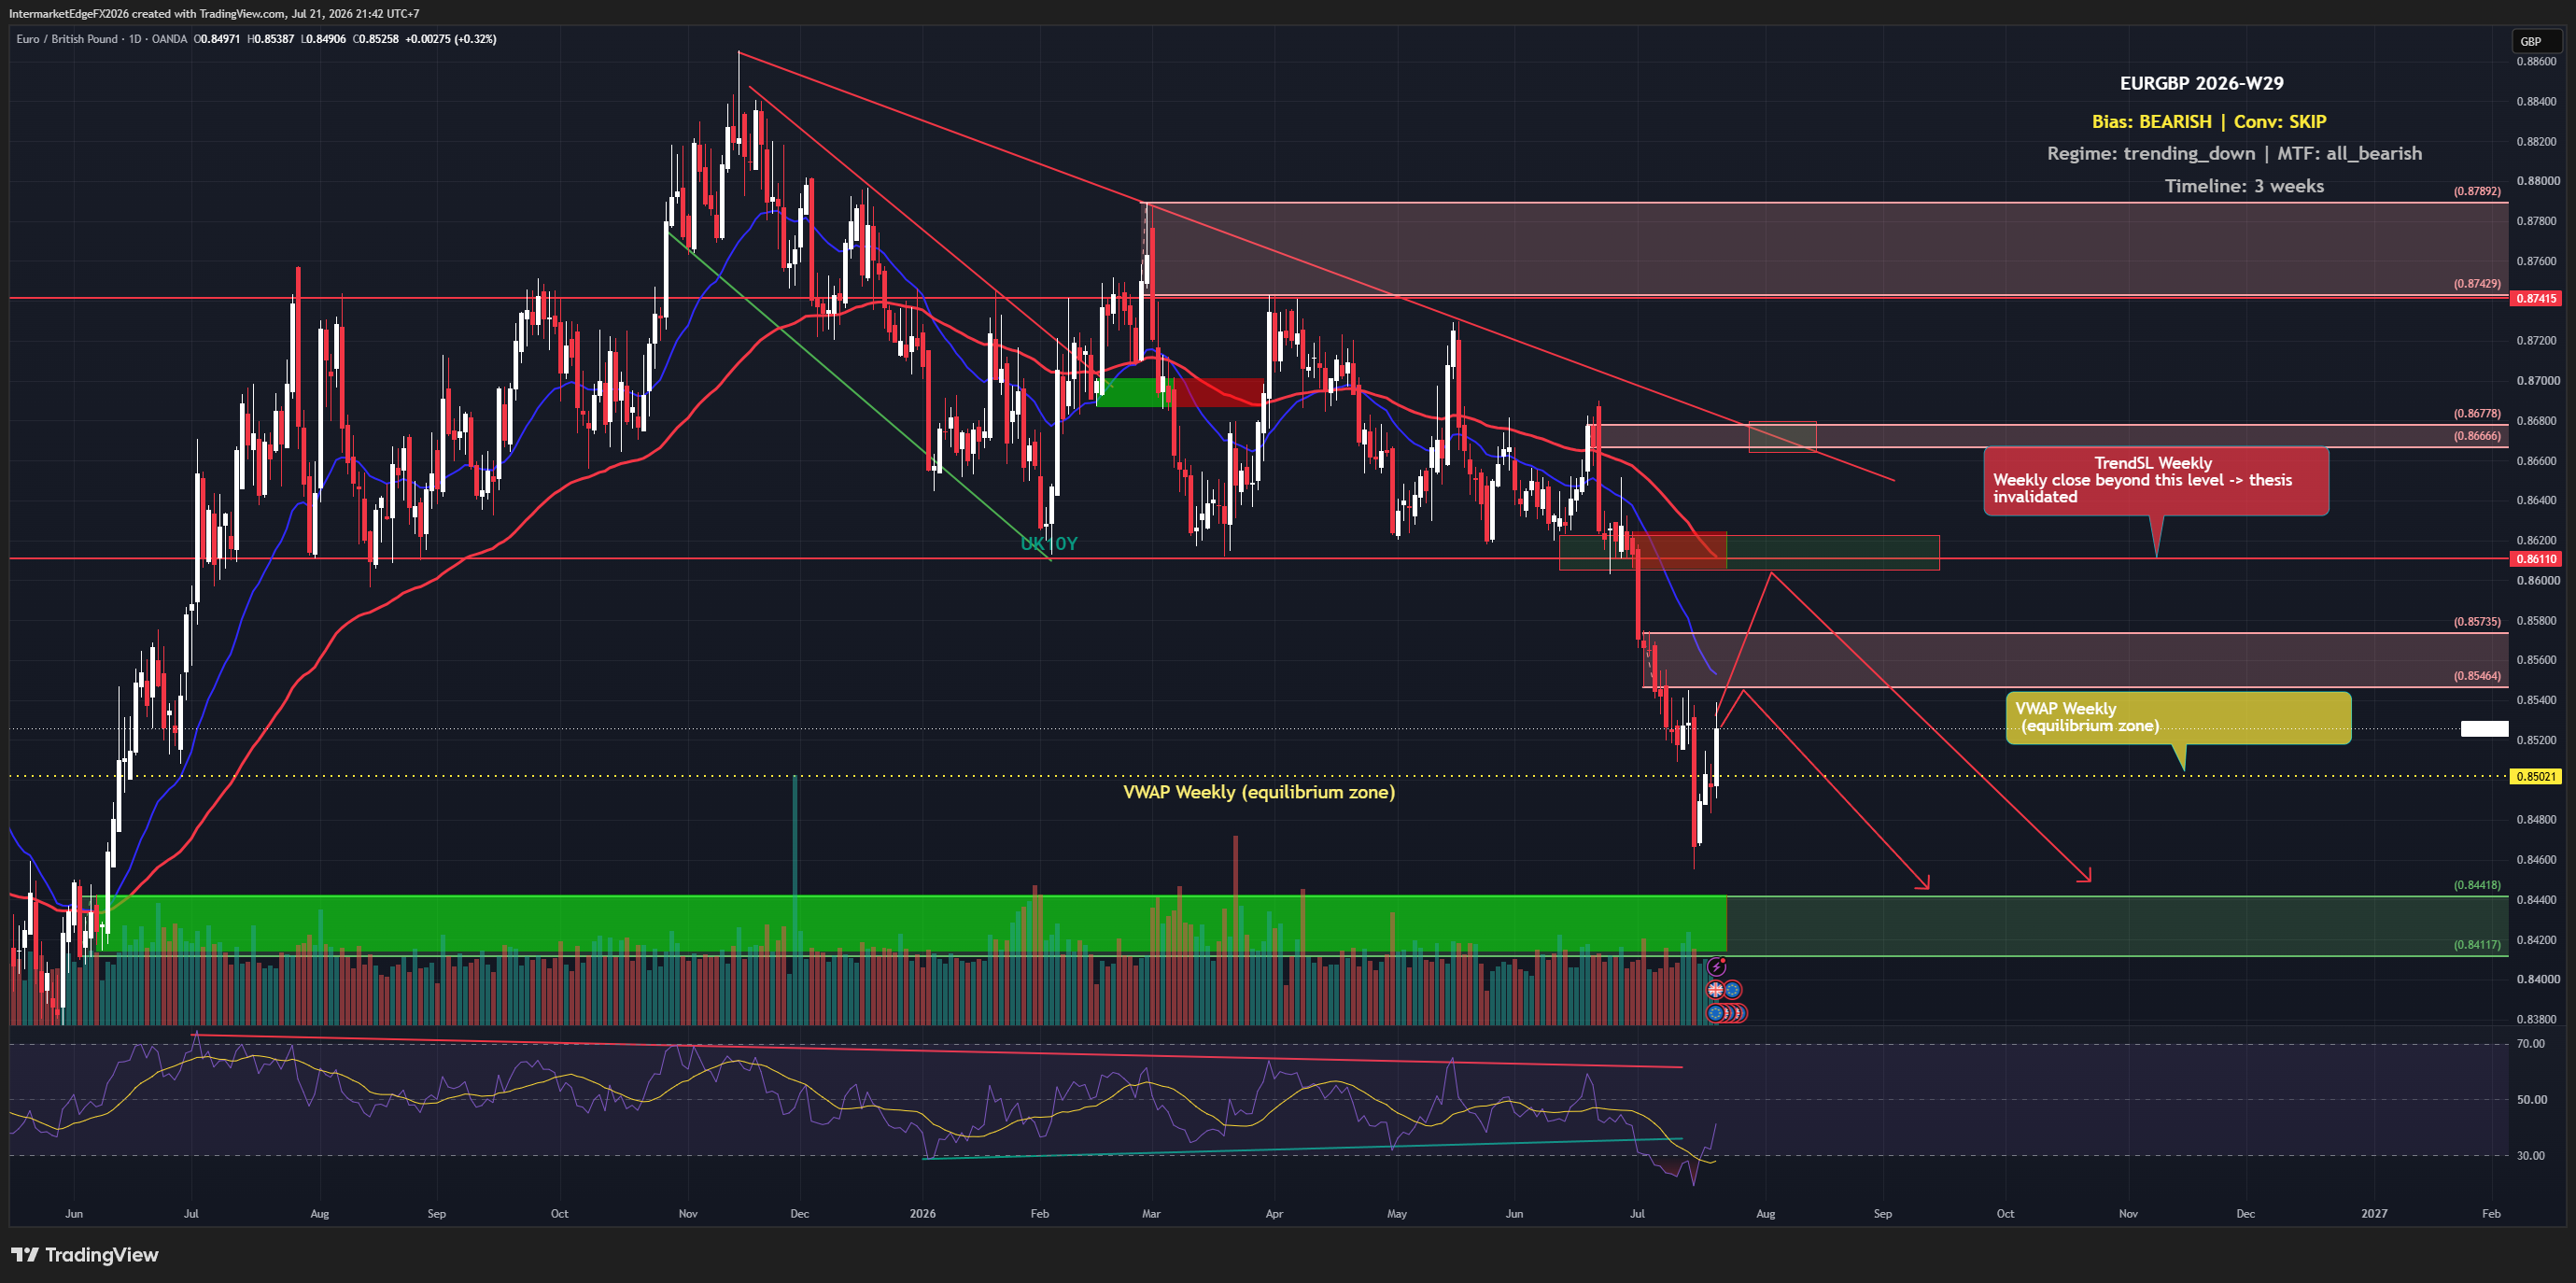
EURGBP Week W29-2026: Sterling Whipsaws on Surprise Chancellor Pick, Bearish Trend Holds Near One-Year Lows at 0.85021

EURGBP Week W29-2026: Sterling Whipsaws on Surprise Chancellor Pick, Bearish Trend Holds Near One-Year Lows at 0.85021

Sterling whipsawed sharply this week around UK political headlines. EURGBP briefly touched a one-year low for the pair — pound's strongest level vs euro in a year — on FT reports that Shabana Mahmood would be Chancellor. The actual appointment of John Healey defied those expectations, triggering a reversal: gilt yields rose and sterling dipped as markets repriced fiscal credibility risk under the new Burnham government. The pair closed at 0.8502, sitting right on the weekly VWAP (0.8502). The broader trend remains down — multi-timeframe alignment is fully bearish, regime reads trending_down — and the Euro side offered no support: Eurozone Core CPI (YoY) printed 2.4% vs 2.6% forecast, a clean miss that removes ECB hawkish optionality. DXY bias is also bearish with low conviction, broadly USD-neutral for the cross. Despite aligned bearish structure, conviction is skip this week. The political noise creates two-way headline risk: any further surprise around the Burnham cabinet or fiscal announcements could spike volatility unpredictably. Price hugging weekly VWAP (0.8502) is also a caution flag — sustained acceptance above that level would signal short-term momentum turning against the thesis. Key levels: bull invalidation above TrendSL 0.8609 (exit shorts, reassess); reduce size if price holds above VWAP 0.8502. Wait for cleaner entry. -- Intermarket Edge

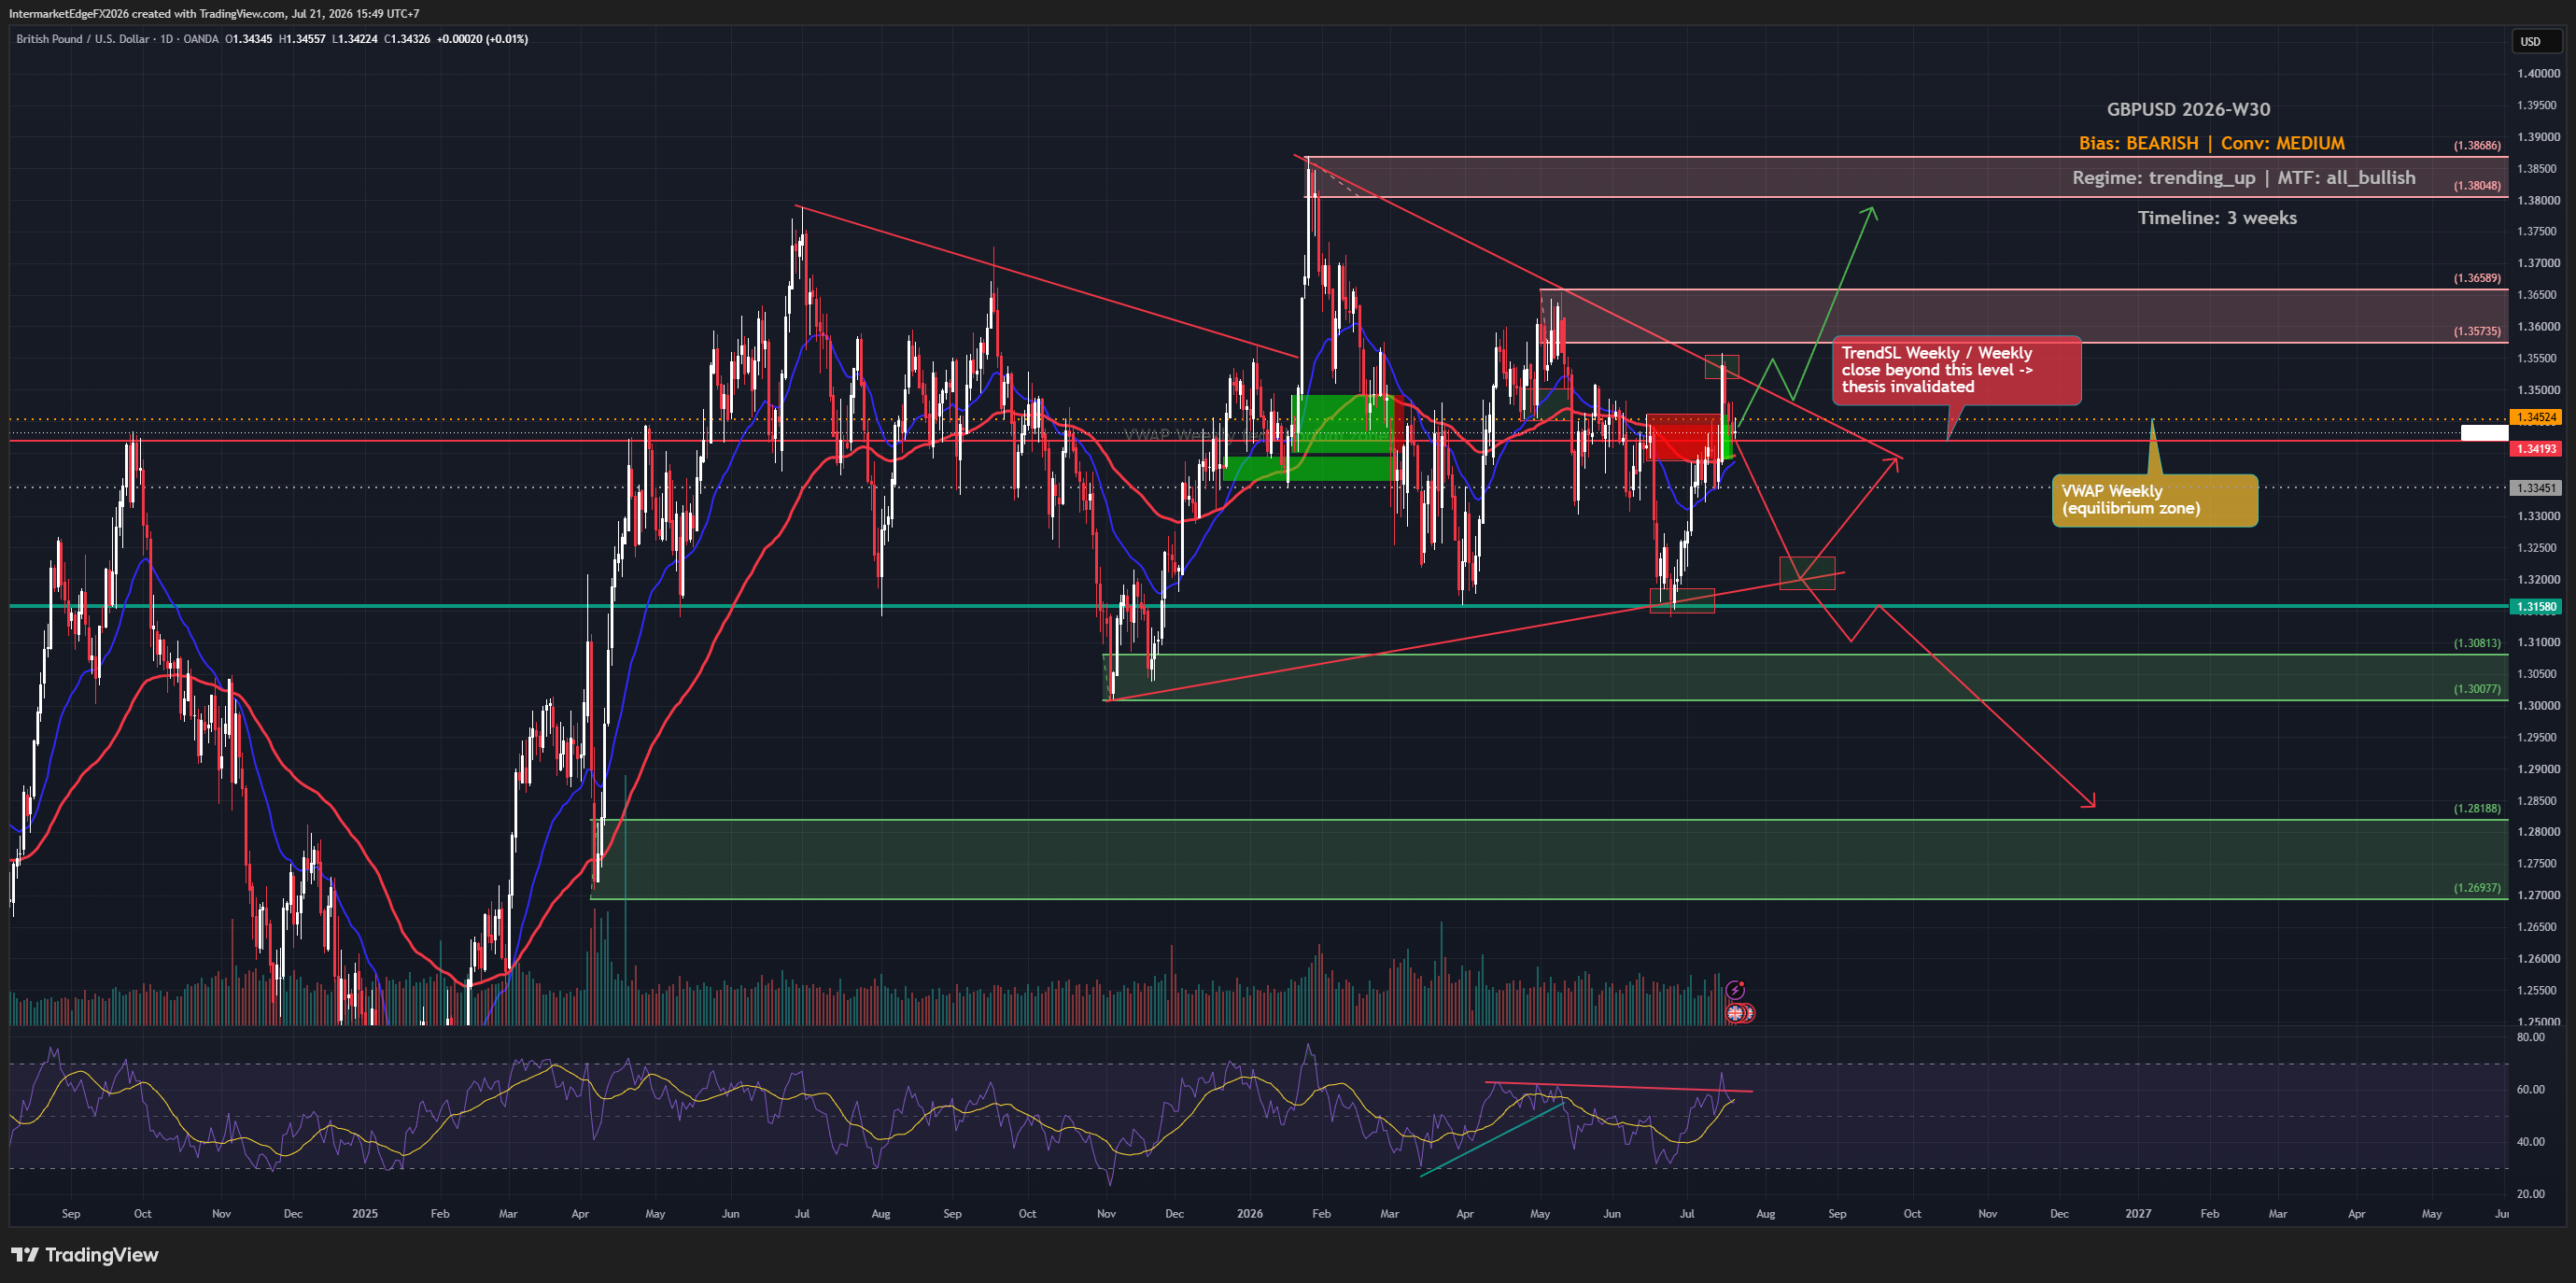
GBPUSD Week W30-2026: Burnham Takes Power and Core CPI Prints Zero, But Price Holds at VWAP 1.3452 as Bull Technicals Clash With a Bearish Macro Case

GBPUSD Week W30-2026: Burnham Takes Power and Core CPI Prints Zero, But Price Holds at VWAP 1.3452 as Bull Technicals Clash With a Bearish Macro Case

Sterling is caught in a genuine tug-of-war this week. Andy Burnham's move into Downing Street triggered volatile, mixed reactions in GBP — markets are questioning fiscal credibility under the new government, and the appointment of John Healey as Chancellor is reshaping spending expectations. Gilt yields rose and sterling dipped on those concerns, a classic political risk premium repricing. On the USD side, escalating US-Iran tensions and a spike in Brent crude are providing a competing safe-haven bid for the dollar, adding to the bearish GBPUSD case via the BOE vs Fed rate differential — US real yields at 2.35% remain a structural headwind for GBP. However, the core signal conflict here is real and cannot be papered over: price, COT positioning, and the technical structure (Daily, Weekly, Monthly all bullish) are aligned against the macro bearish thesis. Price is sitting exactly at VWAP weekly (1.3452) and above TrendSL weekly (1.3419) — both thesis-break levels are untested. A weekly close above 1.3419 formally invalidates bearish structure. The US Core CPI miss (actual 0.0 vs 0.2 forecast) also complicates the 'Fed stays hawkish' narrative and is a partial offset to USD strength. A TGA drain adds further USD headwind. Bottom line: macro and political forces lean bearish, but technical alignment and a crowded short setup (COT bullish at +0.80) create meaningful reversal risk. Conviction is medium. Size conservatively and watch weekly closes relative to 1.3419 and 1.3452 before committing directionally. -- Intermarket Edge

Stay in the loop

Get notified about new research, macro insights, and market analysis.

InterMarketEdge

© 2026 InterMarketEdge. Financial intelligence for inter-market traders.