Intermarket Analysis — InterMarketEdge

Intermarket Analysis

Cross-asset correlation studies — how oil, yields, equities, and FX interact and what divergences signal

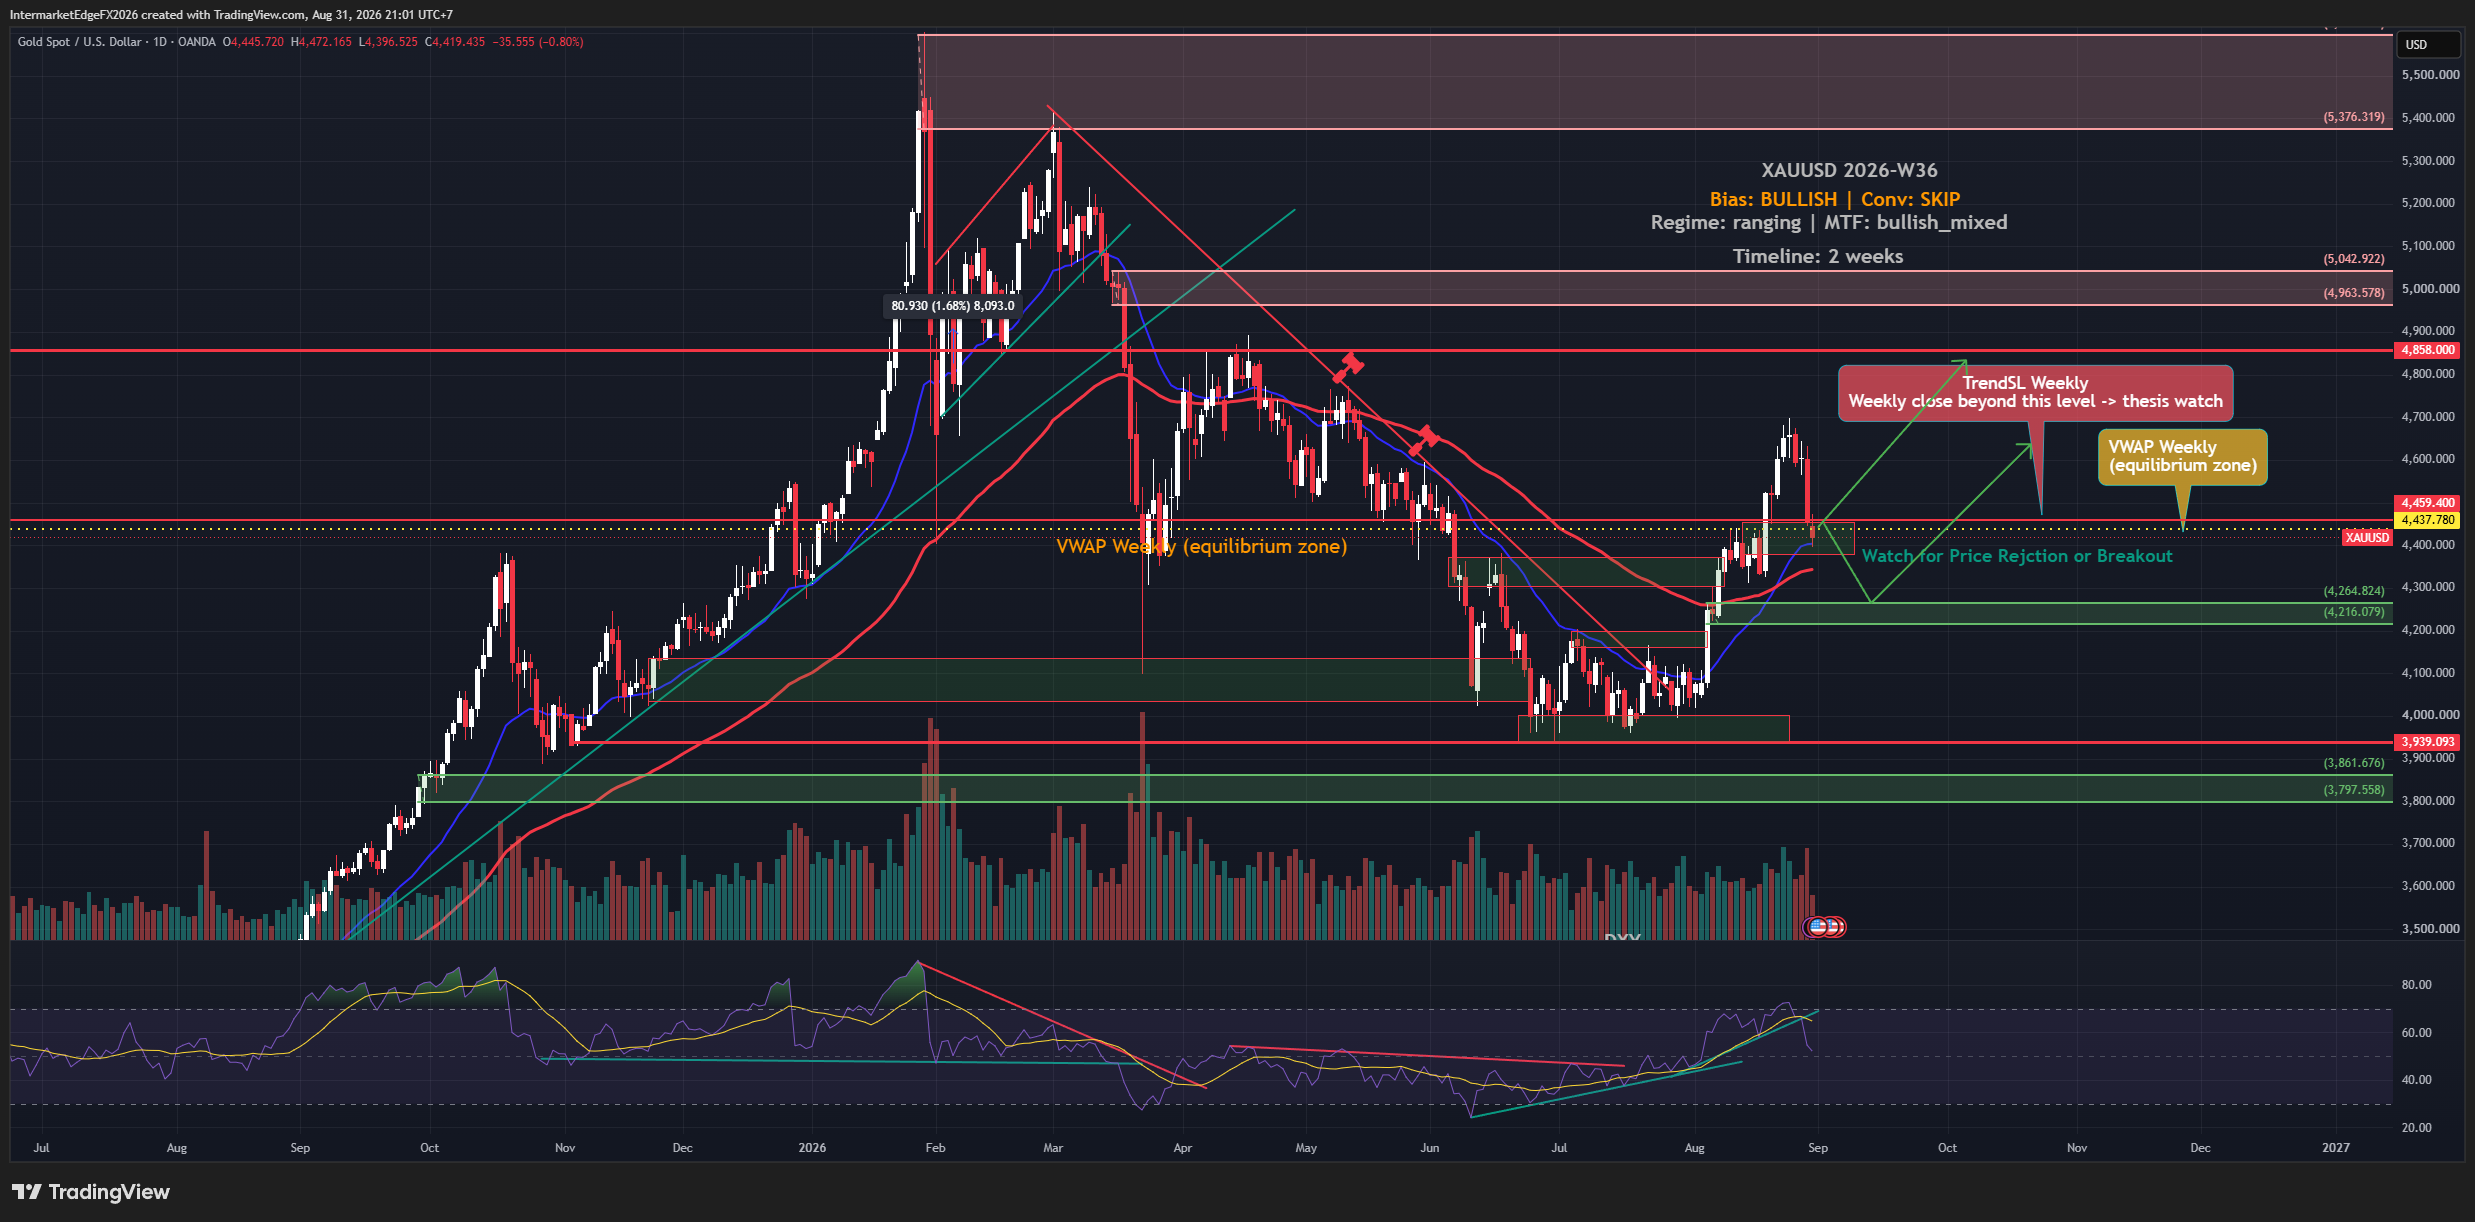
XAUUSD Weekly Outlook: Hawkish Shock, Unconfirmed Bull Case

XAUUSD Weekly Outlook: Hawkish Shock, Unconfirmed Bull Case

Gold fell more than 3% in a single session after Fed Chair Kevin Warsh signaled further rate hikes if inflation does not clearly return toward 2%, lifting September hike probability from roughly 36% to around 62%. Yet despite that sharp Friday selloff, spot gold near 4,448 dollars remained on course for its strongest monthly gain since January. That contradiction, brutal single-session damage inside a bullish monthly trend, is exactly the kind of setup where traders read the direction right and still get hurt. The framework labels XAUUSD bullish for the two-week window, but deliberately attaches a stand-aside posture to that label, meaning the evidence is not convincing enough to size a position, and that is a considered analytical conclusion rather than an absence of a view. Understanding why that gap exists between the directional label and the action status is the practical takeaway. Price signals, the inputs the analysis weighs most heavily for direction, lean bullish. But the COT data through August 25 showed managed money net long 144,747 COMEX gold contracts, up 3,099 from the prior week. It is worth noting that this COT reading predates Friday's sharp selloff, so the actual positioning picture after that session is unknown and must be treated as lagged. Even before accounting for that lag, the level itself is a crowding risk: when speculative longs are already concentrated at an extreme, the question becomes who is left to push price higher, and the answer often determines whether a bullish thesis accelerates or reverses violently on any negative catalyst. That COT reading conflicts directly with the bullish price signals, and the framework flags this openly rather than resolving the conflict artificially. -- Intermarket Edge (Note: COT (Commitment of Traders) data is released weekly by the CFTC with a reporting-period lag -- it is not a real-time position feed. See cftc.gov for the exact release schedule.)
USDCAD: Bullish Macro Label Meets a Bearish Price Structure

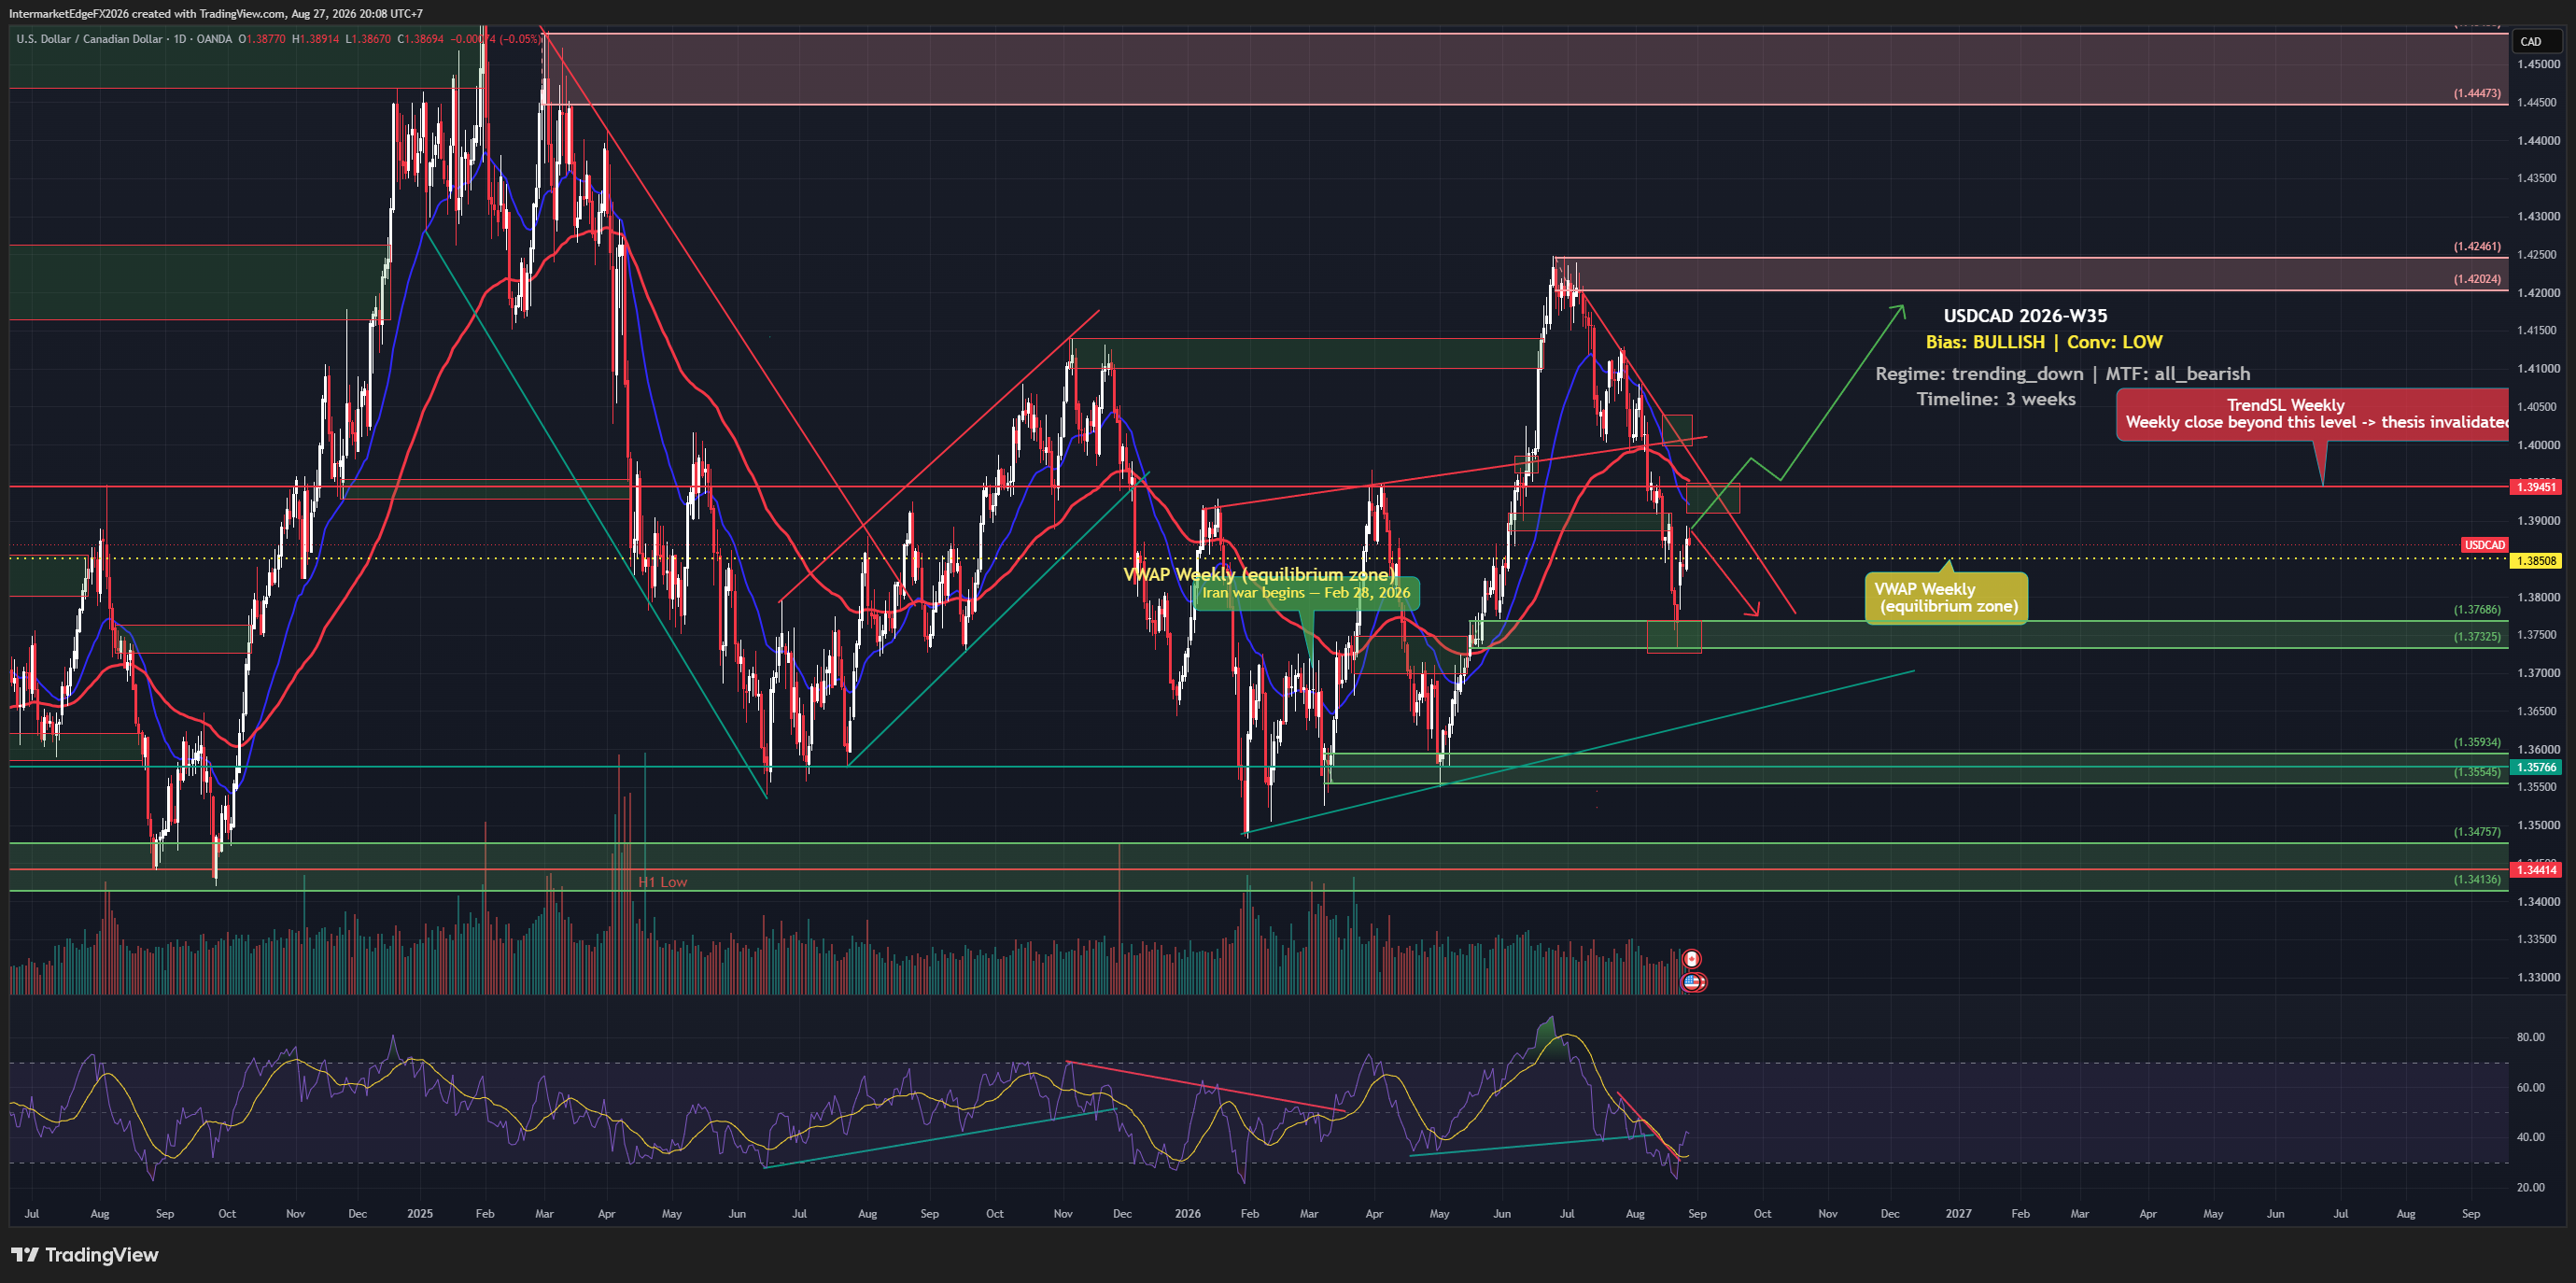
USDCAD: Bullish Macro Label Meets a Bearish Price Structure

USDCAD is carrying a bullish bias into the final stretch of August 2026, but the pair is trading nearly 63 pips below the weekly TrendSL of 1.39451 as of Thursday, 27 August, meaning the technical structure does not yet support the label it has been given. The Canadian dollar hit a one-week low as a revived trade dispute rekindled economic worries, yet retaliatory tariffs from Canada quickly clawed some of that move back. That push-pull dynamic is precisely the kind of environment where calling a direction early is far easier than timing it correctly. The bullish thesis on USDCAD rests on a causal chain that begins at the Fed: sustained hawkishness has pushed US real yields to 2.32%, which supports dollar demand globally and feeds directly into USDCAD through the rate differential with the Bank of Canada. COT positioning data adds a secondary layer of confirmation, with commercial and speculative data skewing toward USD strength, though the brief does not specify the report week, net-position figure, or sample window, so this should be read as directional corroboration rather than a standalone signal. Macro and positioning therefore rhyme. What they do not resolve is the technical picture. This is where the thesis becomes genuinely complicated. At the time of writing, price at 1.38829 is already below the TrendSL weekly of 1.39451, and that condition was true from the moment the thesis was generated, not something that developed afterward. A bullish bias with price testing from underneath a declining trend stop-loss line is a structural contradiction: the same framework that produces the bullish label is simultaneously flagging that the technical evidence does not support it yet. The conviction level is accordingly low, and that is not a minor disclaimer, it is the honest read of a setup where macro and price structure are pointing in opposite directions. -- Intermarket Edge

EURGBP Week W35-2026: Sterling Pauses Its Four-Week Rally, but the Bullish Case Sits Below Every Key Level

EURGBP Week W35-2026: Sterling Pauses Its Four-Week Rally, but the Bullish Case Sits Below Every Key Level

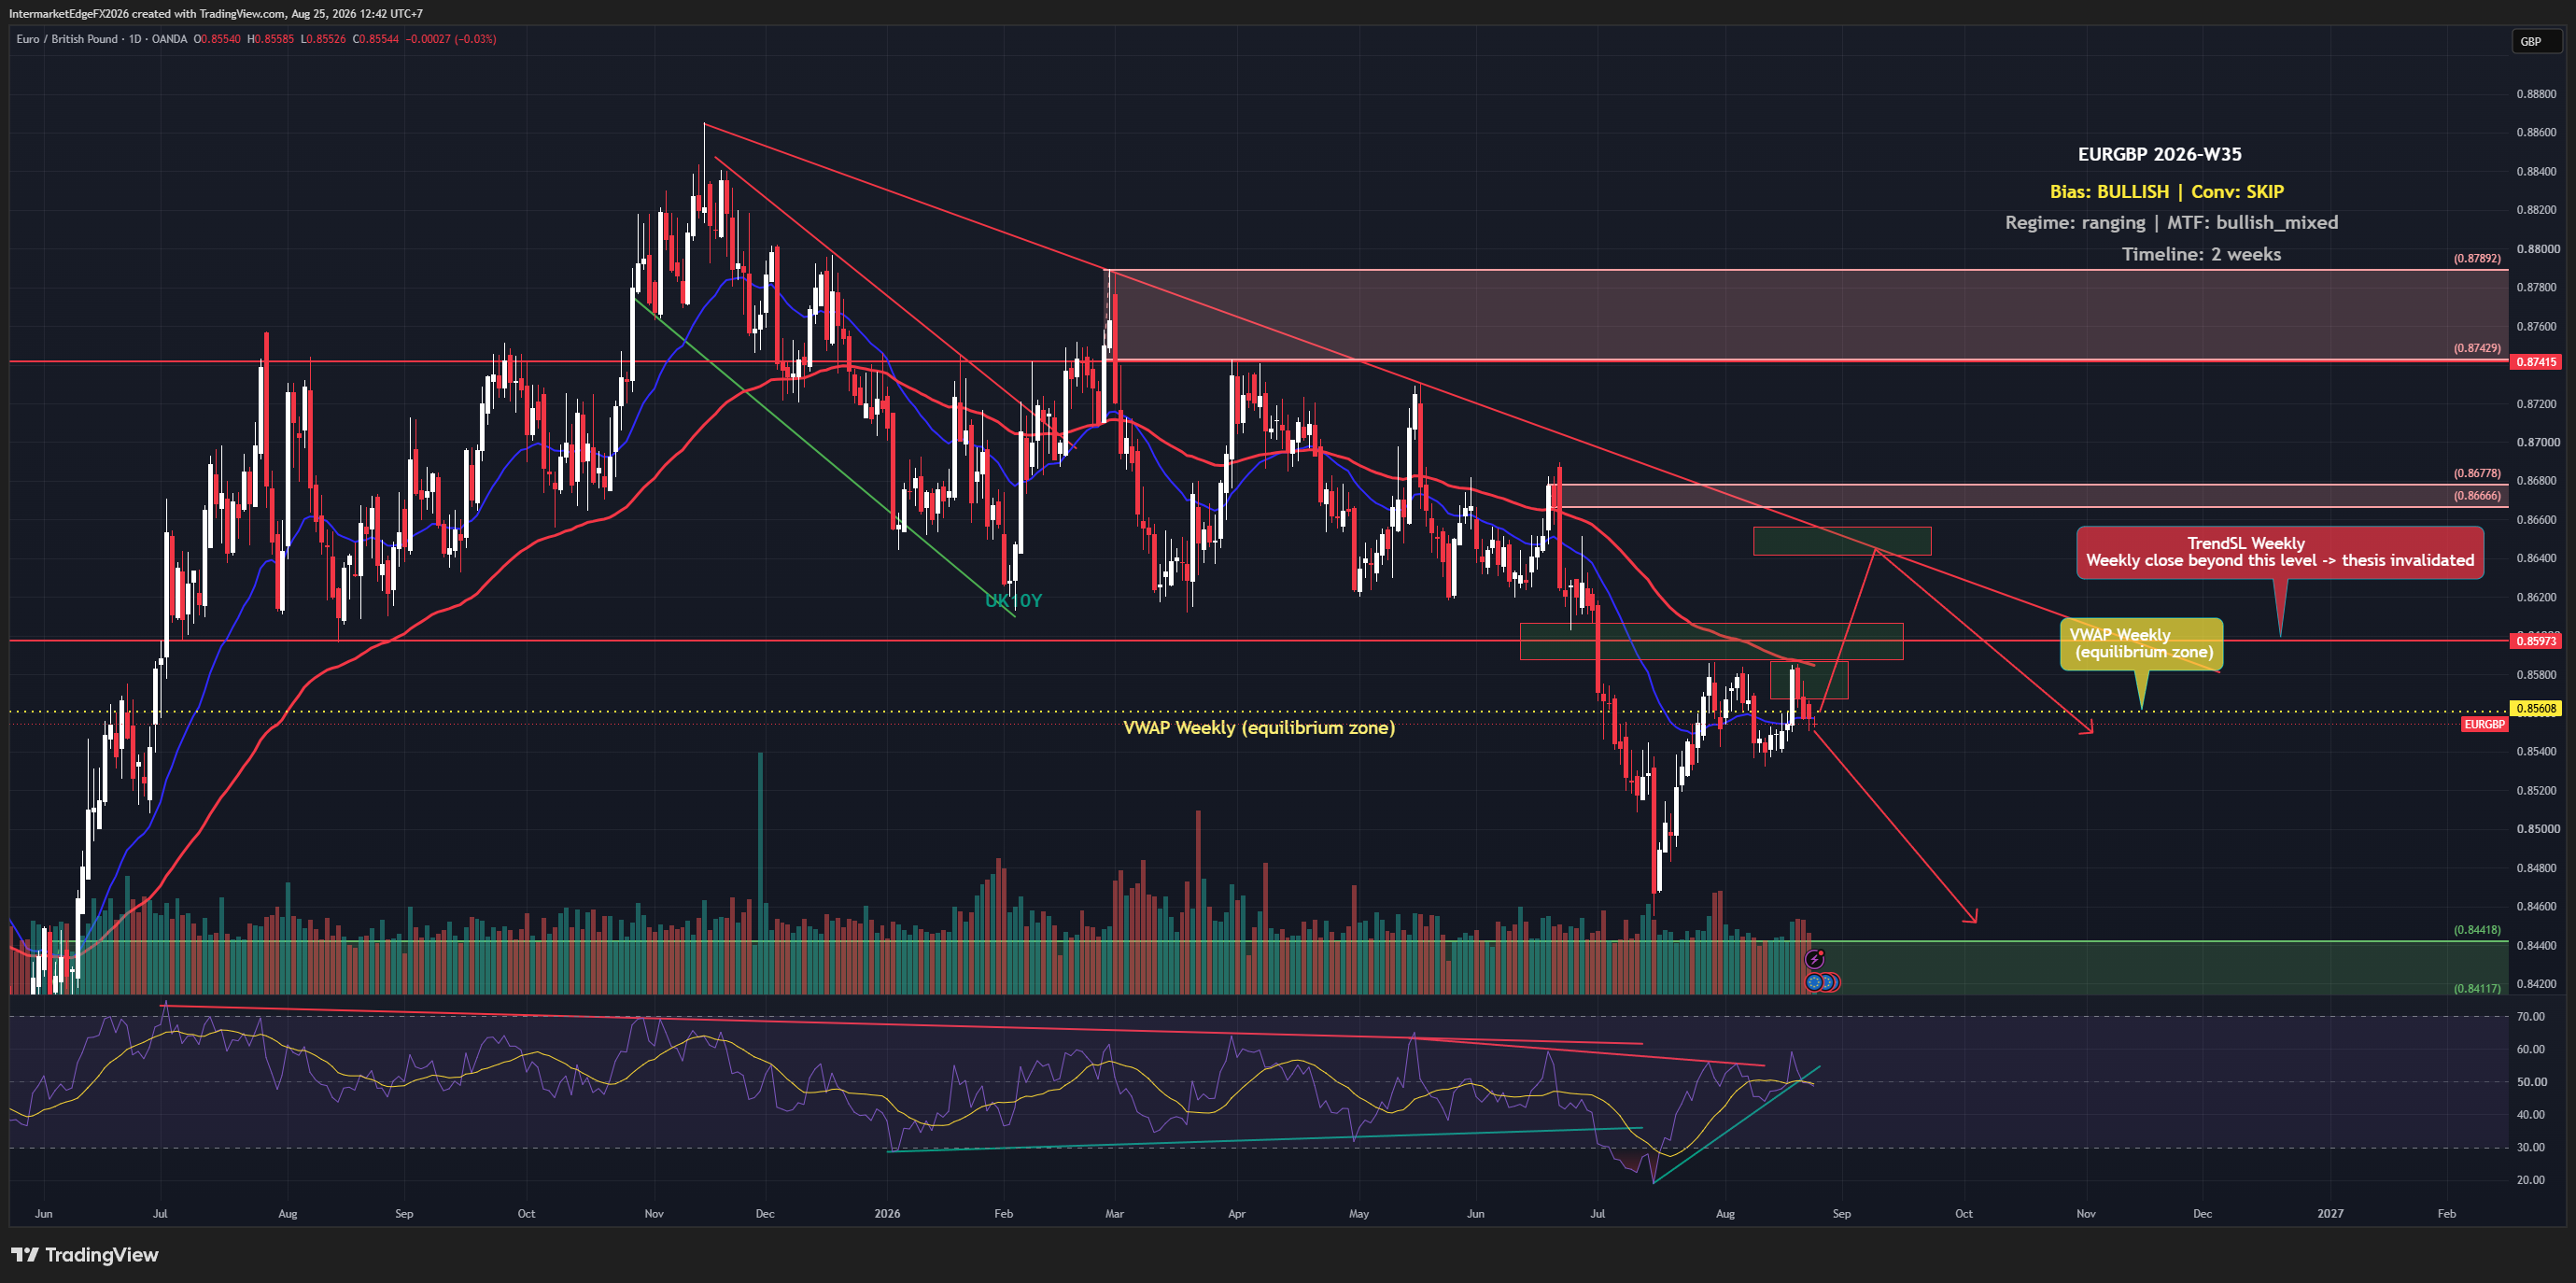
EURGBP is sitting below its weekly VWAP of 0.85608 as of Tuesday, 25 August 2026, and the technical structure already contradicts the tentative bullish lean this week carries. Sterling just paused a four-week rally as investors repositioned around US sanctions on Iran, while the ECB is signaling caution on rates even as the eurozone shows unexpected resilience. The pair is caught between two central banks pulling in different directions, and right now, neither side has won. The framework labels EURGBP bullish for the two-week horizon beginning W35-2026, but the honest description of that label is that it rests on a single thin pillar: price action alone. Every other input, positioning data, macro signals, liquidity conditions, sentiment, is neutral and contributing nothing to the directional call. That kind of setup, where one source carries the entire argument, is precisely where conviction becomes a problem, and this analysis treats it as such. The decision here is deliberately to stand aside rather than size a position, because the evidence is not yet convincing enough to justify the directional risk. The stated primary driver is the ECB versus Bank of England rate differential, the practical meaning of which is that when the ECB is expected to hold or cut while the BOE is expected to hike, Sterling strengthens relative to the euro, pushing EURGBP down, and vice versa. But here is the disconnect that matters: no rate-specific or macro-specific signals have actually fired in support of the bullish label. The driver is named but not confirmed by the inputs. Compounding that, the structural or longer-term bias is neutral, which conflicts with the short-term bullish lean. -- Intermarket Edge

XAUUSD Week W35-2026: Gold Hits a Three-Month High as Fiscal Fears Collide With a Real Yield Warning

XAUUSD Week W35-2026: Gold Hits a Three-Month High as Fiscal Fears Collide With a Real Yield Warning

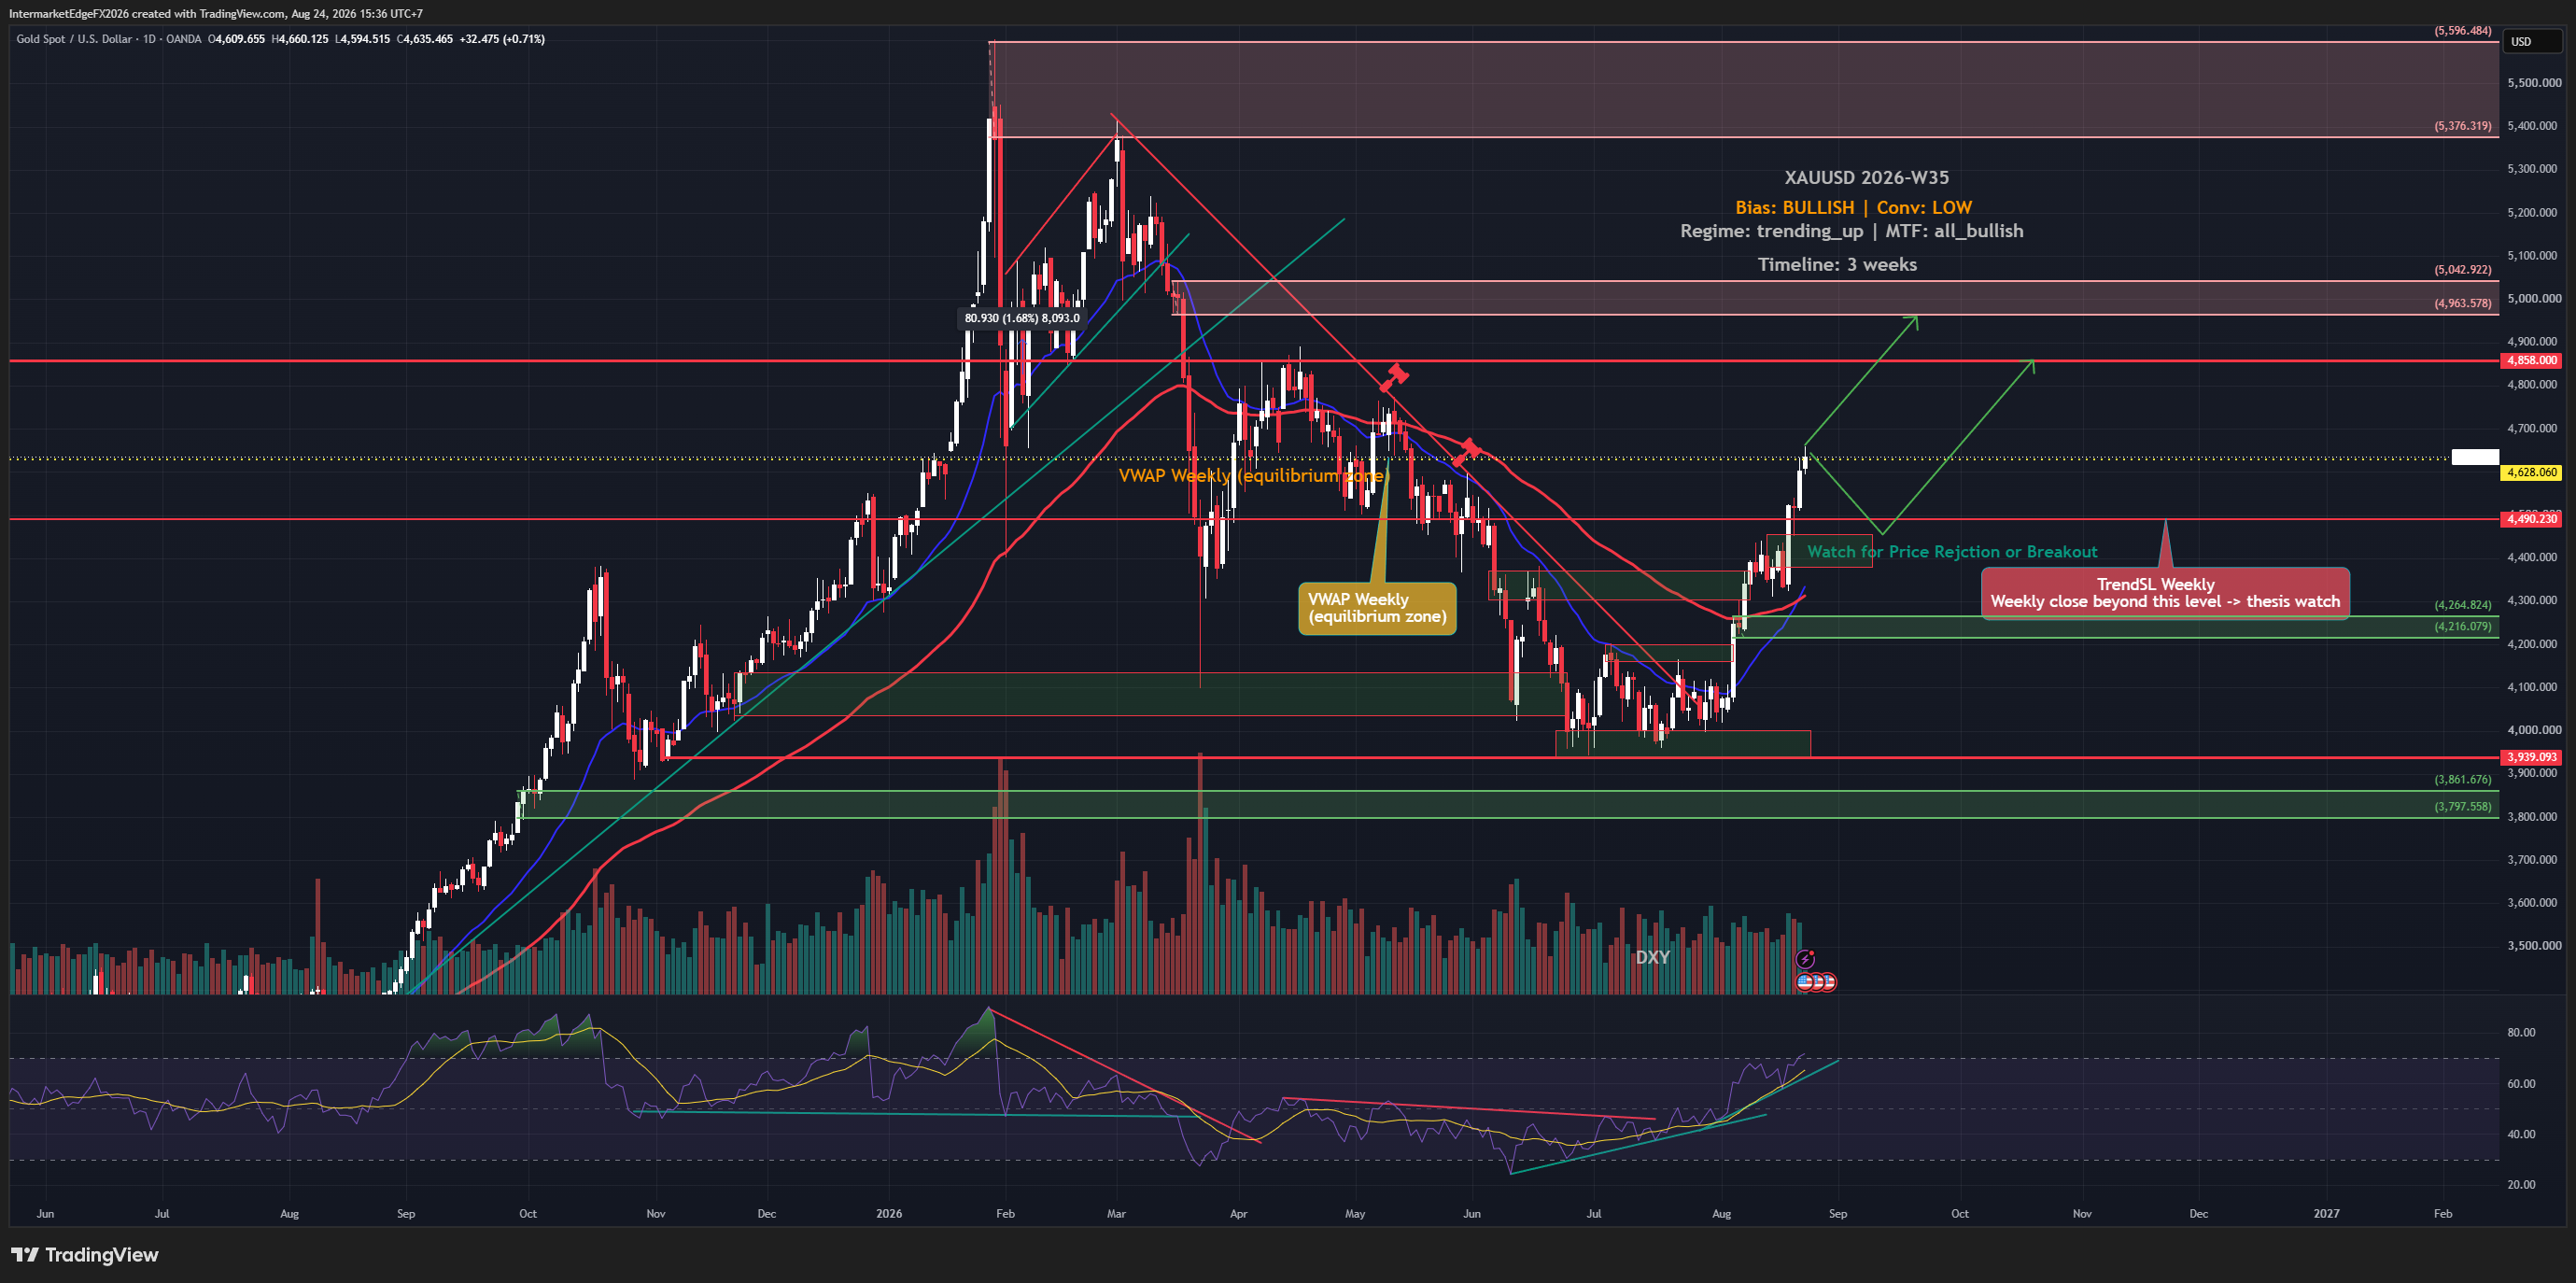
Gold traded at 4641.1 on Monday, 24 August 2026, reaching levels not seen in over three months ahead of a week packed with US inflation and labor data. The move is real, daily, weekly, and monthly structure all point the same direction. But the macro headwind is equally real: a US 10-year real yield of 2.35% is the kind of opportunity cost that historically slows gold rallies. Knowing which force wins this week is the actual question. The bullish bias on gold this week rests on two pillars: price structure and derivatives-market positioning, specifically the COT signal. Every major timeframe, daily, weekly, monthly, has its trend stop-loss pointing in the same direction, which is the highest form of technical agreement the framework registers. That kind of multi-timeframe alignment (MTF all_bullish) means trend-following systems and discretionary traders anchored to weekly and monthly structure are pulling in the same direction, reducing the probability of sharp mean-reversion moves against the trend. The COT signal adds a second, independent layer. When the positioning pattern currently active has fired historically, over 41 observed weeks, the bullish outcome was correct roughly 70.7% of the time, with average conviction rising substantially across those instances. That figure should be read as a directional probability, not a guarantee; the sample size is moderate and the methodology details are not fully disclosed in what is available here, so treat it as supporting evidence, not standalone proof. What keeps conviction at the low end despite these positives is the absence of any sentiment or liquidity confirmation. The bullish case is built entirely on price structure and COT; neither sentiment flow nor liquidity conditions are contributing. -- Intermarket Edge

EURJPY Week W34-2026: Trend Holds Above 184.86, But a BOJ Carry-Unwind Warning Keeps Buyers Cautious

EURJPY Week W34-2026: Trend Holds Above 184.86, But a BOJ Carry-Unwind Warning Keeps Buyers Cautious

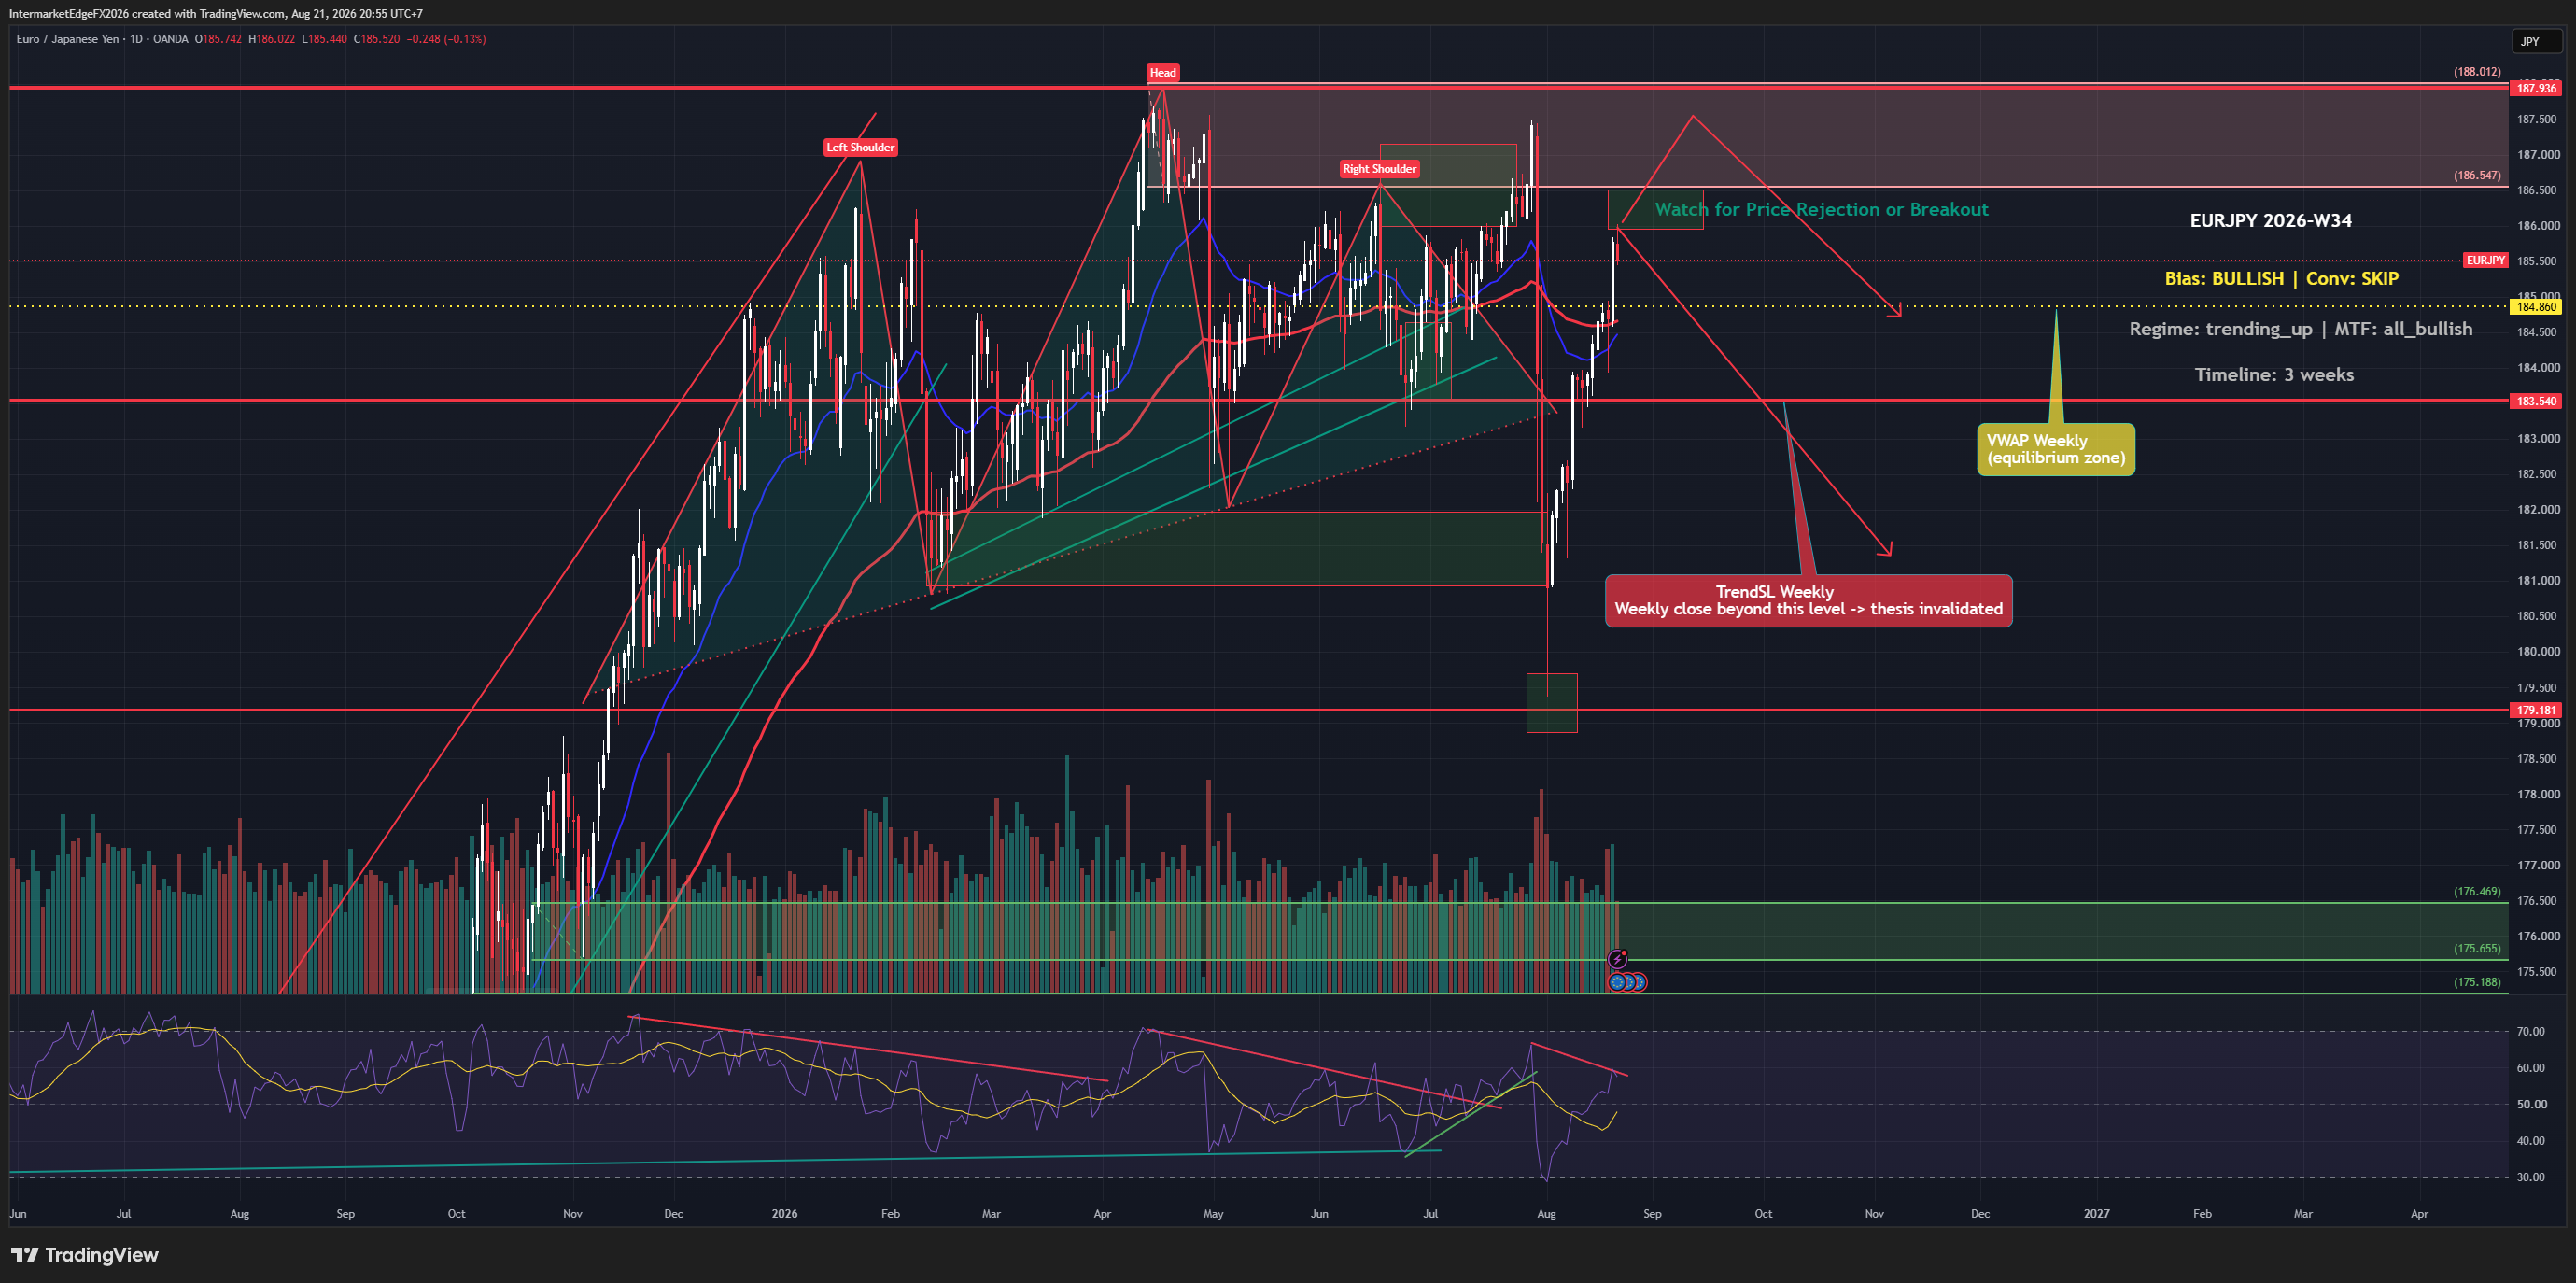
EURJPY is trading at 185.65 as of Friday, 21 August 2026, above its weekly VWAP at 184.86, with daily, weekly, and monthly trend all pointing the same direction. That alignment sounds clean, but Japan's 52nd consecutive Core-Core CPI increase is keeping BOJ rate-hike expectations alive, and a carry unwind triggered by BOJ policy tightening could erase a technically sound bullish setup faster than most traders anticipate. The structure is bullish. The macro is not cooperating. The structural bias for EURJPY through the next three weeks is bullish, and that verdict rests entirely on price action: daily, weekly, and monthly trend are all aligned upward simultaneously, which is the highest-conviction technical signal this framework can register. When all three timeframes agree, trend-following logic argues for giving the move room to continue rather than fighting it. The current market price of 185.65, recorded on Friday, 21 August 2026, sits above both the weekly VWAP of 184.86 and the weekly trend stop-loss at 183.54, meaning the price structure has not yet given a technical reason to abandon the bullish read. The honest complication is that price action is operating in isolation here. COT positioning, liquidity signals, and sentiment data are all neutral, no confirming flows are reinforcing what the charts suggest. That leaves the bull case technically sound but fundamentally thin. More significantly, macro signals are leaning bearish, driven by BOJ hawkishness carry-unwind risk carrying a meaningful weight in the overall picture. A carry unwind, where yen funding costs rise enough to force traders out of long EURJPY positions regardless of chart structure, does not care about multi-timeframe alignment; it can override technical setups quickly and with little warning. The result is a bullish directional bias that the framework cannot yet support with enough confirming evidence to justify sizing a position. -- Intermarket Edge (Note: COT (Commitment of Traders) data

XAUUSD Week W34-2026: Fed-Hike Bets Collapse and Gold Climbs, But the Structural Ceiling at 4438 Remains Unbroken

XAUUSD Week W34-2026: Fed-Hike Bets Collapse and Gold Climbs, But the Structural Ceiling at 4438 Remains Unbroken

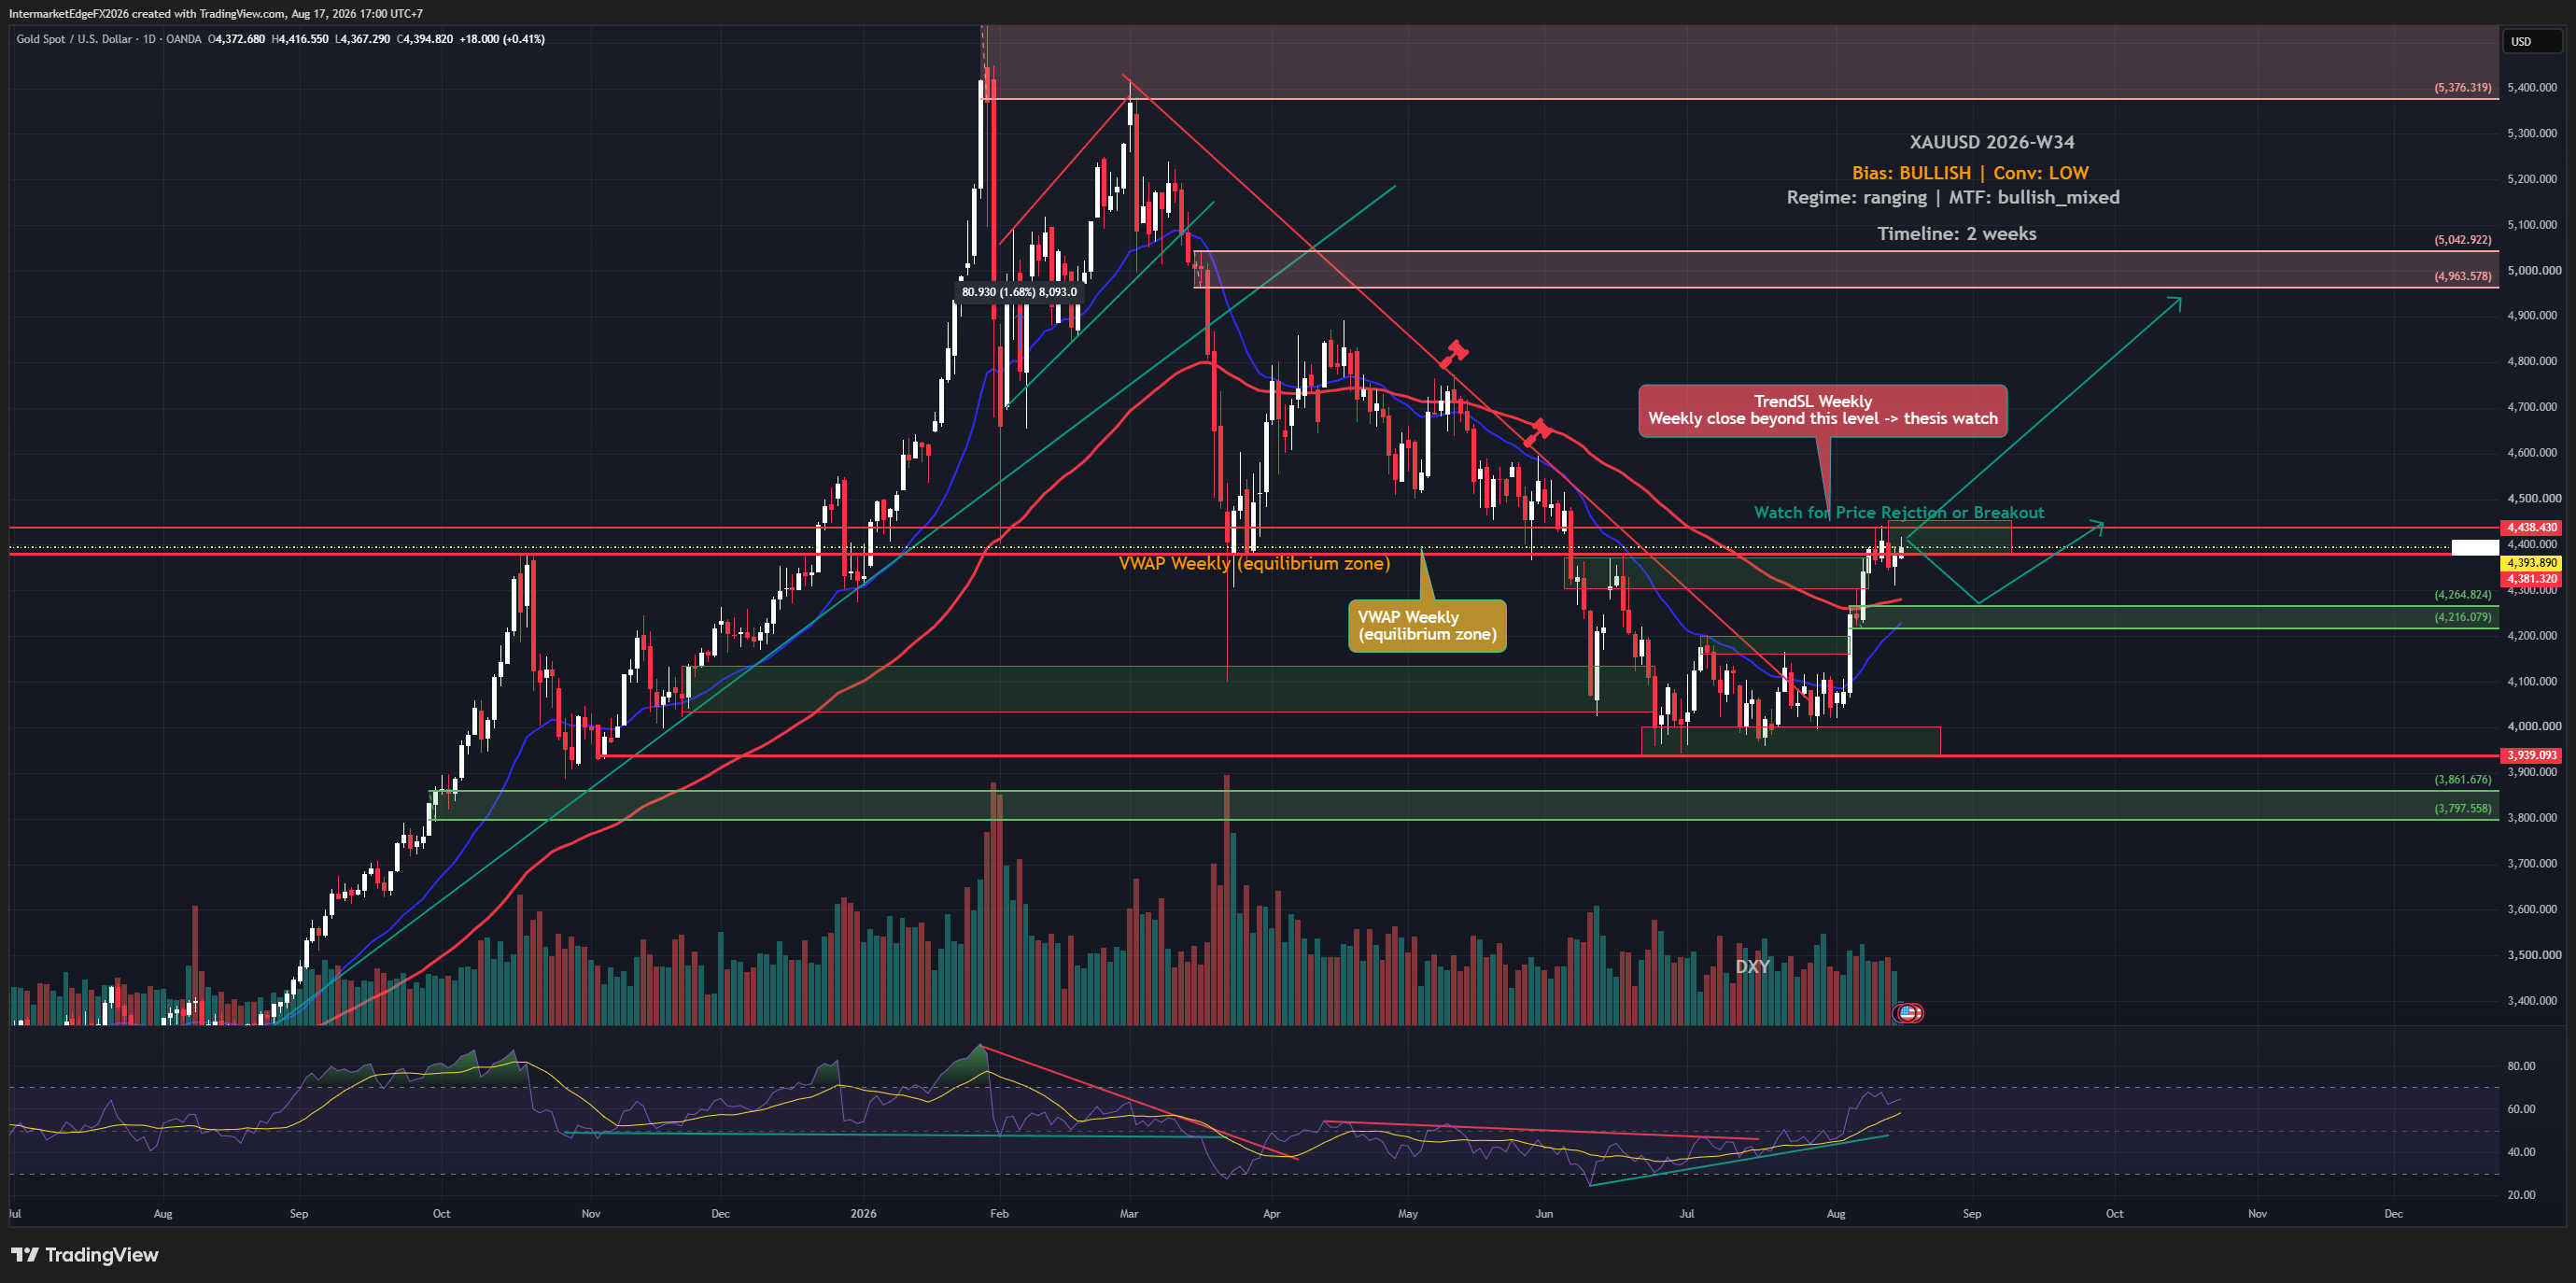
Gold is climbing toward $4,400 as Fed rate-hike bets collapse and the dollar softens, yet the bullish structure is not yet confirmed. Price on Monday, 17 August 2026 sits at 4394.5, marginally above the weekly VWAP but still well below the key trend structure level at 4438.43. The driver that was supposed to cap gold, Fed hawkishness, has been largely invalidated by the market itself, flipping the conventional bearish narrative on its head. The framework's bias for XAUUSD this week is bullish, but that label requires immediate qualification: conviction is low, and the structural picture at the time of thesis generation actually argues against the bullish call rather than supporting it. The reference close price of 4397.83 was already sitting below the weekly trend structure level at 4438.43 when the thesis was set, which means the bullish label is a directional lean, driven primarily by price action and COT positioning, not a technically confirmed trend. That distinction matters because it changes how much weight any given piece of confirming evidence should carry. The two active pillars supporting the bullish case are price behavior and COT positioning. On the COT side, commercial and speculative positioning in Comex gold futures and options as of the August 14 report leans bullish, but the specific net-position figure and the precise breakdown between commercial hedgers and large speculators are not available here, so this should be read as directional evidence, not a citable standalone number. On price, the multi-timeframe alignment is described as bullish-mixed: some shorter timeframes confirm the directional lean, others do not. Cutting across both pillars is a live Fed-hawkish causal chain that argues the opposite direction, rising real yields reducing gold's appeal, and these forces are partially offsetting each other right now. -- Intermarket Edge (Note: COT (Commitment of Traders) data is released weekly by the CFTC with a reporting-period lag -- it is no

USOIL Week W33-2026: Inventory Builds and Hormuz Uncertainty Leave Oil Caught Between 81.12 and 85.31

USOIL Week W33-2026: Inventory Builds and Hormuz Uncertainty Leave Oil Caught Between 81.12 and 85.31

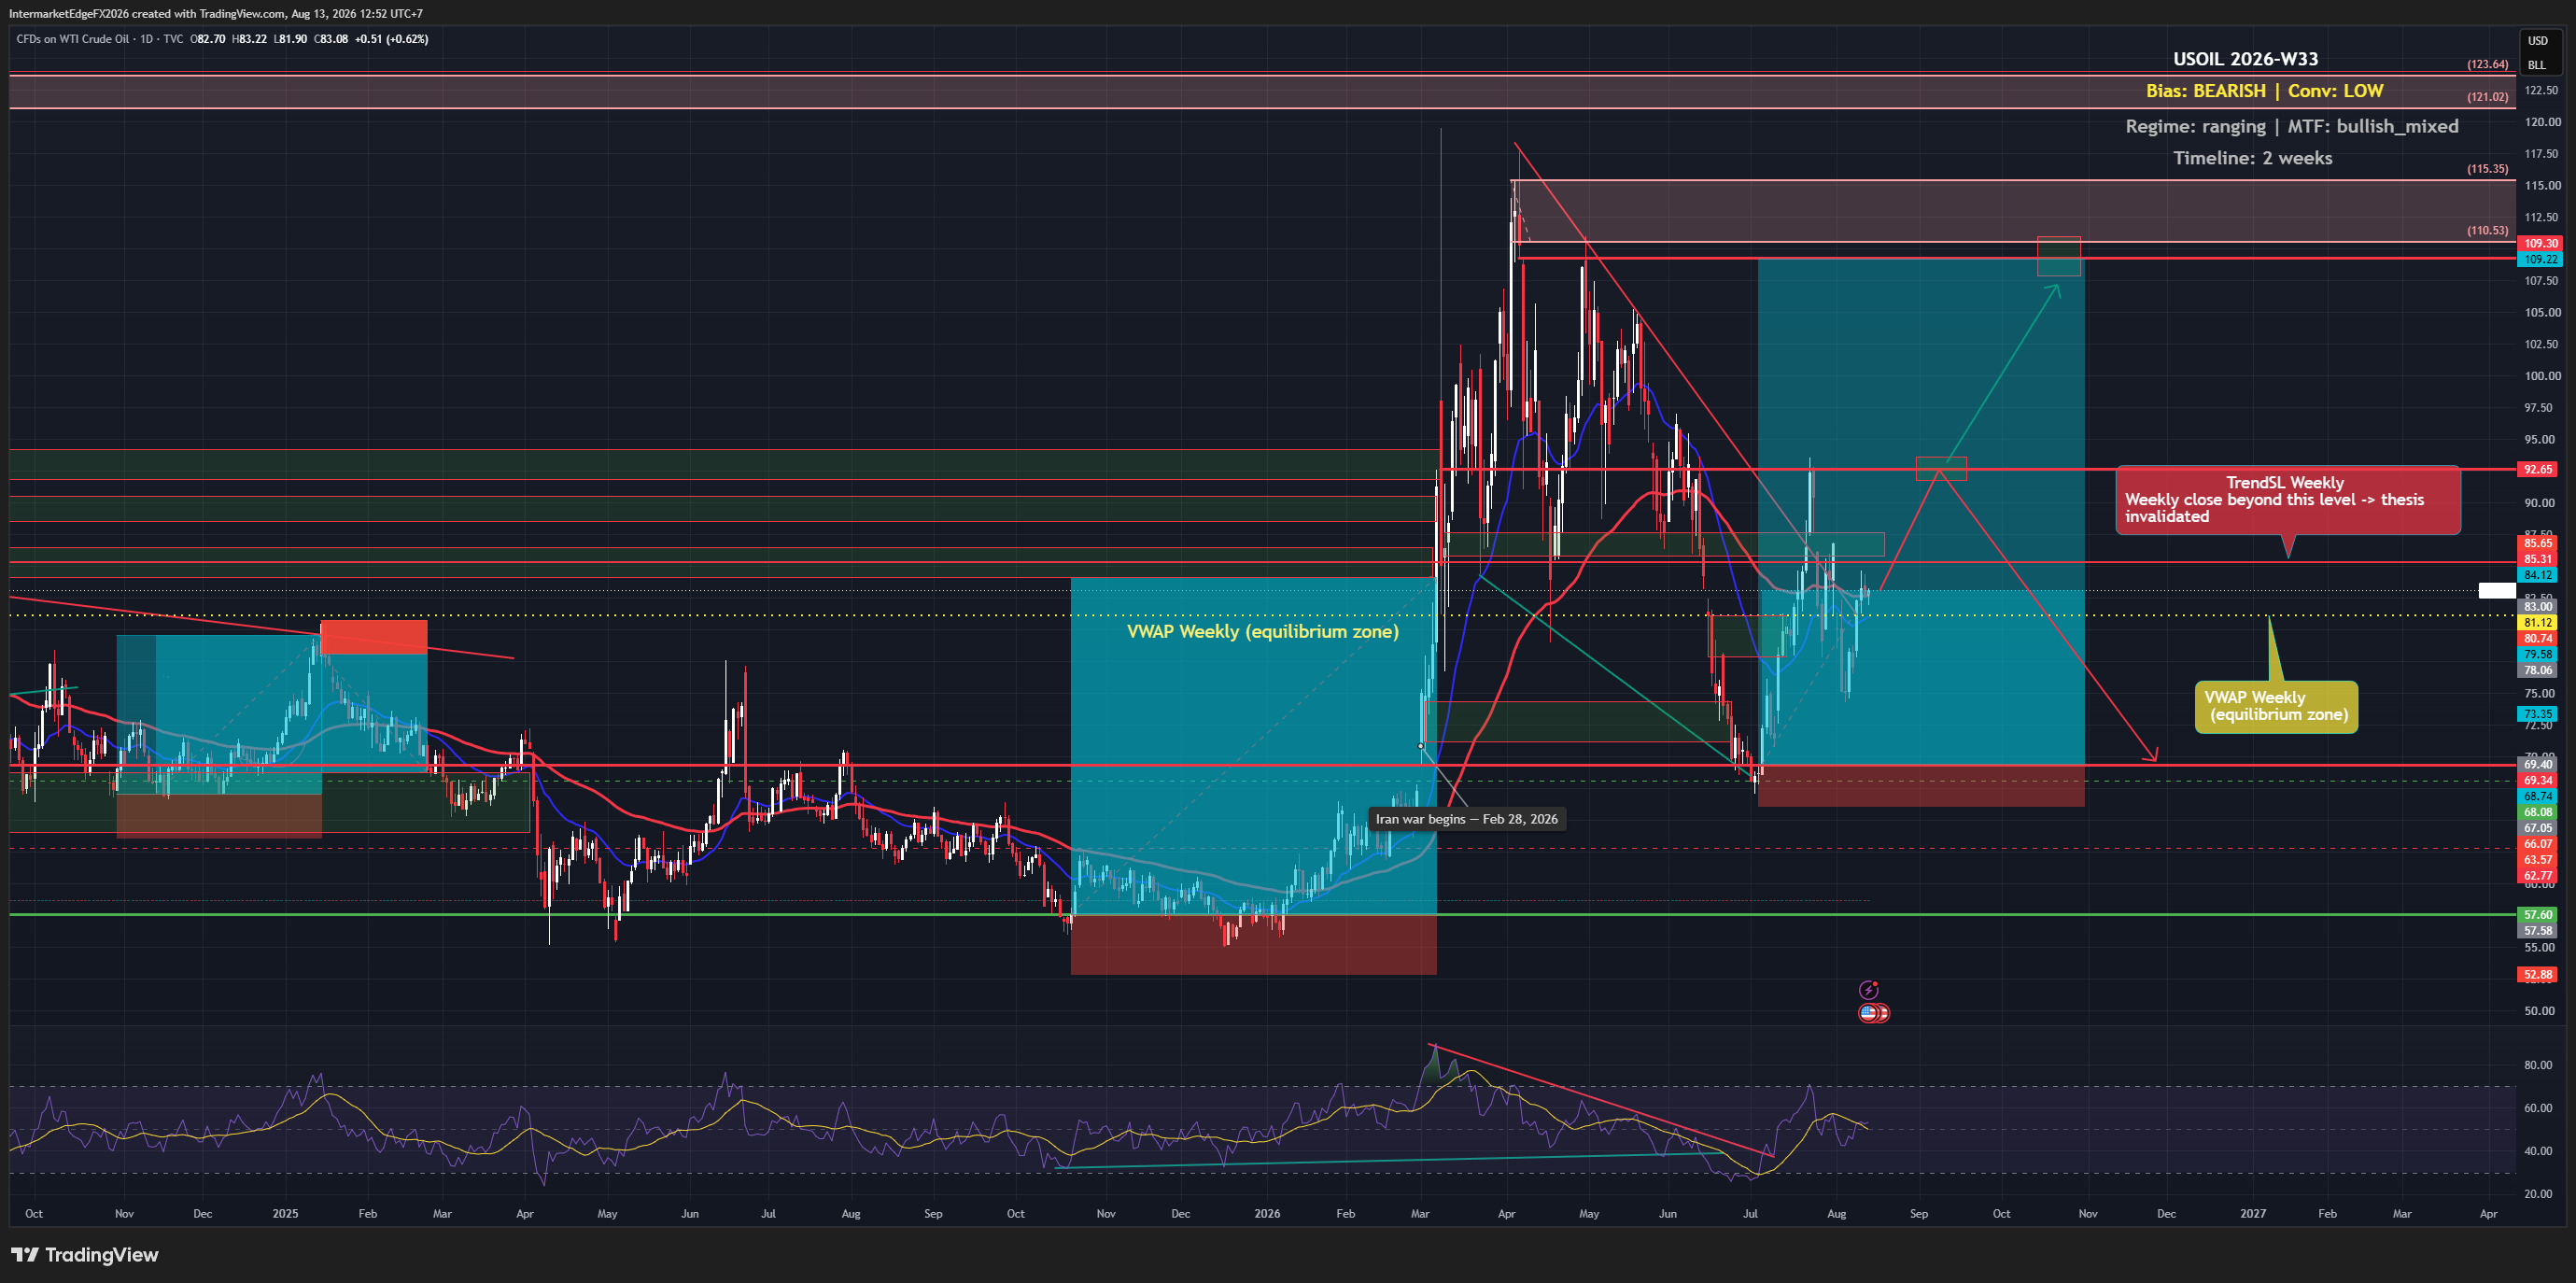
USOIL is trading at 82.90 on the CL=F futures contract used as proxy, caught between a four-week streak of crude inventory builds averaging above 1.5 million barrels and a COT positioning read that still leans bullish. The macro story, rising real yields, a stronger dollar impulse, and China's structural shift away from gasoline, points lower. But price has not broken down yet, and that gap between the fundamental case and actual price behavior is exactly where traders get into trouble this week. The framework's output for W33-2026 is a bearish bias on USOIL, but the conviction is deliberately low, and that low conviction is not a soft bearish call, it is a signal that the evidence is conflicted enough to warrant real caution before sizing any directional position. Here is why the conflict matters: price, COT positioning, and the technical read all carry bullish signals in isolation. COT data shows a bullish lean among non-commercial participants, though the brief does not specify the exact report week, net-position figure, or sample, so this should be read as directional evidence rather than a precise citable statistic. Price itself is above the weekly VWAP at 82.90, meaning short-term momentum has not rolled over yet. And the multi-timeframe alignment reads as bullish-mixed, not cleanly bearish. What flips the framework's output to bearish despite all that is the macro overlay: the combination of a rising real yield environment creating dollar-bullish pressure, four consecutive weeks of crude inventory accumulation averaging above 1.5 million barrels per the EIA's actual reported figures, and the structural demand erosion from China's accelerating EV adoption together form a weight that the bullish positioning signals have not yet been able to lift price through. -- Intermarket Edge

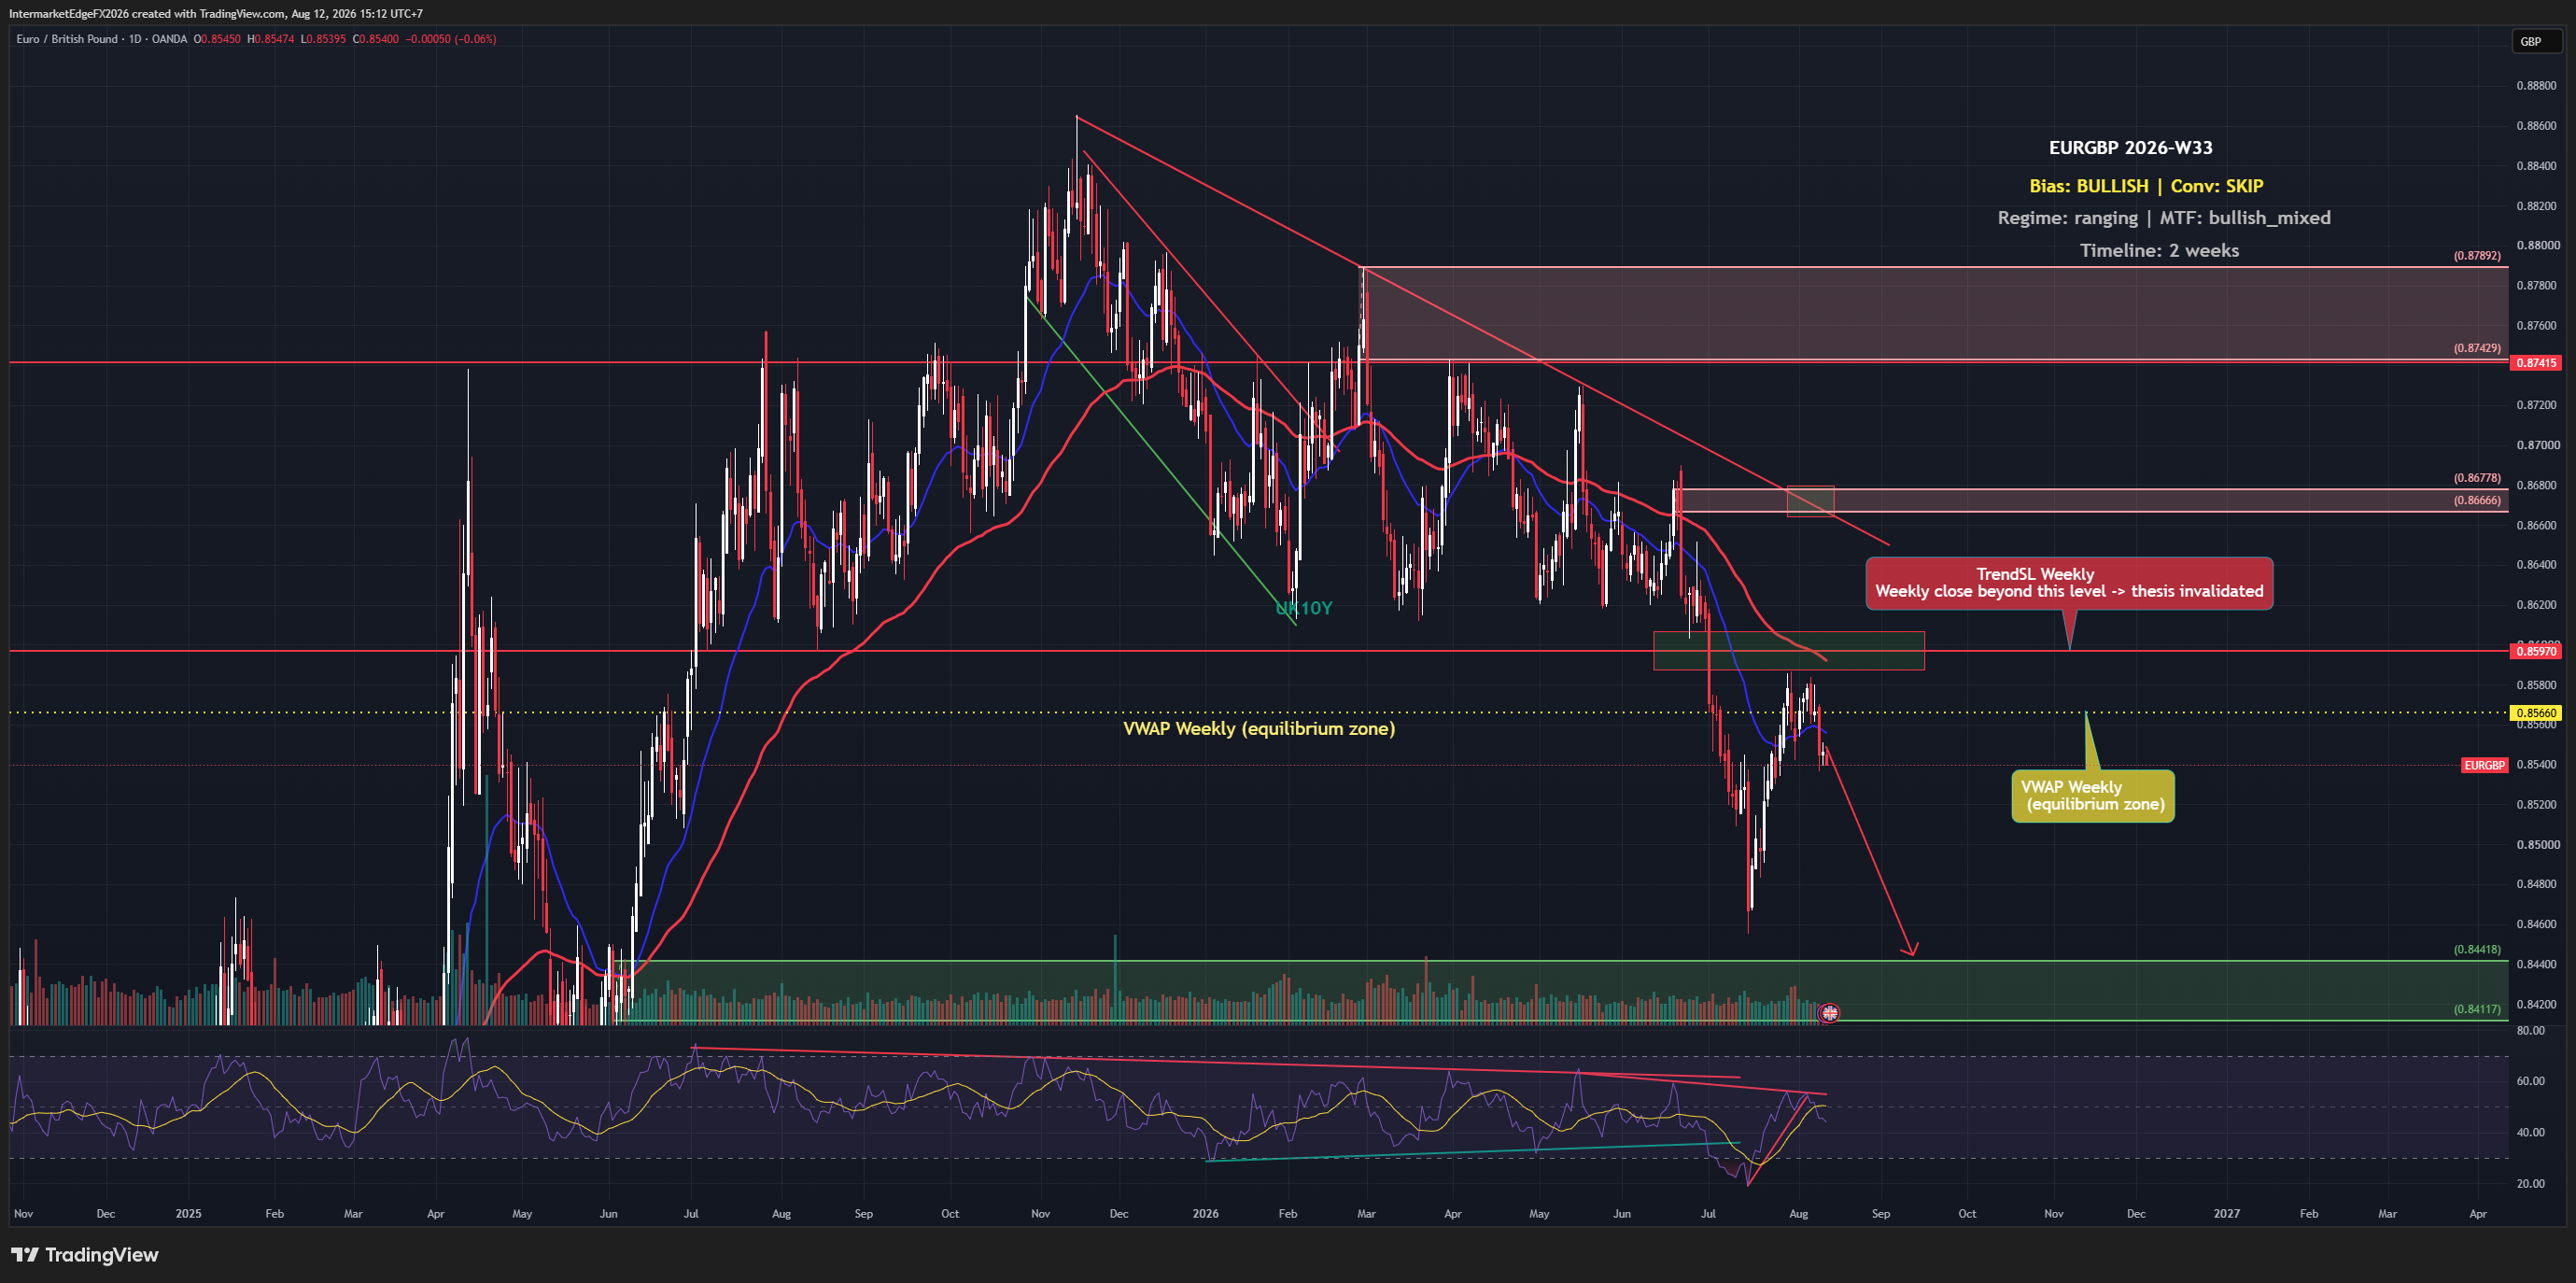
EURGBP Week W33-2026: BOE Holds at 3.75% But Sterling Fights Back, Leaving Bulls Stranded Below 0.8566

EURGBP Week W33-2026: BOE Holds at 3.75% But Sterling Fights Back, Leaving Bulls Stranded Below 0.8566

EURGBP is technically labelled bullish this week, yet as of Wednesday 12 August 2026, price at 0.85407 is sitting below the weekly VWAP at 0.8566, testing from underneath rather than pushing through it. That gap between the label and the price reality is exactly the kind of setup where traders get caught leaning on a bias that the market itself hasn't confirmed yet. With a BOE divided 6-3 on holding rates and a Euro-area CPI miss already in the books, neither side has a clean fundamental edge right now. The framework arrives at a weak bullish lean on EURGBP for this two-week window, but it is important to understand precisely how thin that lean is. The only active signal driving the bullish label comes from price action itself; positioning data, macro rules, liquidity signals, and sentiment indicators all contribute nothing, they fired no confirming evidence. A bias resting on a single source with no corroboration from other analytical layers is, by design, a low-confidence read that demands a correspondingly cautious posture. The analysis explicitly flags a structural conflict at the heart of the thesis: the overall directional label is bullish, but the structural bias is neutral, meaning the two core components of the framework are not pointing the same way. That internal contradiction is not a rounding error, it is a direct signal that the environment has not yet organised itself into a tradeable directional setup. The ECB-versus-BOE rate differential is cited as the primary fundamental narrative, the idea being that if ECB policy holds firmer relative to BOE policy, euro support should outpace sterling support over time. But no macro rule within the analysis has fired to validate that narrative in a quantifiable way this week, so it remains a story rather than a confirmed driver. What this means practically: the bullish label should be read as a directional lean, not a conviction call. -- Intermarket Edge

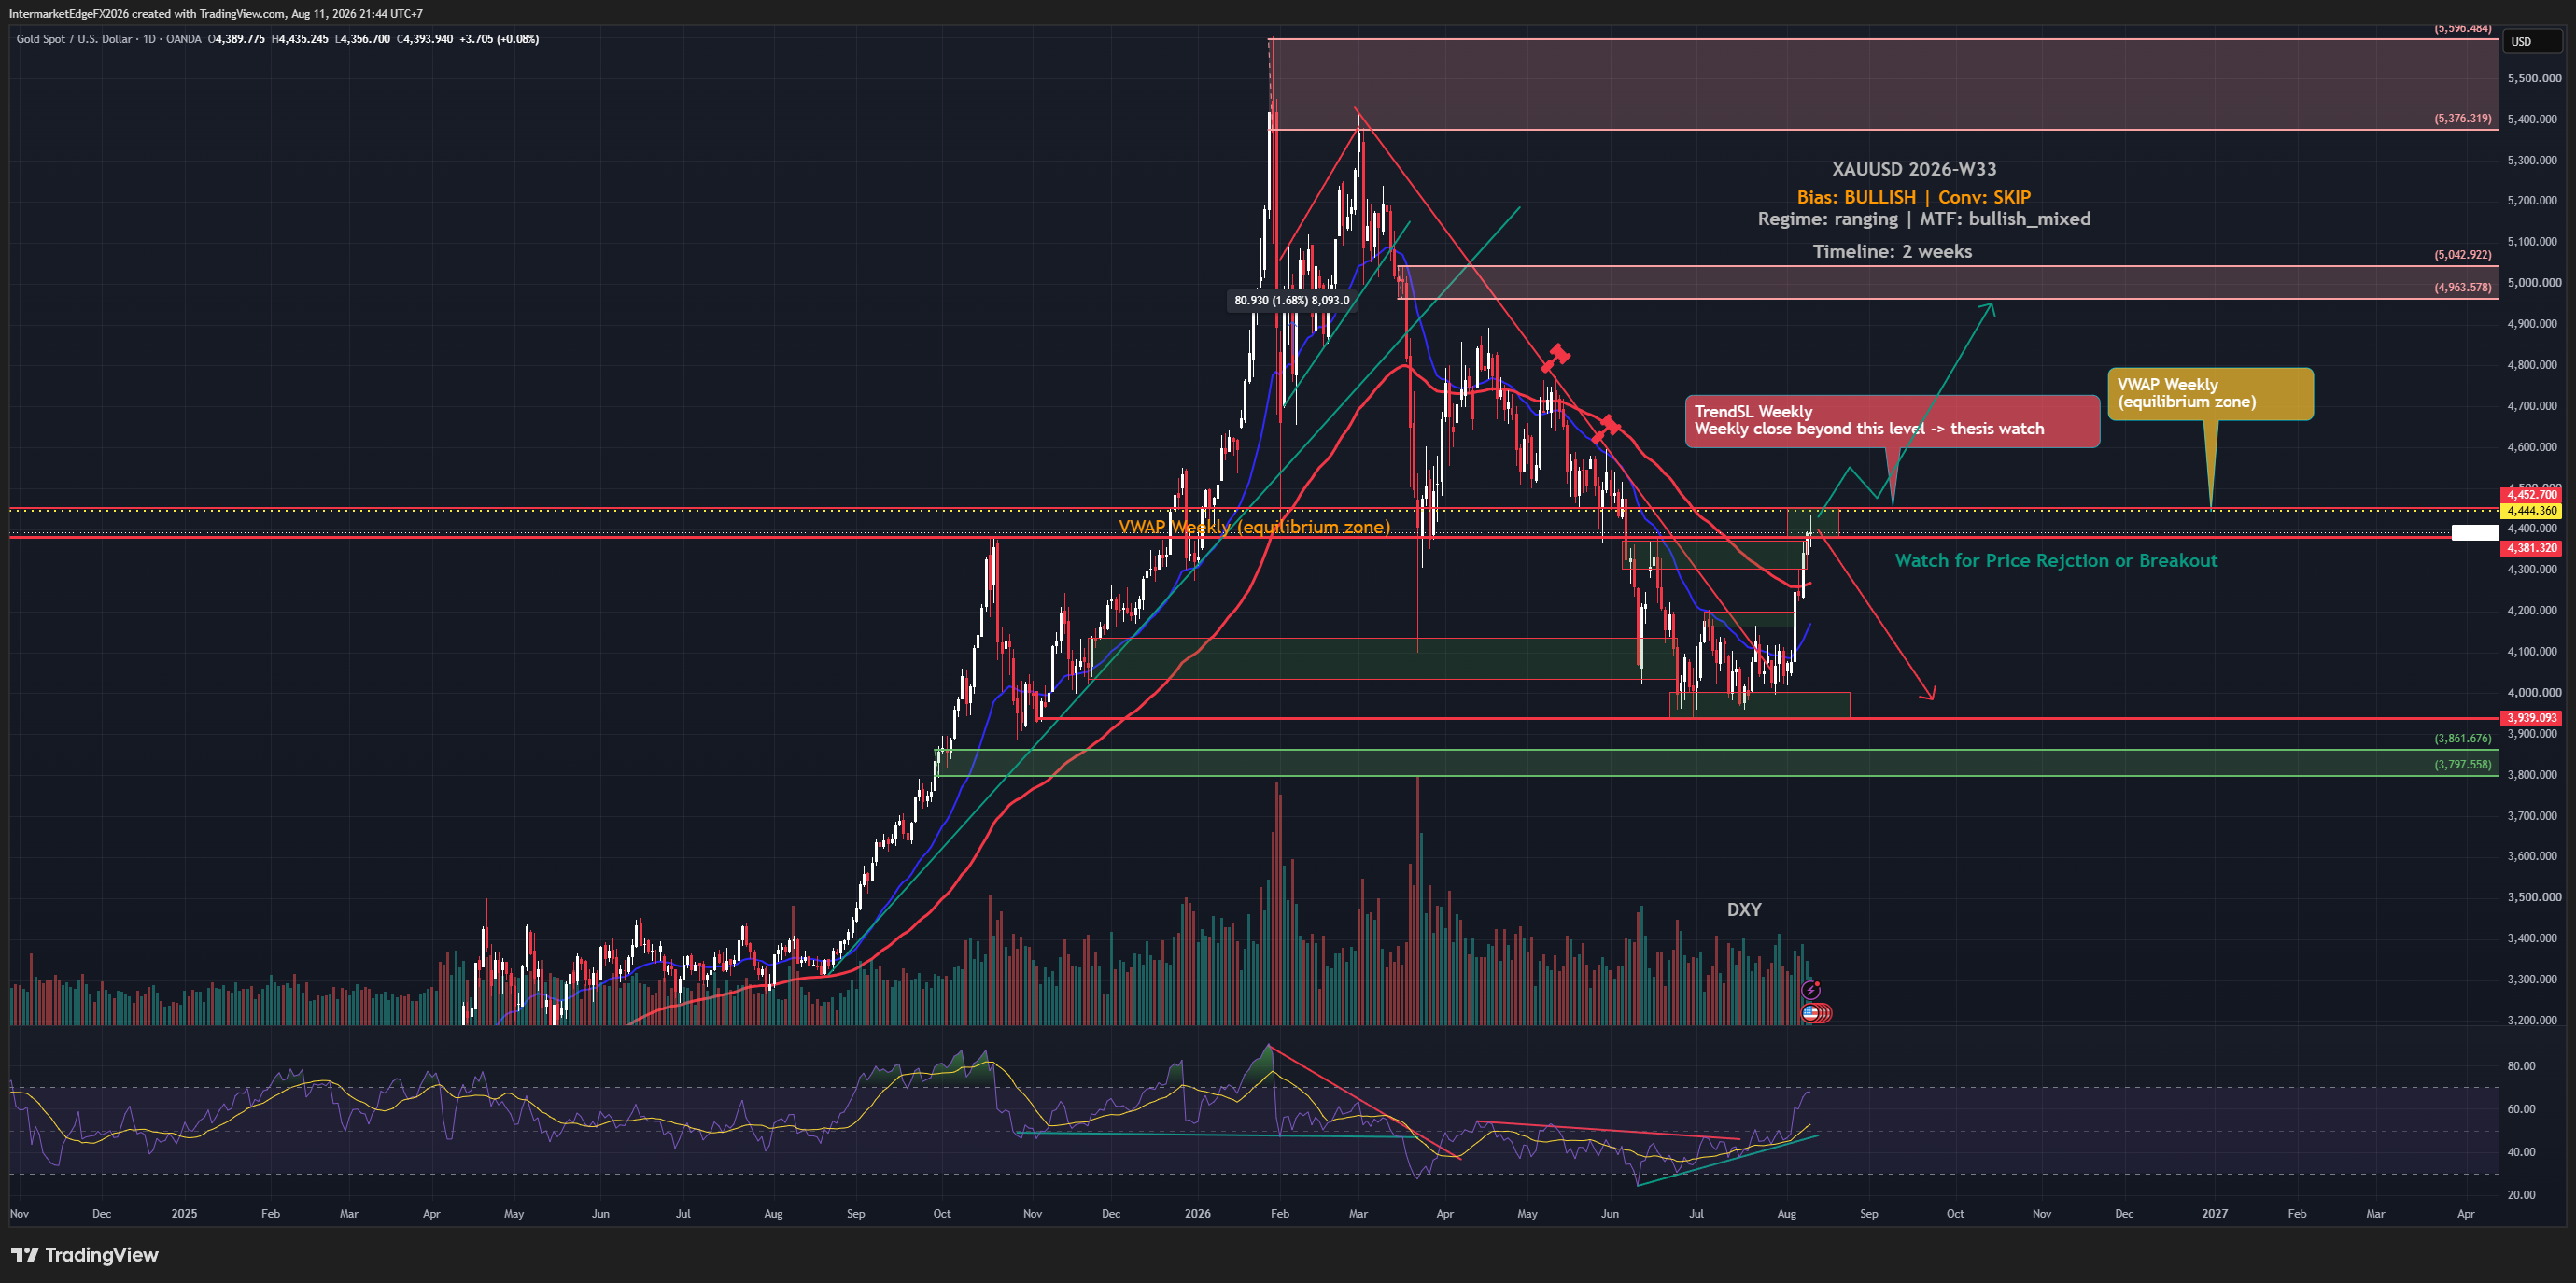
XAUUSD Week W33-2026: Gold Crosses the Line, but Confirmation Must Wait

XAUUSD Week W33-2026: Gold Crosses the Line, but Confirmation Must Wait

Gold printed a flat zero on the July Core CPI reading, the kind of number that should send an inflation hedge sharply higher. Instead, XAUUSD is hovering within a handful of dollars of a technical level that the bullish case still needs to close above on a weekly basis. The contradiction between a cooling inflation print and a 2.4% real yield that keeps the Fed's pressure alive is exactly the tension defining this week's tape. The overall lean for gold this week is bullish, but the honest framing is that this is a low-conviction technical bias rather than a macro-supported directional call. Price action and COT positioning, where large speculator positioning is tilted bullish, though the specific report date, net-position figure, and sample period are not disclosed in the underlying data, so treat this as directional evidence rather than a citable statistic, are carrying most of the analytical weight. The macro contribution is marginal, and both liquidity and sentiment indicators are quiet, offering no additional confirmation in either direction. The hawkish Fed causal chain is the key headwind worth understanding precisely: higher real yields reduce gold's relative appeal because bonds now compete meaningfully for capital, creating persistent downward pressure on prices. That chain has been deliberately downweighted in the framework after backtesting showed it produced correct directional calls only roughly 35.9% of the time when applied to XAUUSD specifically, a figure that comes without disclosed sample size or test period, so treat it as a caution flag rather than a hard statistical rule. The practical takeaway is that price and positioning should lead the analysis, not macro narratives alone. What makes this week's setup particularly difficult is that the CPI miss does not resolve the conflict, it creates a new one. -- Intermarket Edge

Stay in the loop

Get notified about new research, macro insights, and market analysis.

InterMarketEdge

© 2026 InterMarketEdge. Financial intelligence for inter-market traders.