Tag: cable — InterMarketEdge

Tag: cable

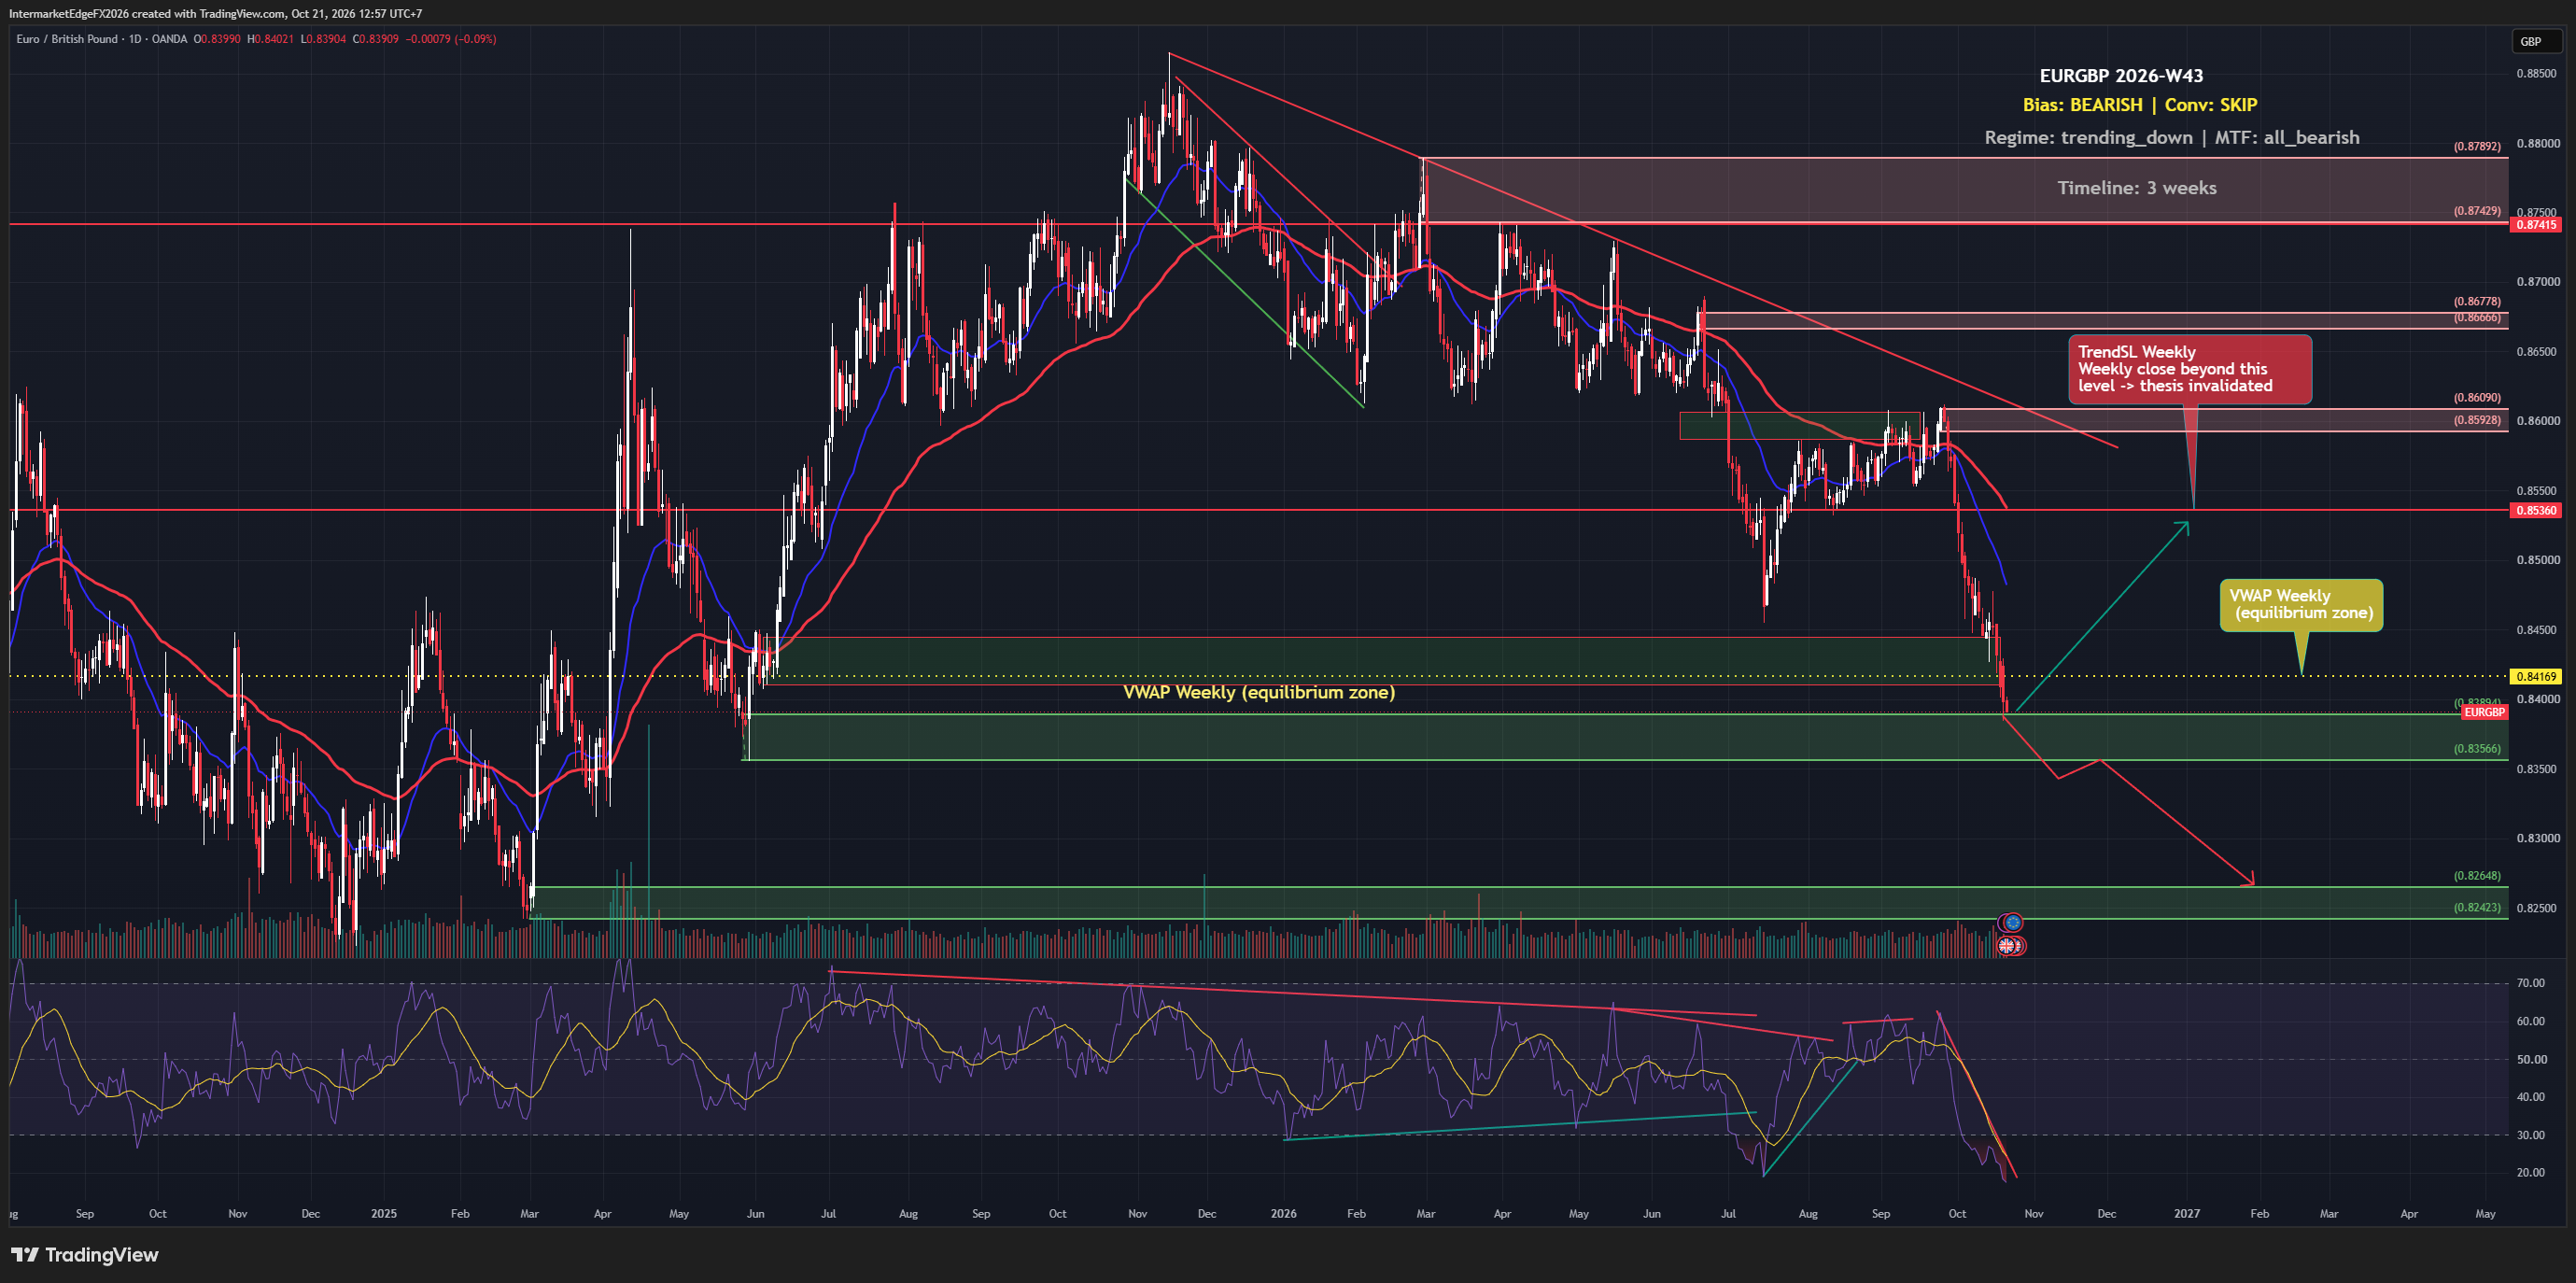
EURGBP W43: Sterling Support Meets an Unresolved Price Conflict

EURGBP W43: Sterling Support Meets an Unresolved Price Conflict

EURGBP W43: bearish three-week view; stand aside. Downward trends coexist with bullish price action. At 05:38 UTC on Wednesday, 21 October 2026, EURGBP was 0.83944, below weekly VWAP 0.84169 and below weekly TrendSL 0.85360. Source: mt5:EURGBP.sml:1m. This is a dated observation, not a live quote. Both risk conditions remain pending in this observation. If price sustains above weekly VWAP 0.84169, momentum would run against the bearish view and short exposure would warrant reduced size. A weekly close above TrendSL 0.85360 would invalidate the bearish structure: exit shorts and reassess. The momentum watch has no added daily or weekly closing requirement. FXSSI: 72% long / 28% short, collected 21 October at 05:38:28 UTC. Broker sample, provider observation time unverified; contrarian context, not an independent sell signal. COT CFTC TFF, Leveraged Funds, report date 2026-10-13: EUR 099741 net short 68,001, net change -23,740; GBP 096742 net long 10,313, change -2,119 contracts versus 6 October. Separate futures components, not direct EURGBP positions; release dates unverified. This is a pre-CPI assessment. ONS scheduled UK September CPI for 21 October at 06:00 UTC. No actual outcome is included. Hotter UK inflation could support GBP if relative rate expectations rise; softer inflation could support a recovery in EURGBP. Check price and relative yields after the release. Intermarket Edge | Institutional Macro & Intermarket Analysis For informational and educational purposes only. Not financial advice.
EURJPY W42: A Bearish View Without a Clear Entry

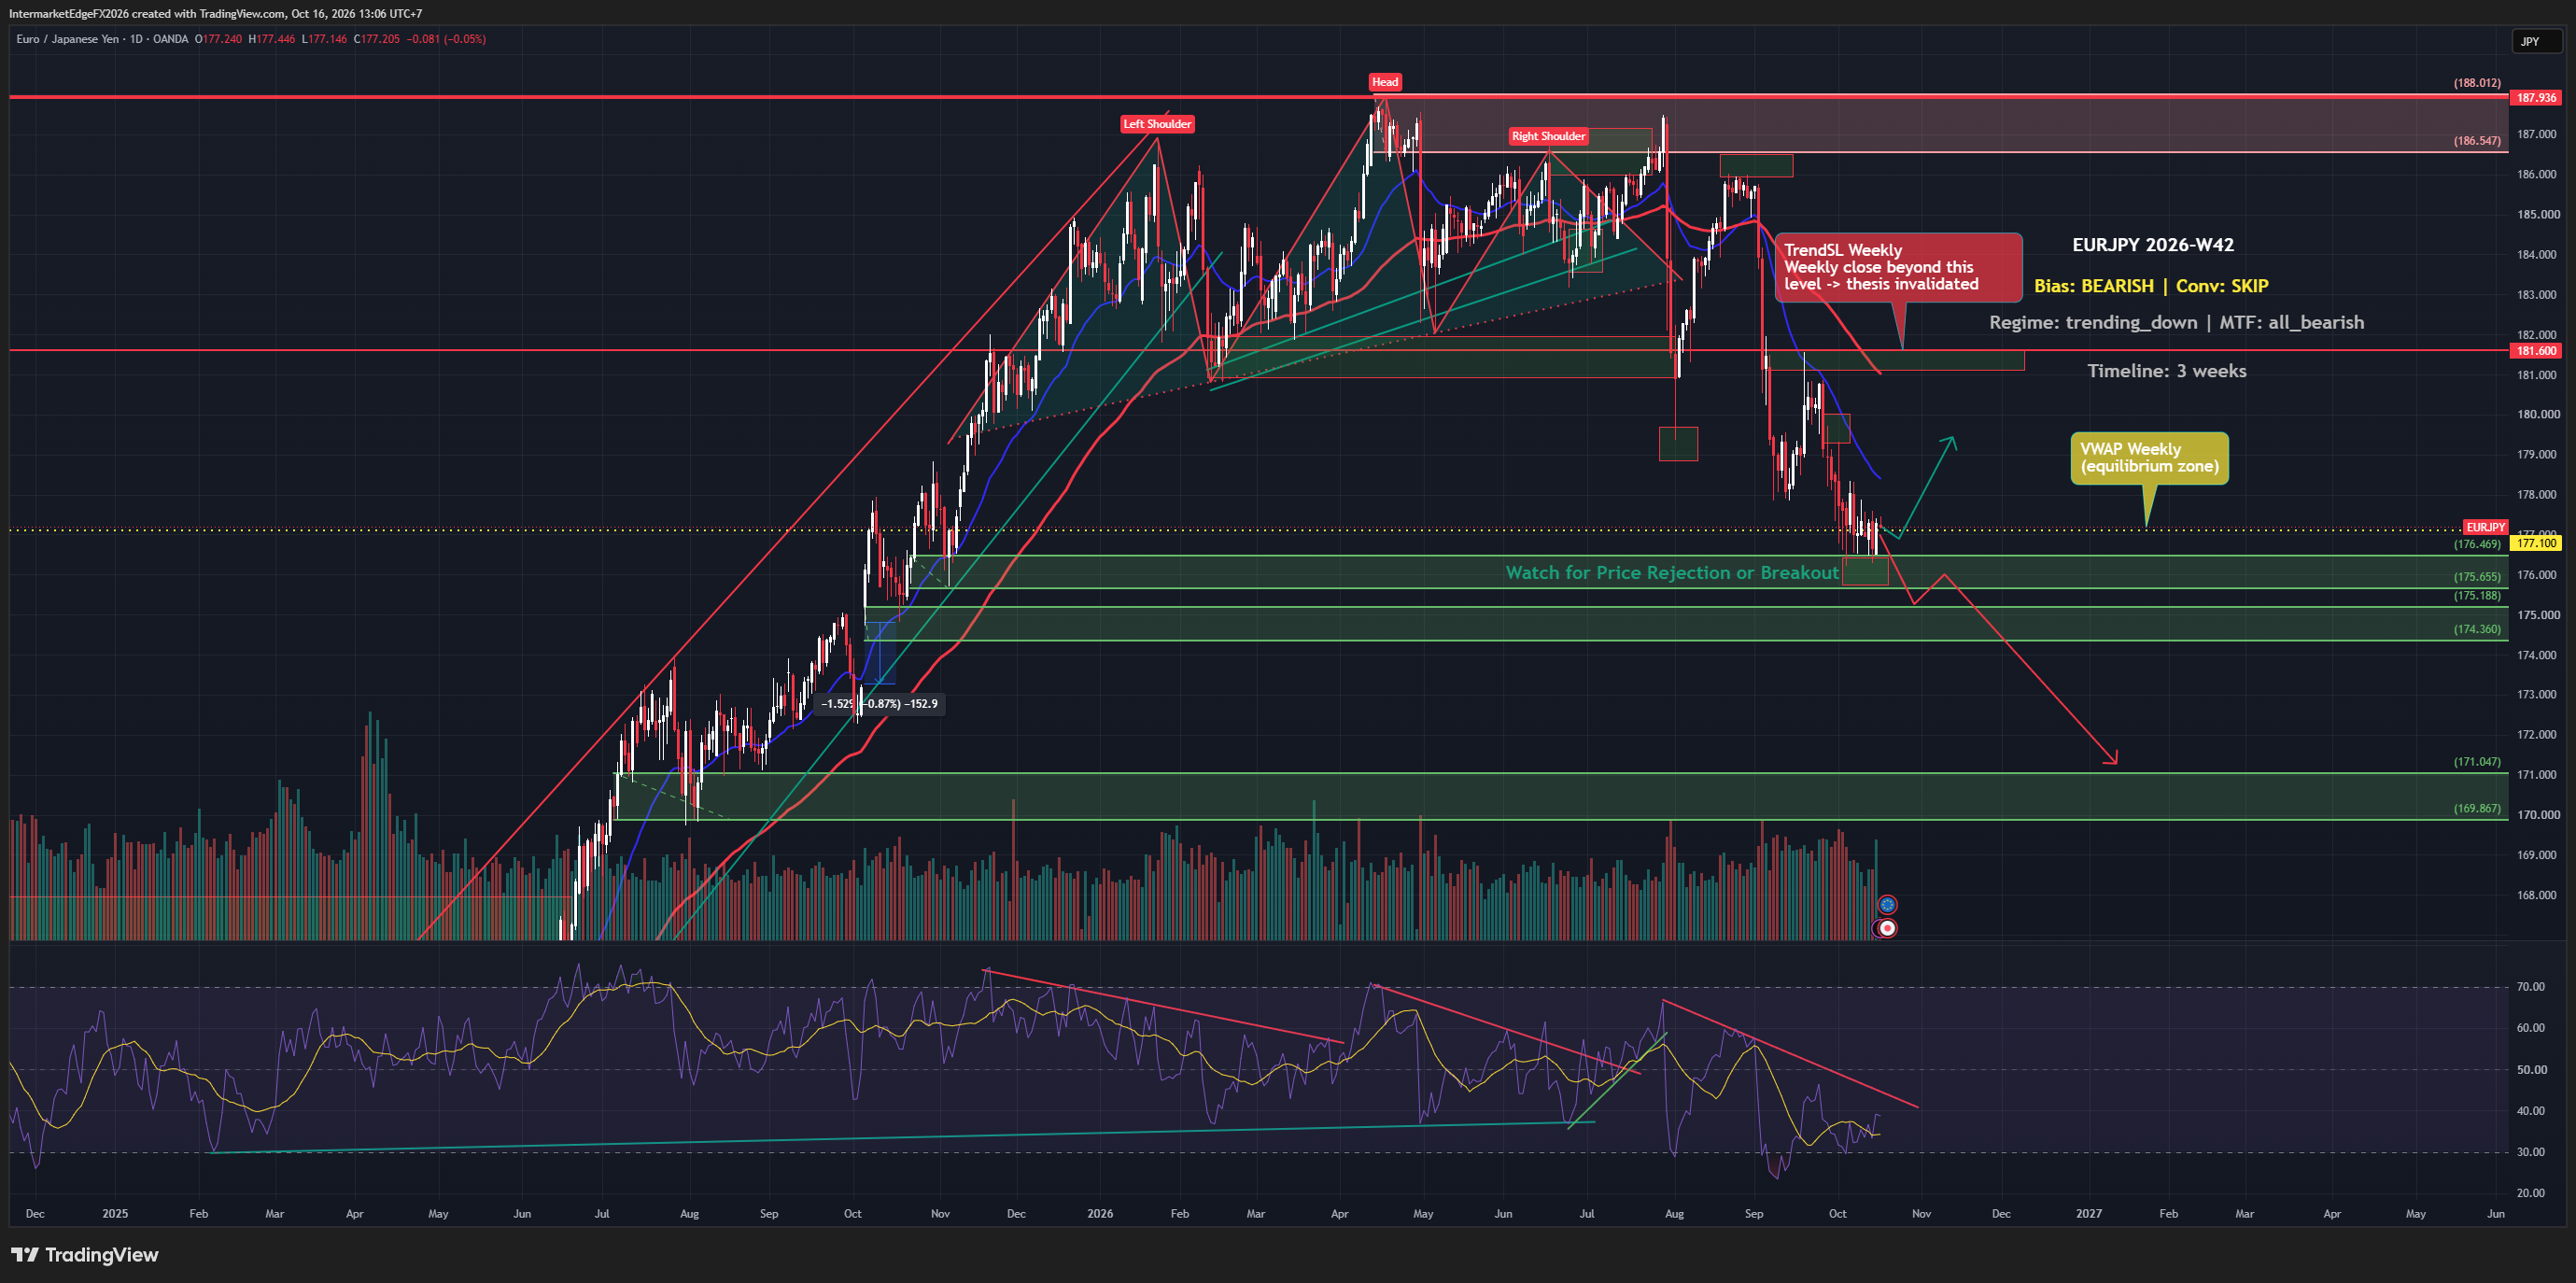
EURJPY W42: A Bearish View Without a Clear Entry

EURJPY W42: bearish three-week view; stand aside for new exposure. At 16/10/2026 06:03 UTC, EURJPY was 177.186, above weekly VWAP 177.102 and below weekly TrendSL 181.597. Source: mt5:EURJPY:1m, a timestamped broker quote. The momentum warning is already active: price is above the weekly average, running against the bearish thesis. For existing shorts, reduce position size now. This condition requires no daily or weekly close. A completed weekly close above 181.597 would invalidate the bearish structure, requiring an exit from shorts and reassessment. This structural invalidation condition remains pending. Compare EURUSD, USDJPY and matching German-Japanese yields. A euro recovery against USD does not establish this cross's direction. The opposing bullish assessment remains a reason to wait for stronger evidence. --- Intermarket Edge | Institutional Macro & Intermarket Analysis For information and education only. Not financial advice.

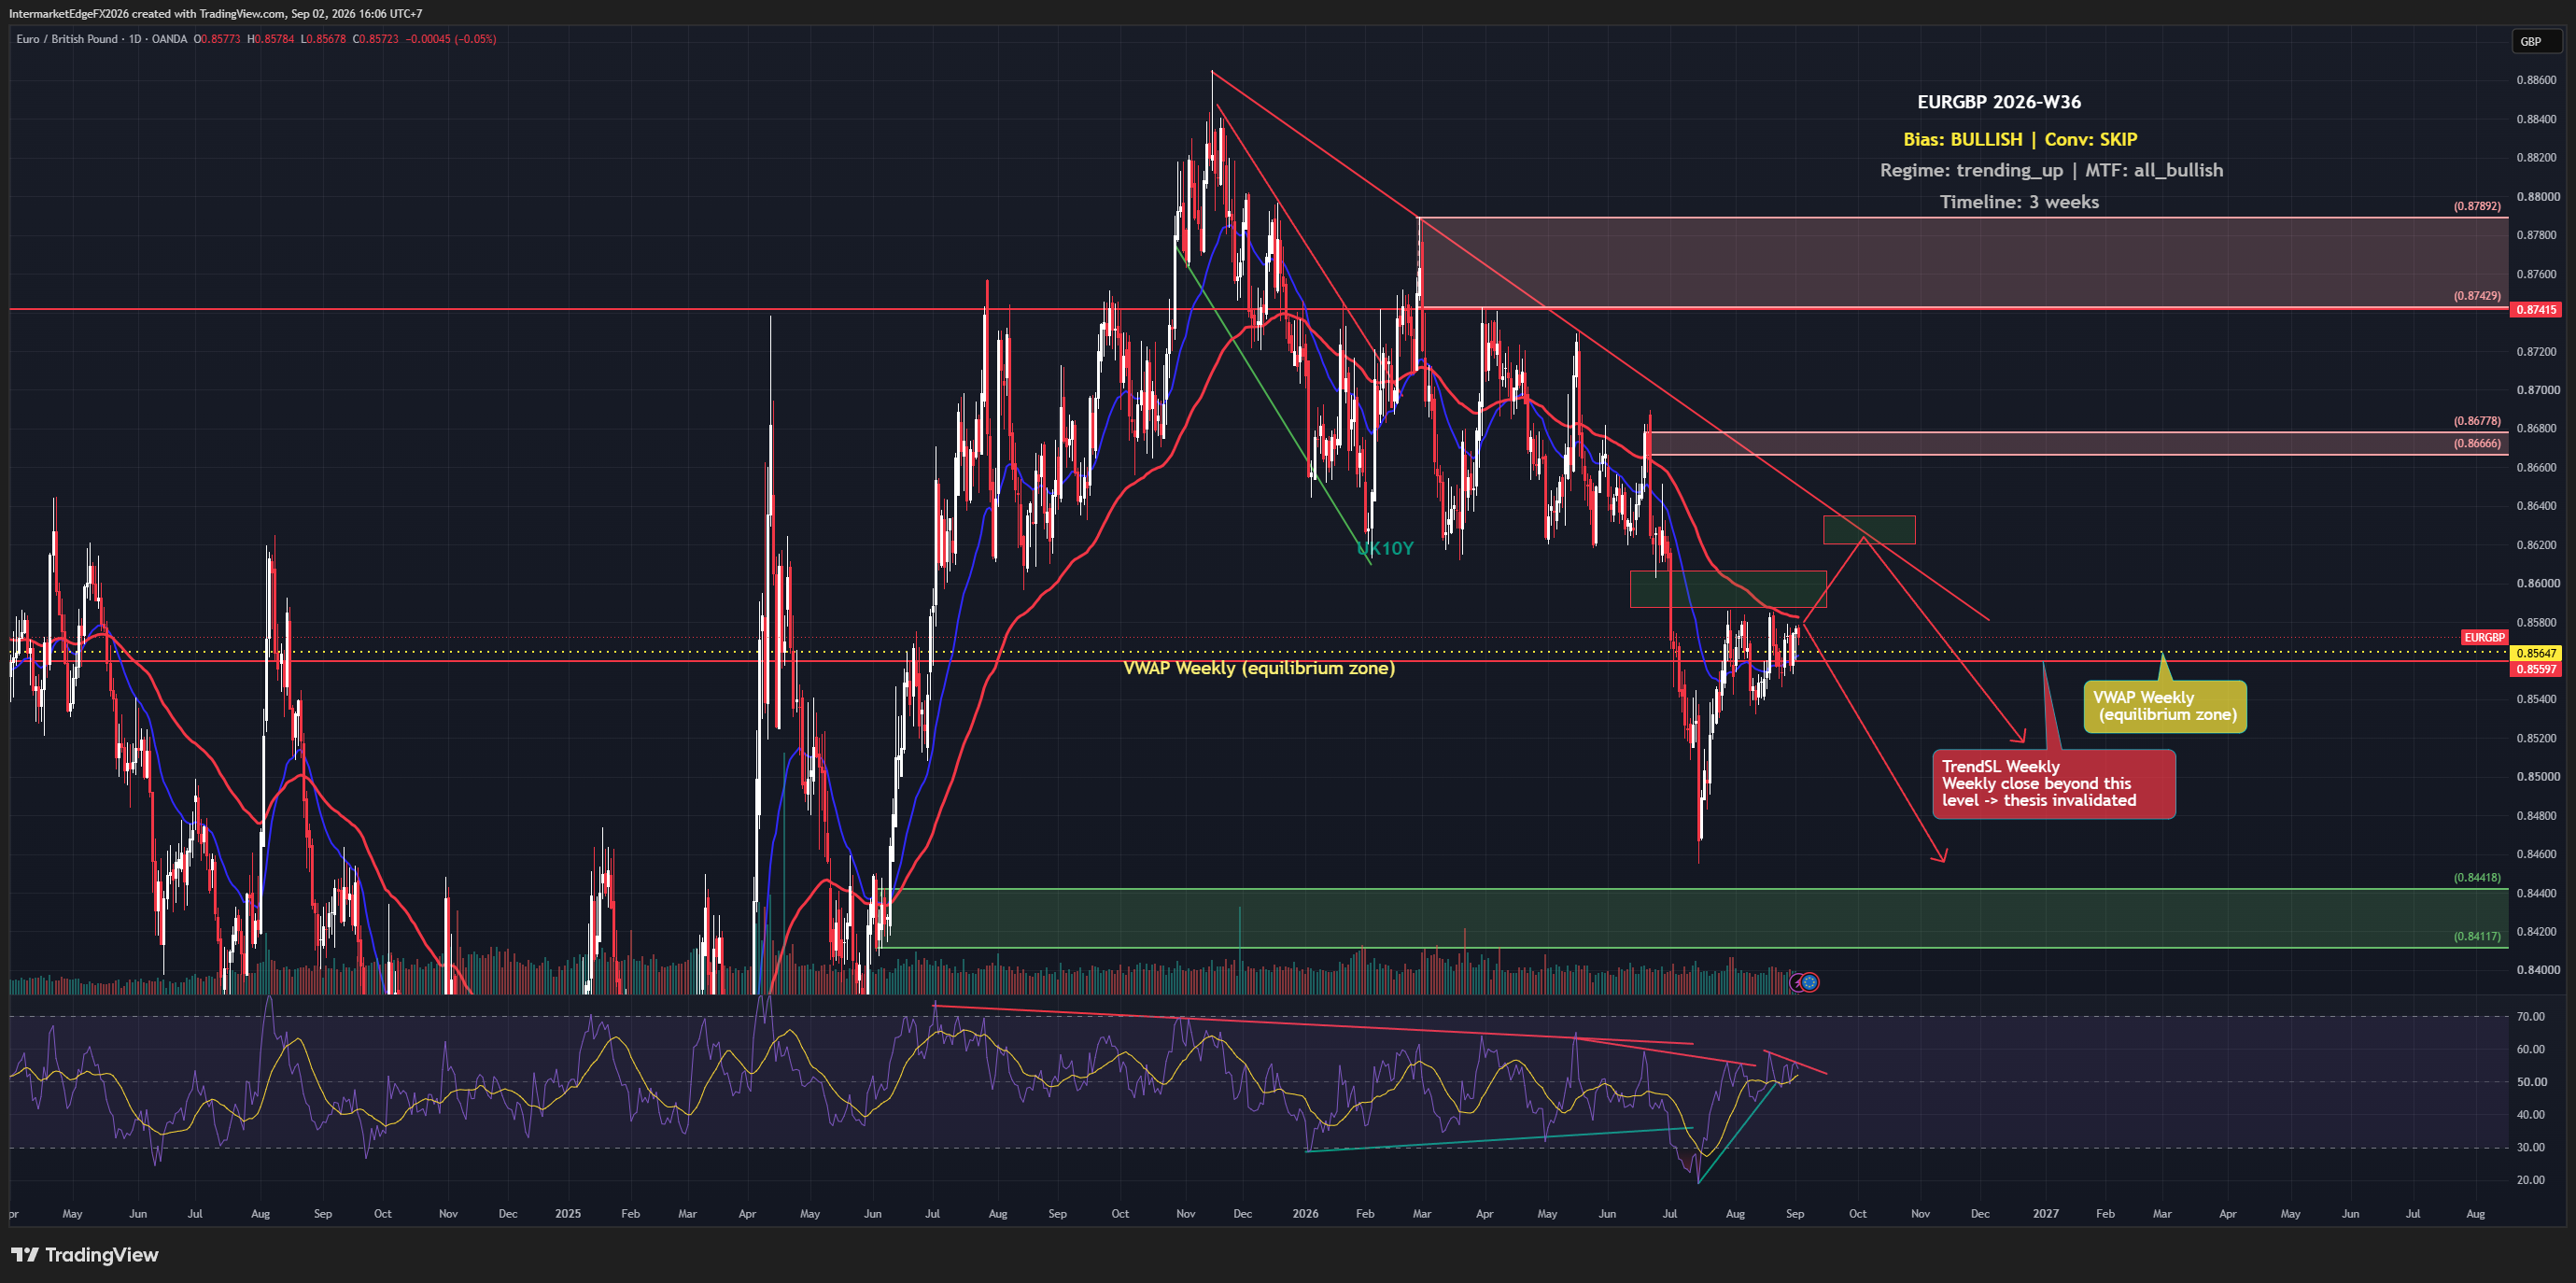
EURGBP Week W36-2026: Technicals Hold Bullish Structure Above 0.85647, But the Macro Story Has a Hole in It

EURGBP Week W36-2026: Technicals Hold Bullish Structure Above 0.85647, But the Macro Story Has a Hole in It

EURGBP is trading above its weekly VWAP at 0.8577 as of Wednesday, 02 September 2026, with charts aligned bullish across every timeframe. The catch: the entire bullish case rests on technical structure alone, no macro confirmation, no positioning signal, nothing beyond price telling you which way to lean. That narrow foundation is exactly what makes this week's setup worth watching carefully rather than trading aggressively. The bullish bias on EURGBP this week is real but structurally thin. Daily, weekly, and monthly technical trend signals are all pointing the same direction, that multi-timeframe alignment, where price structure agrees across short, medium, and long horizons, is the strongest argument for the upside case. It reduces the probability that you are catching a random short-term noise move against a larger trend. What it does not do is tell you why the move should continue or how far it goes. The stated fundamental driver for this pair is the ECB versus BoE rate differential, the gap between where the two central banks are setting rates and where markets expect them to go, which directly affects the relative attractiveness of holding euros versus pounds. That differential is a plausible and historically significant driver for EURGBP. The problem this week is that the macro evidence has produced no confirming signal. The rate differential is the narrative, but the data behind it has not fired. That gap between a coherent story and an absent signal is the defining tension. The practical consequence is that the conviction level here amounts to a deliberate decision to stand aside. The technical foundation is present; everything else that would normally underpin a higher-confidence directional trade, positioning data, a macro catalyst, sentiment confirmation, is not contributing. -- Intermarket Edge

EURGBP Week W35-2026: Sterling Pauses Its Four-Week Rally, but the Bullish Case Sits Below Every Key Level

EURGBP Week W35-2026: Sterling Pauses Its Four-Week Rally, but the Bullish Case Sits Below Every Key Level

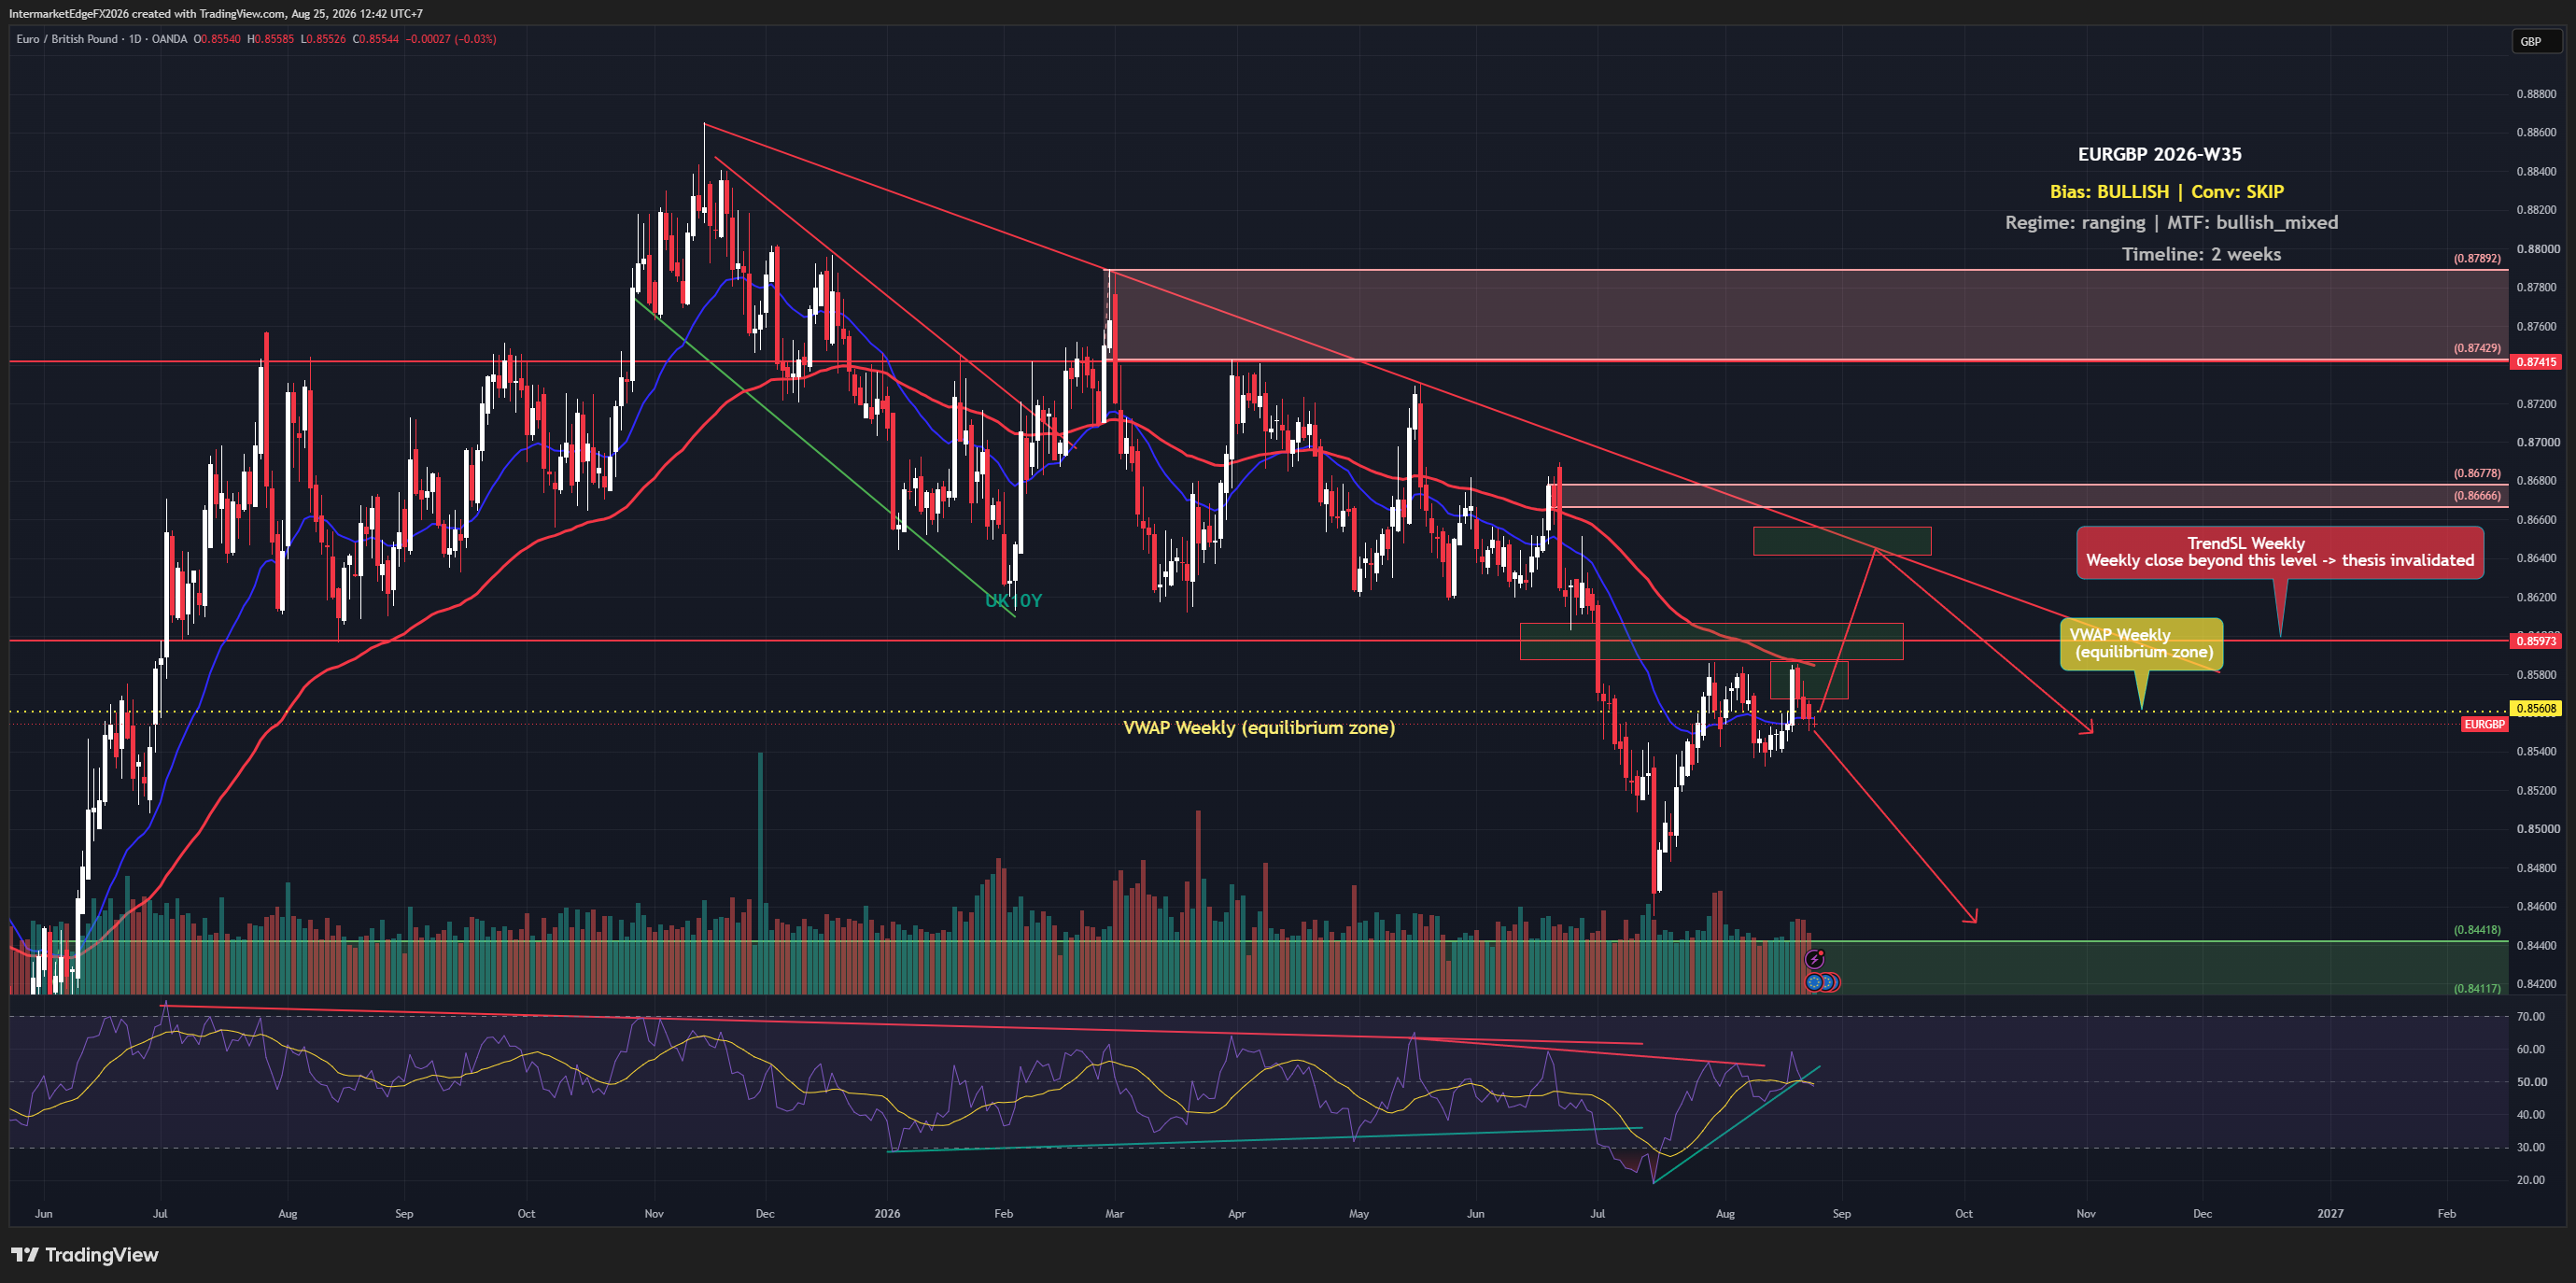
EURGBP is sitting below its weekly VWAP of 0.85608 as of Tuesday, 25 August 2026, and the technical structure already contradicts the tentative bullish lean this week carries. Sterling just paused a four-week rally as investors repositioned around US sanctions on Iran, while the ECB is signaling caution on rates even as the eurozone shows unexpected resilience. The pair is caught between two central banks pulling in different directions, and right now, neither side has won. The framework labels EURGBP bullish for the two-week horizon beginning W35-2026, but the honest description of that label is that it rests on a single thin pillar: price action alone. Every other input, positioning data, macro signals, liquidity conditions, sentiment, is neutral and contributing nothing to the directional call. That kind of setup, where one source carries the entire argument, is precisely where conviction becomes a problem, and this analysis treats it as such. The decision here is deliberately to stand aside rather than size a position, because the evidence is not yet convincing enough to justify the directional risk. The stated primary driver is the ECB versus Bank of England rate differential, the practical meaning of which is that when the ECB is expected to hold or cut while the BOE is expected to hike, Sterling strengthens relative to the euro, pushing EURGBP down, and vice versa. But here is the disconnect that matters: no rate-specific or macro-specific signals have actually fired in support of the bullish label. The driver is named but not confirmed by the inputs. Compounding that, the structural or longer-term bias is neutral, which conflicts with the short-term bullish lean. -- Intermarket Edge

EURUSD W34: A Bearish Thesis Without Technical Confirmation

EURUSD W34: A Bearish Thesis Without Technical Confirmation

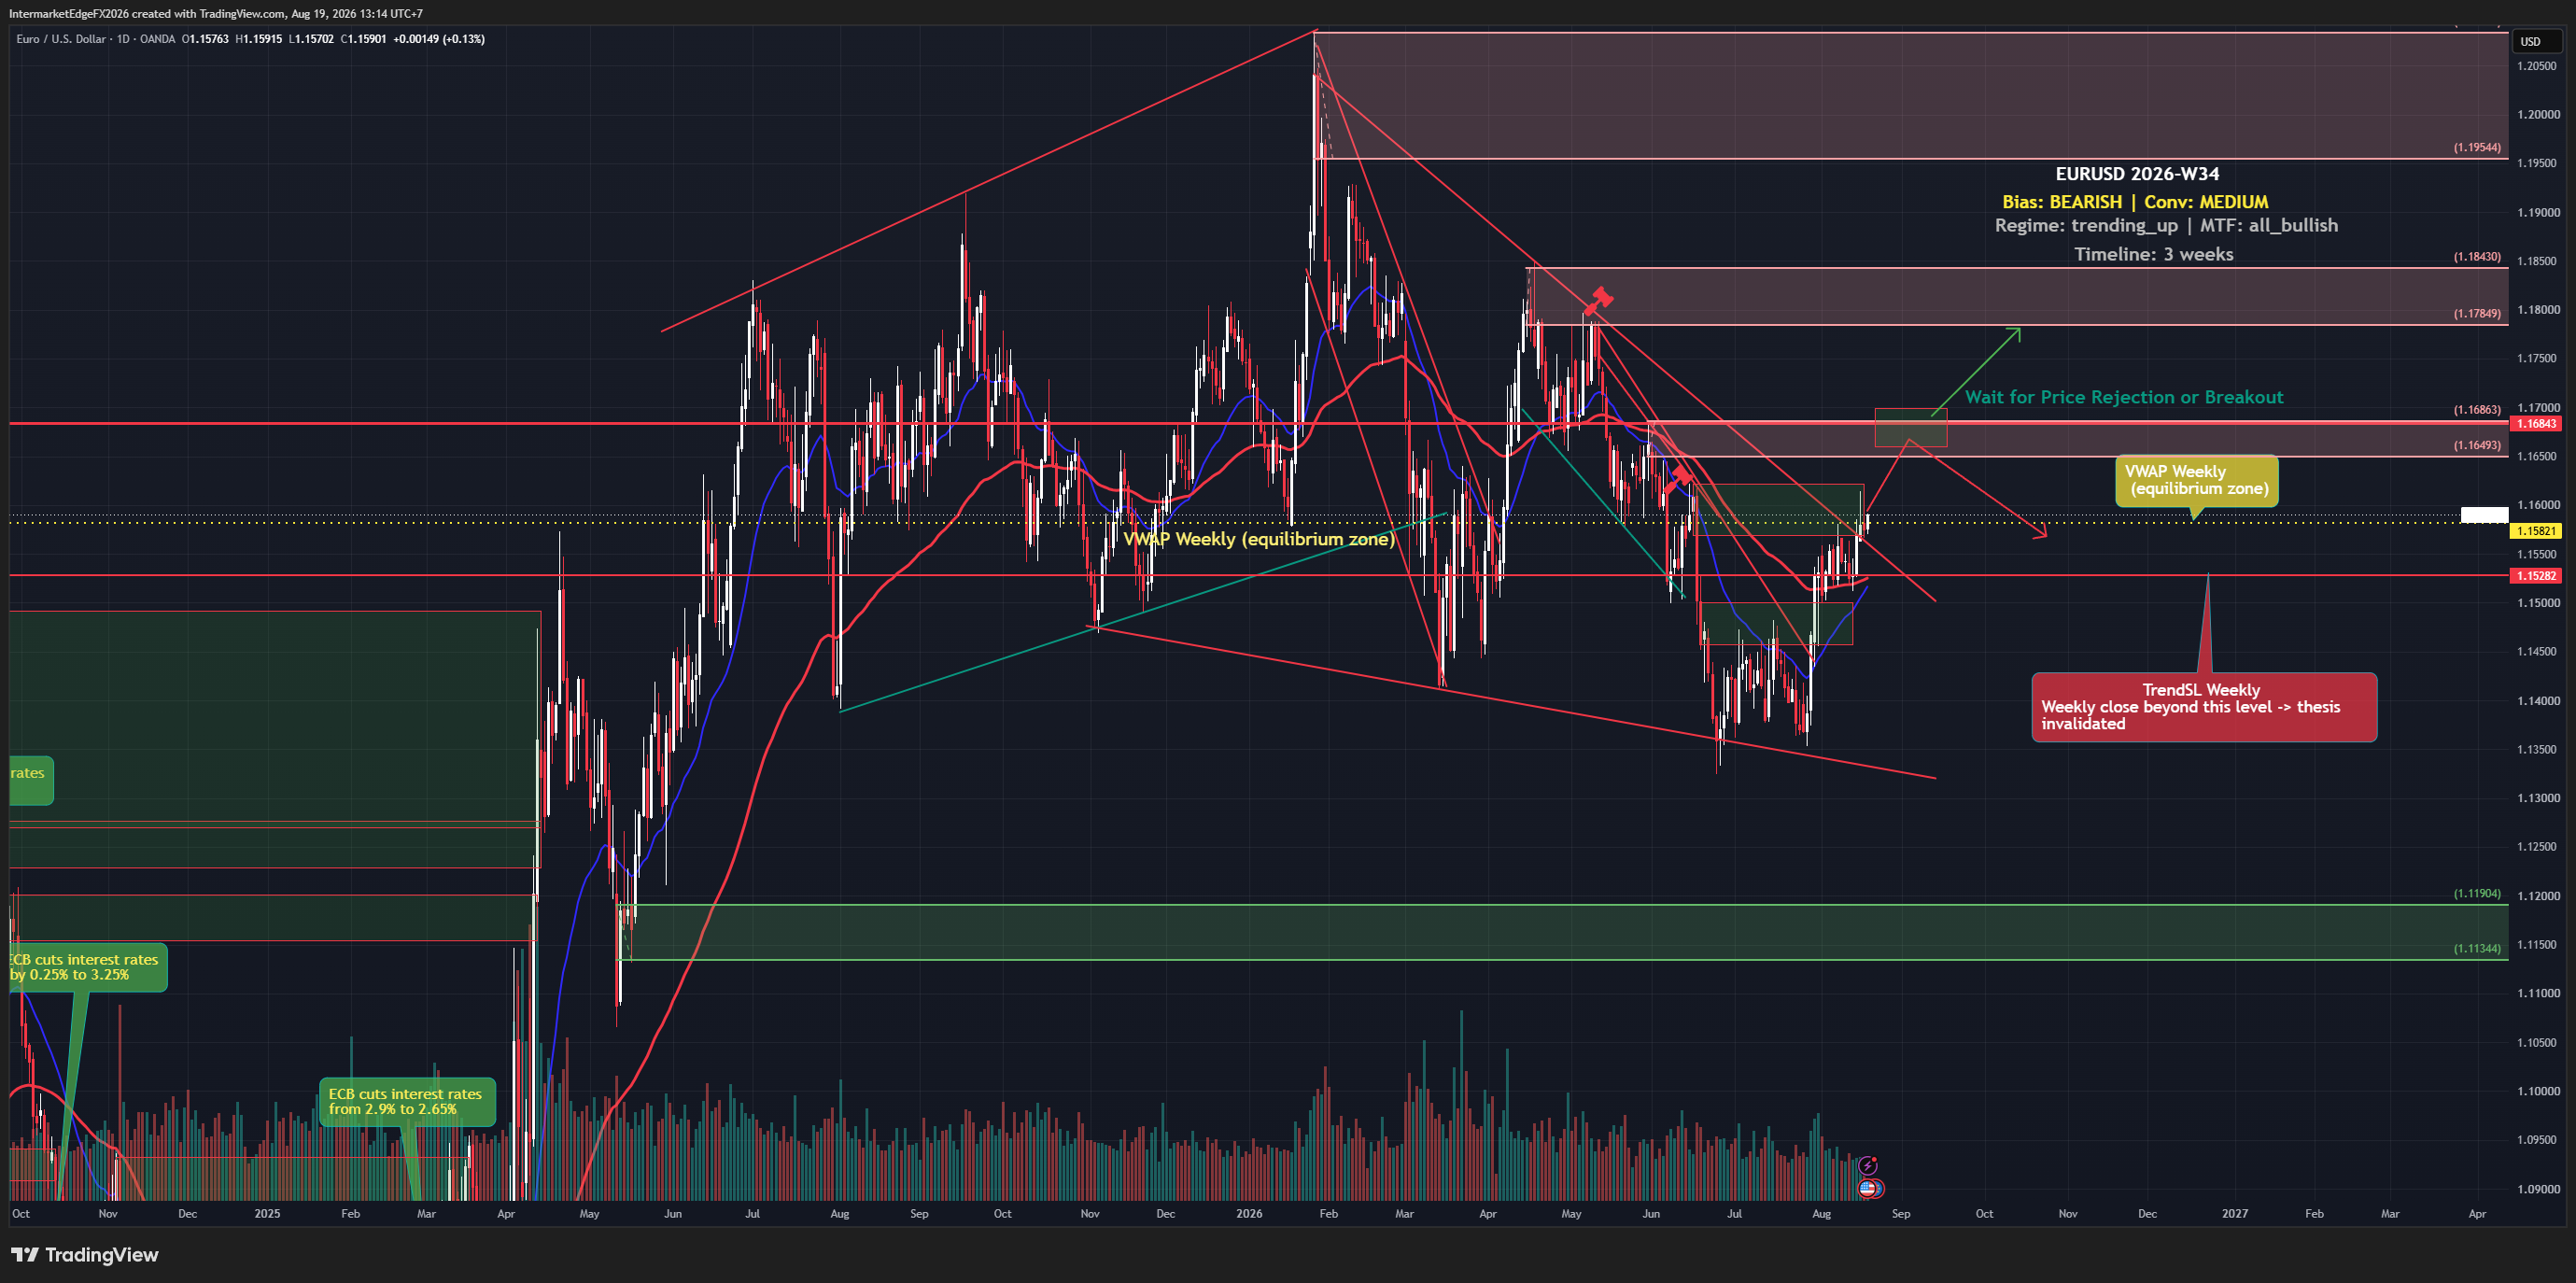
EURUSD is trading at 1.15824 as of Wednesday, 19 August 2026, sitting directly on the weekly VWAP zone at 1.15821. Markets are pricing a dovish Fed pivot while US 10-year real yields simultaneously sit at 2.44%, a level that historically pulls capital into USD. When price, COT positioning, and every timeframe chart point one direction but the macro structural case points the other, one of those signals is about to be proven wrong. The framework's structural conclusion for EURUSD this week is bearish, driven primarily by the ECB versus Fed rate differential, meaning the gap between what the European Central Bank pays relative to the Federal Reserve makes the euro a lower-yielding, less attractive carry currency, which mechanically pushes EUR/USD lower as capital allocates toward the higher-yielding dollar side. Rising US real yields at 2.44% reinforce this causal chain with significant weight: real yield advantage attracts foreign capital into Treasuries, which requires buying USD first, compressing EUR/USD in the process. Here is where the analysis becomes genuinely uncomfortable, and honest about it: the conviction sits at medium rather than high precisely because every other signal currently contradicts that structural conclusion. Price itself is constructive. Commitment of Traders positioning, which tracks what different categories of market participants are reporting, though the specific report week and net-position figures are not confirmed in this brief, so treat this as directional evidence rather than a precise statistic, shows leveraged funds at extreme short positioning even as price trends higher. -- Intermarket Edge

EURGBP Week W33-2026: BOE Holds at 3.75% But Sterling Fights Back, Leaving Bulls Stranded Below 0.8566

EURGBP Week W33-2026: BOE Holds at 3.75% But Sterling Fights Back, Leaving Bulls Stranded Below 0.8566

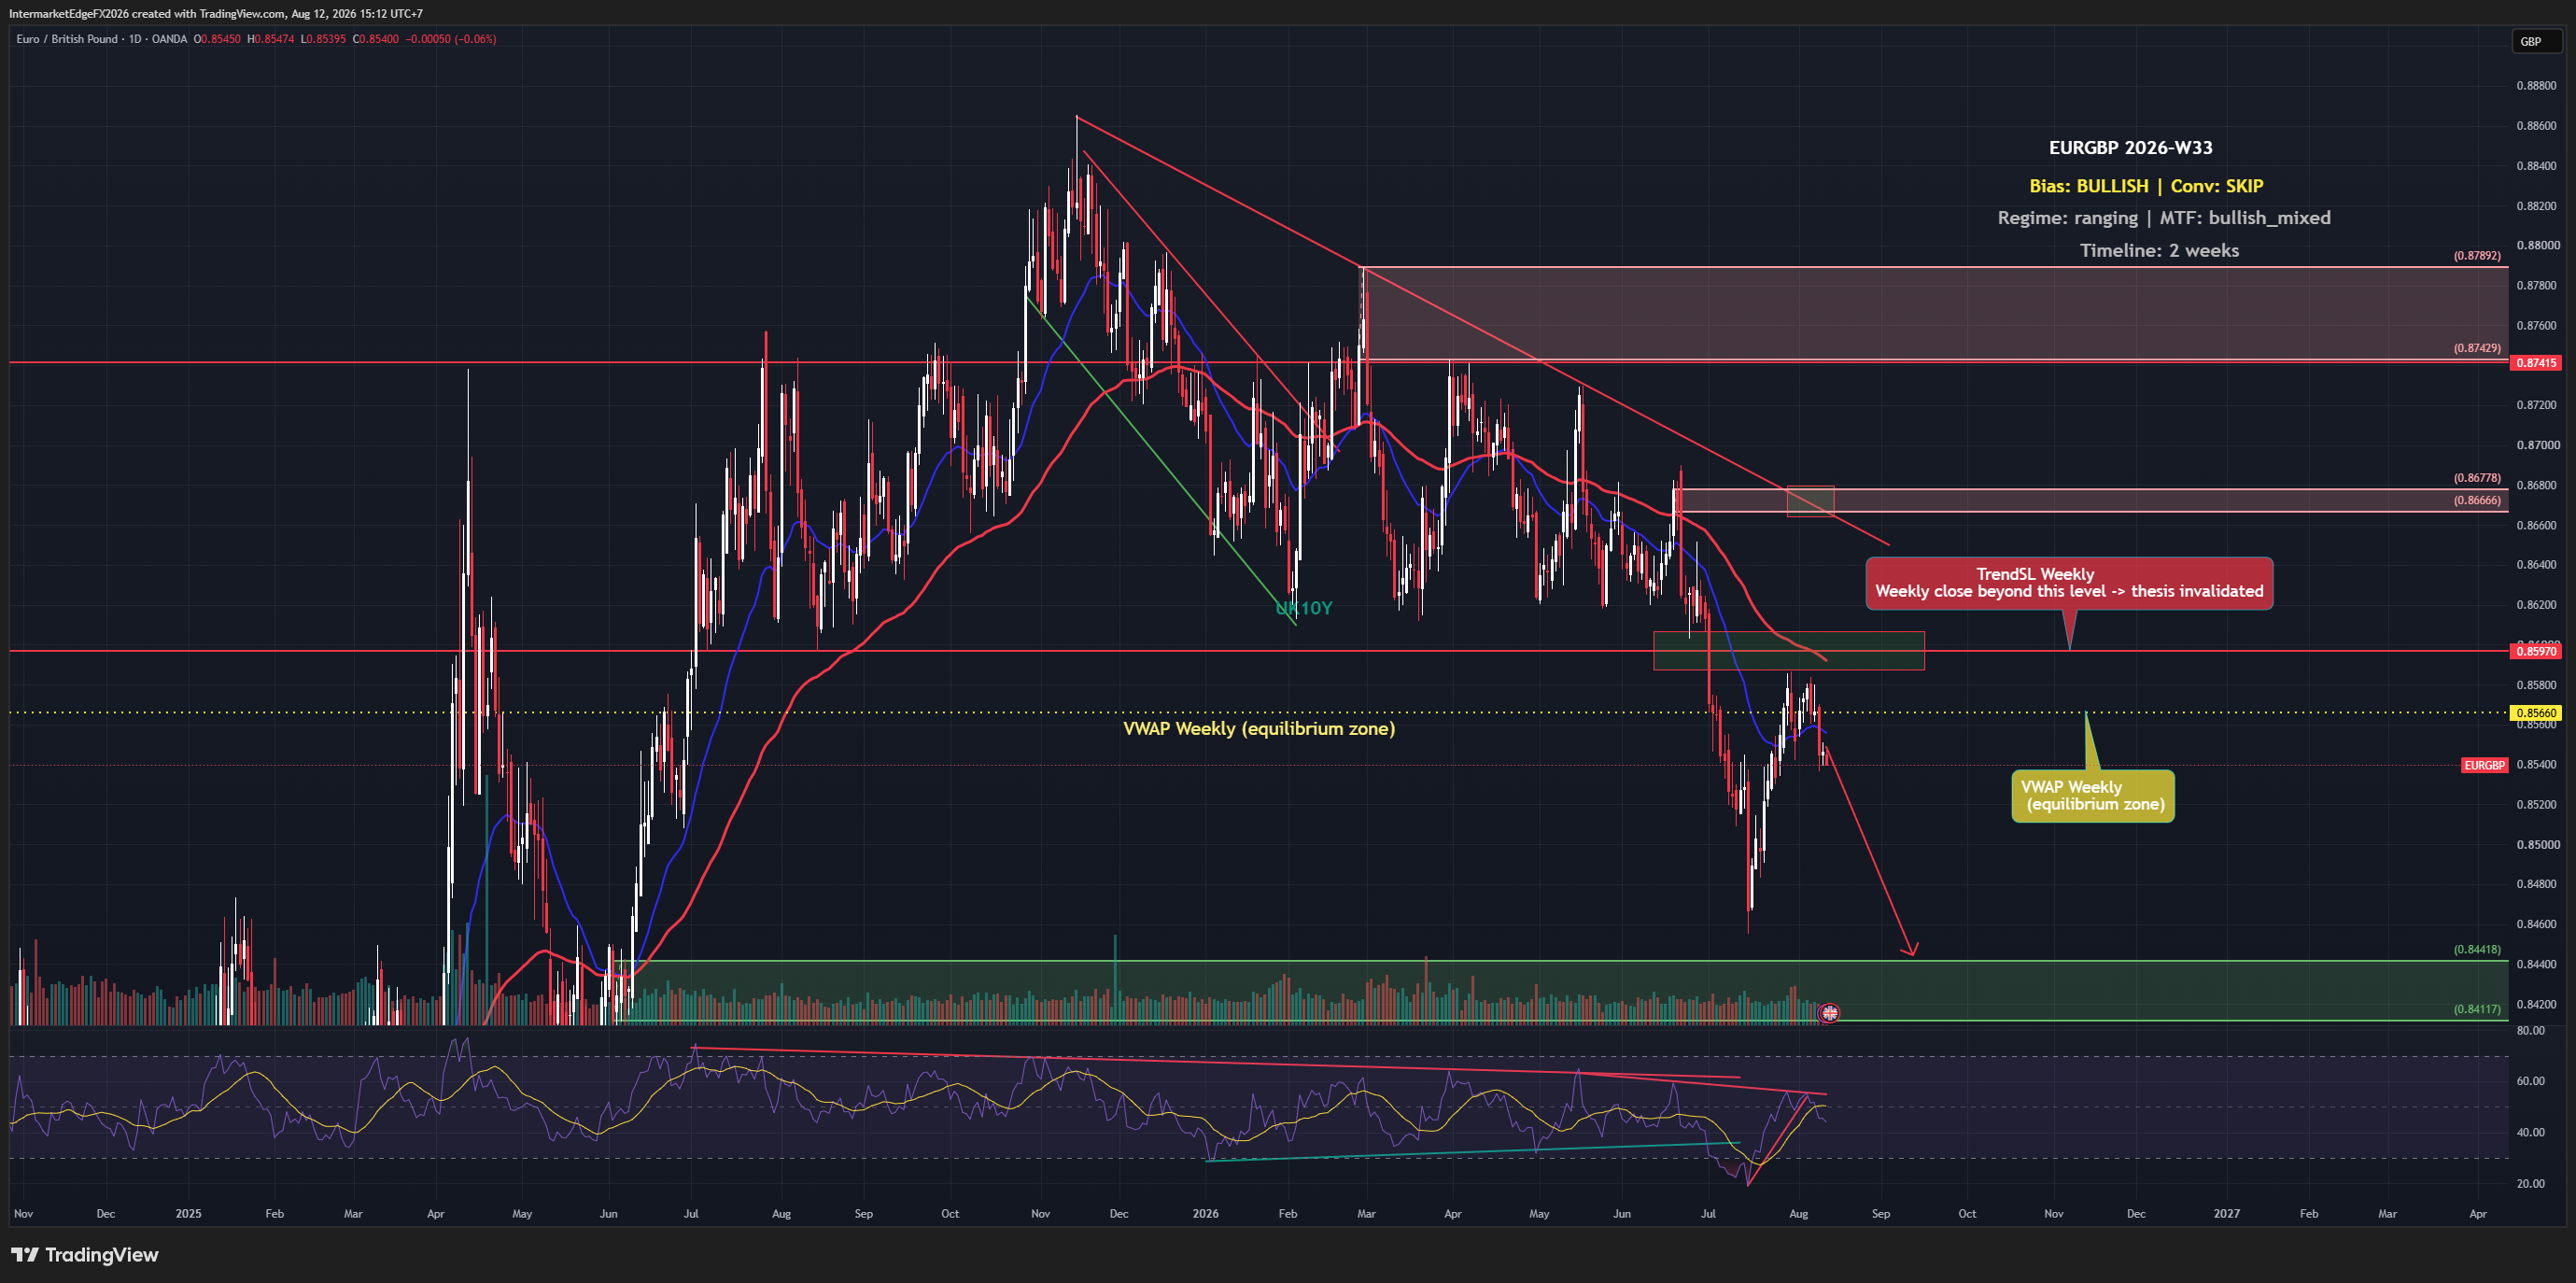
EURGBP is technically labelled bullish this week, yet as of Wednesday 12 August 2026, price at 0.85407 is sitting below the weekly VWAP at 0.8566, testing from underneath rather than pushing through it. That gap between the label and the price reality is exactly the kind of setup where traders get caught leaning on a bias that the market itself hasn't confirmed yet. With a BOE divided 6-3 on holding rates and a Euro-area CPI miss already in the books, neither side has a clean fundamental edge right now. The framework arrives at a weak bullish lean on EURGBP for this two-week window, but it is important to understand precisely how thin that lean is. The only active signal driving the bullish label comes from price action itself; positioning data, macro rules, liquidity signals, and sentiment indicators all contribute nothing, they fired no confirming evidence. A bias resting on a single source with no corroboration from other analytical layers is, by design, a low-confidence read that demands a correspondingly cautious posture. The analysis explicitly flags a structural conflict at the heart of the thesis: the overall directional label is bullish, but the structural bias is neutral, meaning the two core components of the framework are not pointing the same way. That internal contradiction is not a rounding error, it is a direct signal that the environment has not yet organised itself into a tradeable directional setup. The ECB-versus-BOE rate differential is cited as the primary fundamental narrative, the idea being that if ECB policy holds firmer relative to BOE policy, euro support should outpace sterling support over time. But no macro rule within the analysis has fired to validate that narrative in a quantifiable way this week, so it remains a story rather than a confirmed driver. What this means practically: the bullish label should be read as a directional lean, not a conviction call. -- Intermarket Edge

GBPUSD Week W31-2026: Sellers Push Price to Lowest Since July 2 as Fed Decision Looms and Rate Differential Widens Against Sterling

GBPUSD Week W31-2026: Sellers Push Price to Lowest Since July 2 as Fed Decision Looms and Rate Differential Widens Against Sterling

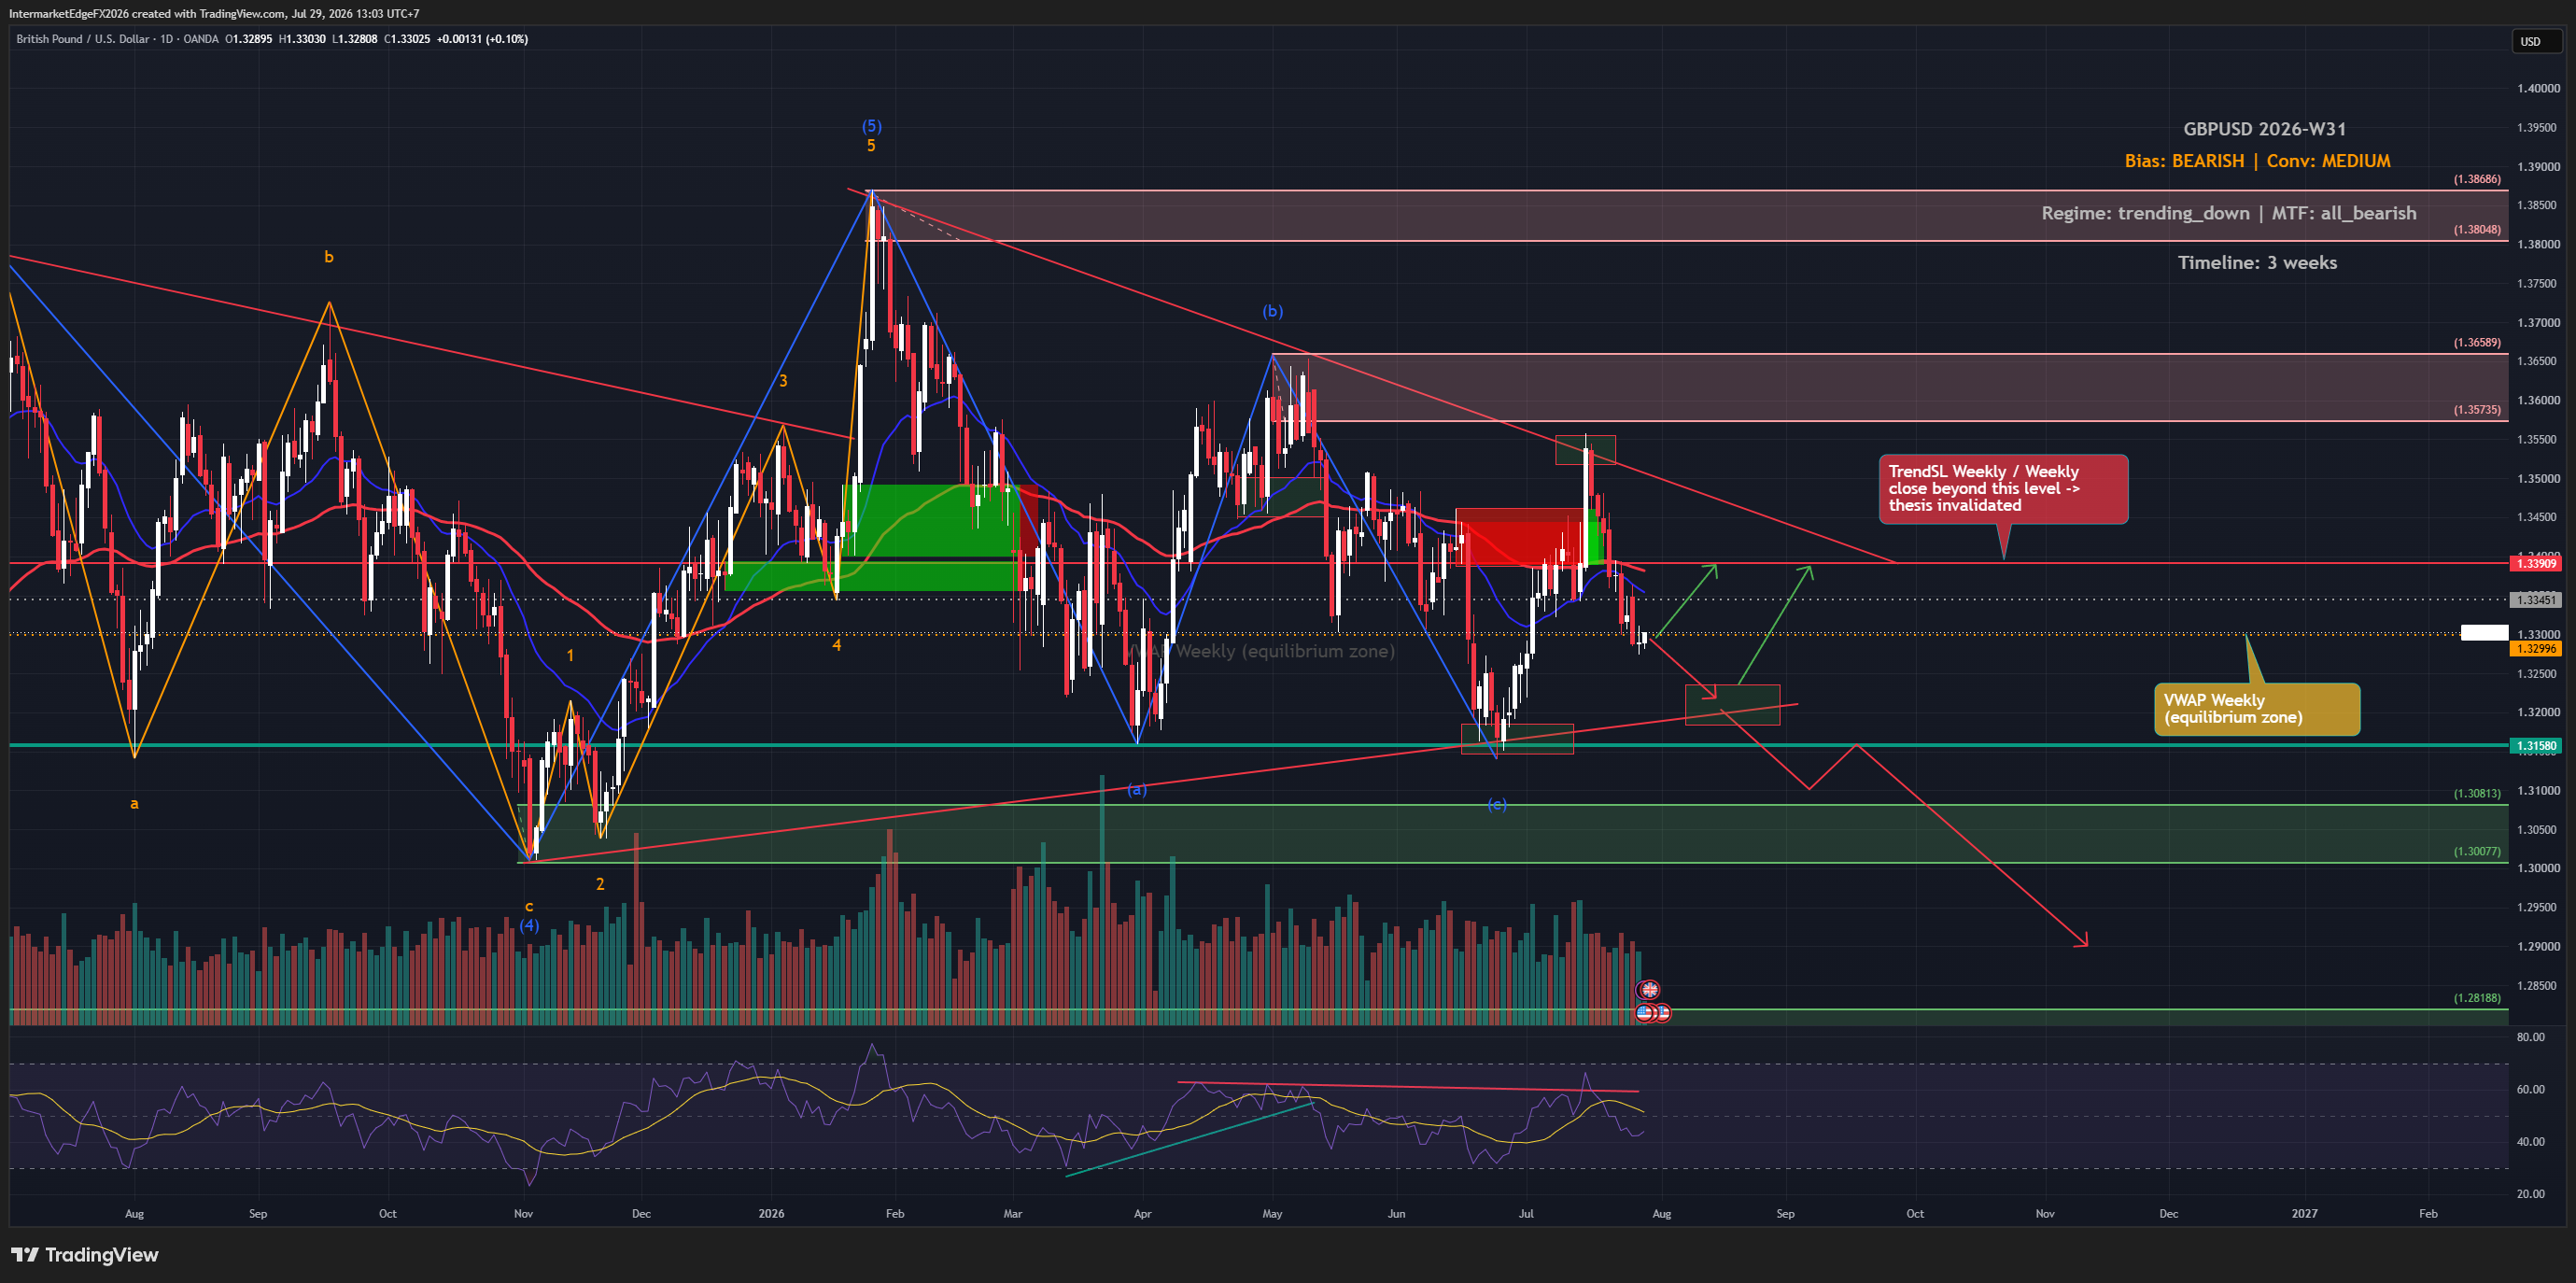
GBPUSD is trading at 1.32988 as of Wednesday, 29 July 2026 at 05:39 UTC, testing from underneath its weekly VWAP at 1.32996, a technically fragile position heading into one of the most catalyst-dense 48-hour windows of the quarter. The Fed decision, BOE rate announcement, UK GDP, and US Core PCE all land within two sessions. With multi-timeframe alignment firmly bearish and the macro rate-differential story still pointing toward USD strength, the setup demands discipline over conviction. The core bearish thesis on GBPUSD rests on a rate-differential argument: the BOE versus Fed policy divergence currently favors USD strength, with the Fed maintaining a restrictive stance anchored by elevated real yields while the Bank of England faces a more ambiguous inflation and growth environment. The Fed hawkish causal chain is the dominant driver here, a tightening bias from the Fed mechanically supports the dollar (USD bullish) and, as the quote currency in GBPUSD, exerts downward pressure on the pair. DXY bullish pressure adds a compounding secondary vector, reinforcing the USD-strength narrative from a broader basket perspective. Multi-timeframe alignment is uniformly bearish, which increases trend-follow confidence when price and structure agree with the macro backdrop. That said, the conviction level here is medium, not high, and the reason matters: there is a genuine signal conflict that traders should not dismiss. Both price action and COT positioning (directional survey data, note the brief does not specify report week, net-position figures, or release date, so this should be read as indicative rather than a precise citable statistic) are reading bullish. This means you have institutional-grade positioning and near-term price momentum potentially working against the bearish macro thesis. The practical implication is clear: this is not a setup to chase aggressively. -- Intermarket Edge

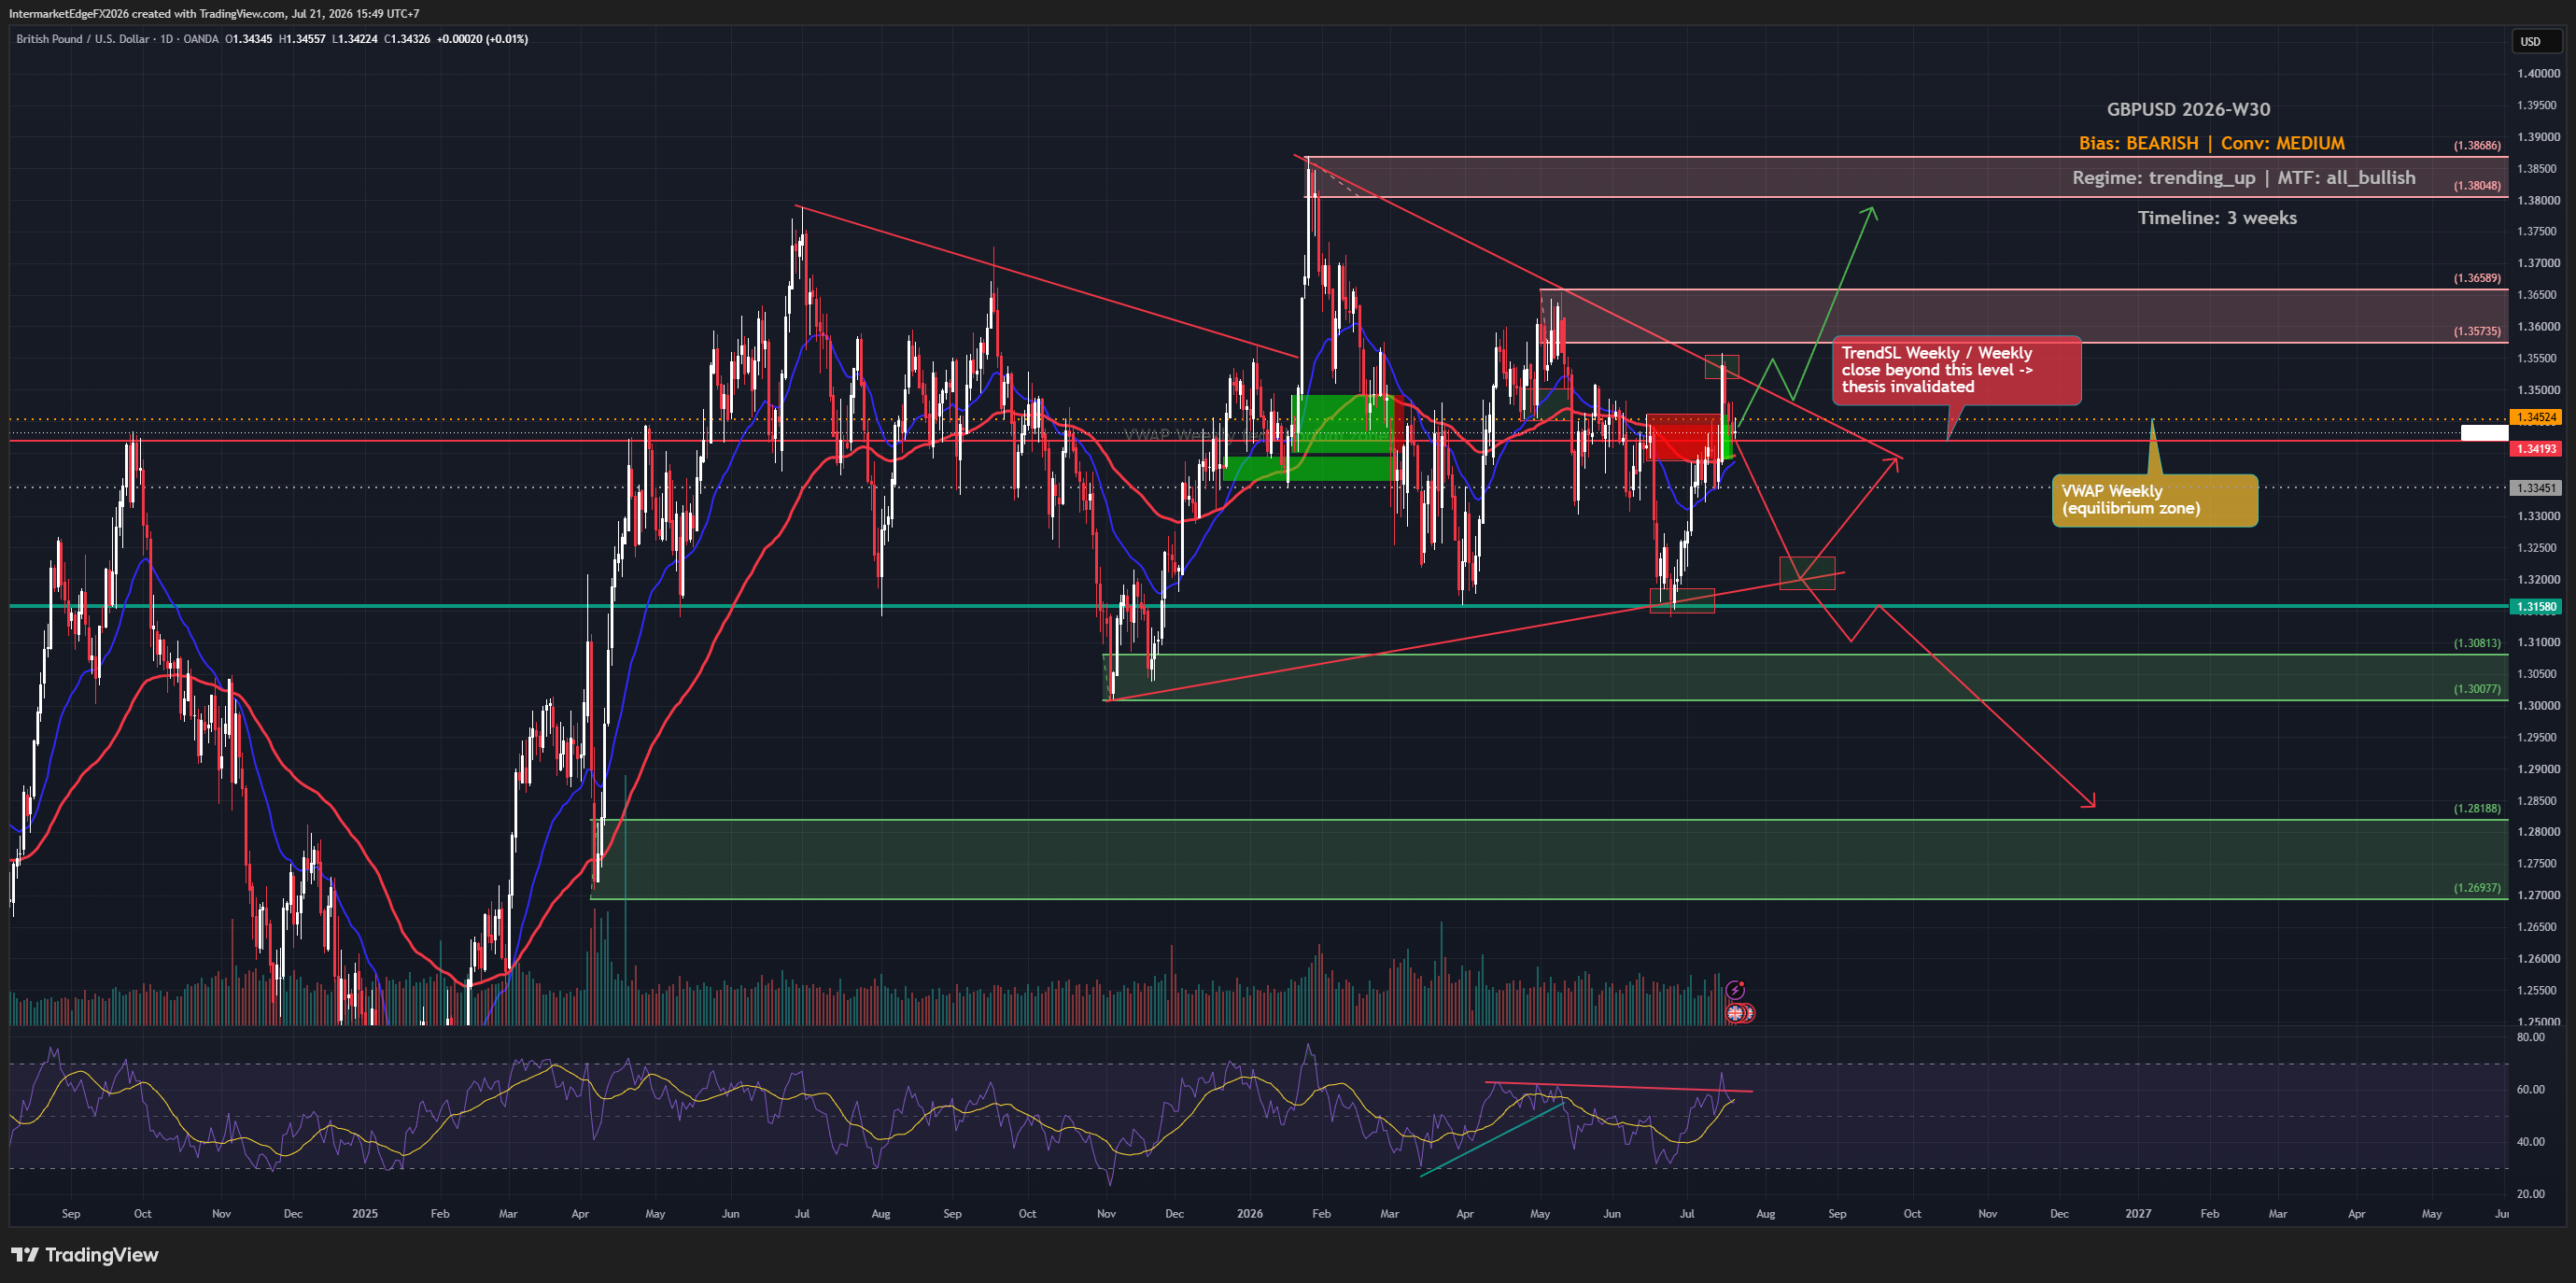
GBPUSD Week W30-2026: Burnham Takes Power and Core CPI Prints Zero, But Price Holds at VWAP 1.3452 as Bull Technicals Clash With a Bearish Macro Case

GBPUSD Week W30-2026: Burnham Takes Power and Core CPI Prints Zero, But Price Holds at VWAP 1.3452 as Bull Technicals Clash With a Bearish Macro Case

Sterling is caught in a genuine tug-of-war this week. Andy Burnham's move into Downing Street triggered volatile, mixed reactions in GBP — markets are questioning fiscal credibility under the new government, and the appointment of John Healey as Chancellor is reshaping spending expectations. Gilt yields rose and sterling dipped on those concerns, a classic political risk premium repricing. On the USD side, escalating US-Iran tensions and a spike in Brent crude are providing a competing safe-haven bid for the dollar, adding to the bearish GBPUSD case via the BOE vs Fed rate differential — US real yields at 2.35% remain a structural headwind for GBP. However, the core signal conflict here is real and cannot be papered over: price, COT positioning, and the technical structure (Daily, Weekly, Monthly all bullish) are aligned against the macro bearish thesis. Price is sitting exactly at VWAP weekly (1.3452) and above TrendSL weekly (1.3419) — both thesis-break levels are untested. A weekly close above 1.3419 formally invalidates bearish structure. The US Core CPI miss (actual 0.0 vs 0.2 forecast) also complicates the 'Fed stays hawkish' narrative and is a partial offset to USD strength. A TGA drain adds further USD headwind. Bottom line: macro and political forces lean bearish, but technical alignment and a crowded short setup (COT bullish at +0.80) create meaningful reversal risk. Conviction is medium. Size conservatively and watch weekly closes relative to 1.3419 and 1.3452 before committing directionally. -- Intermarket Edge

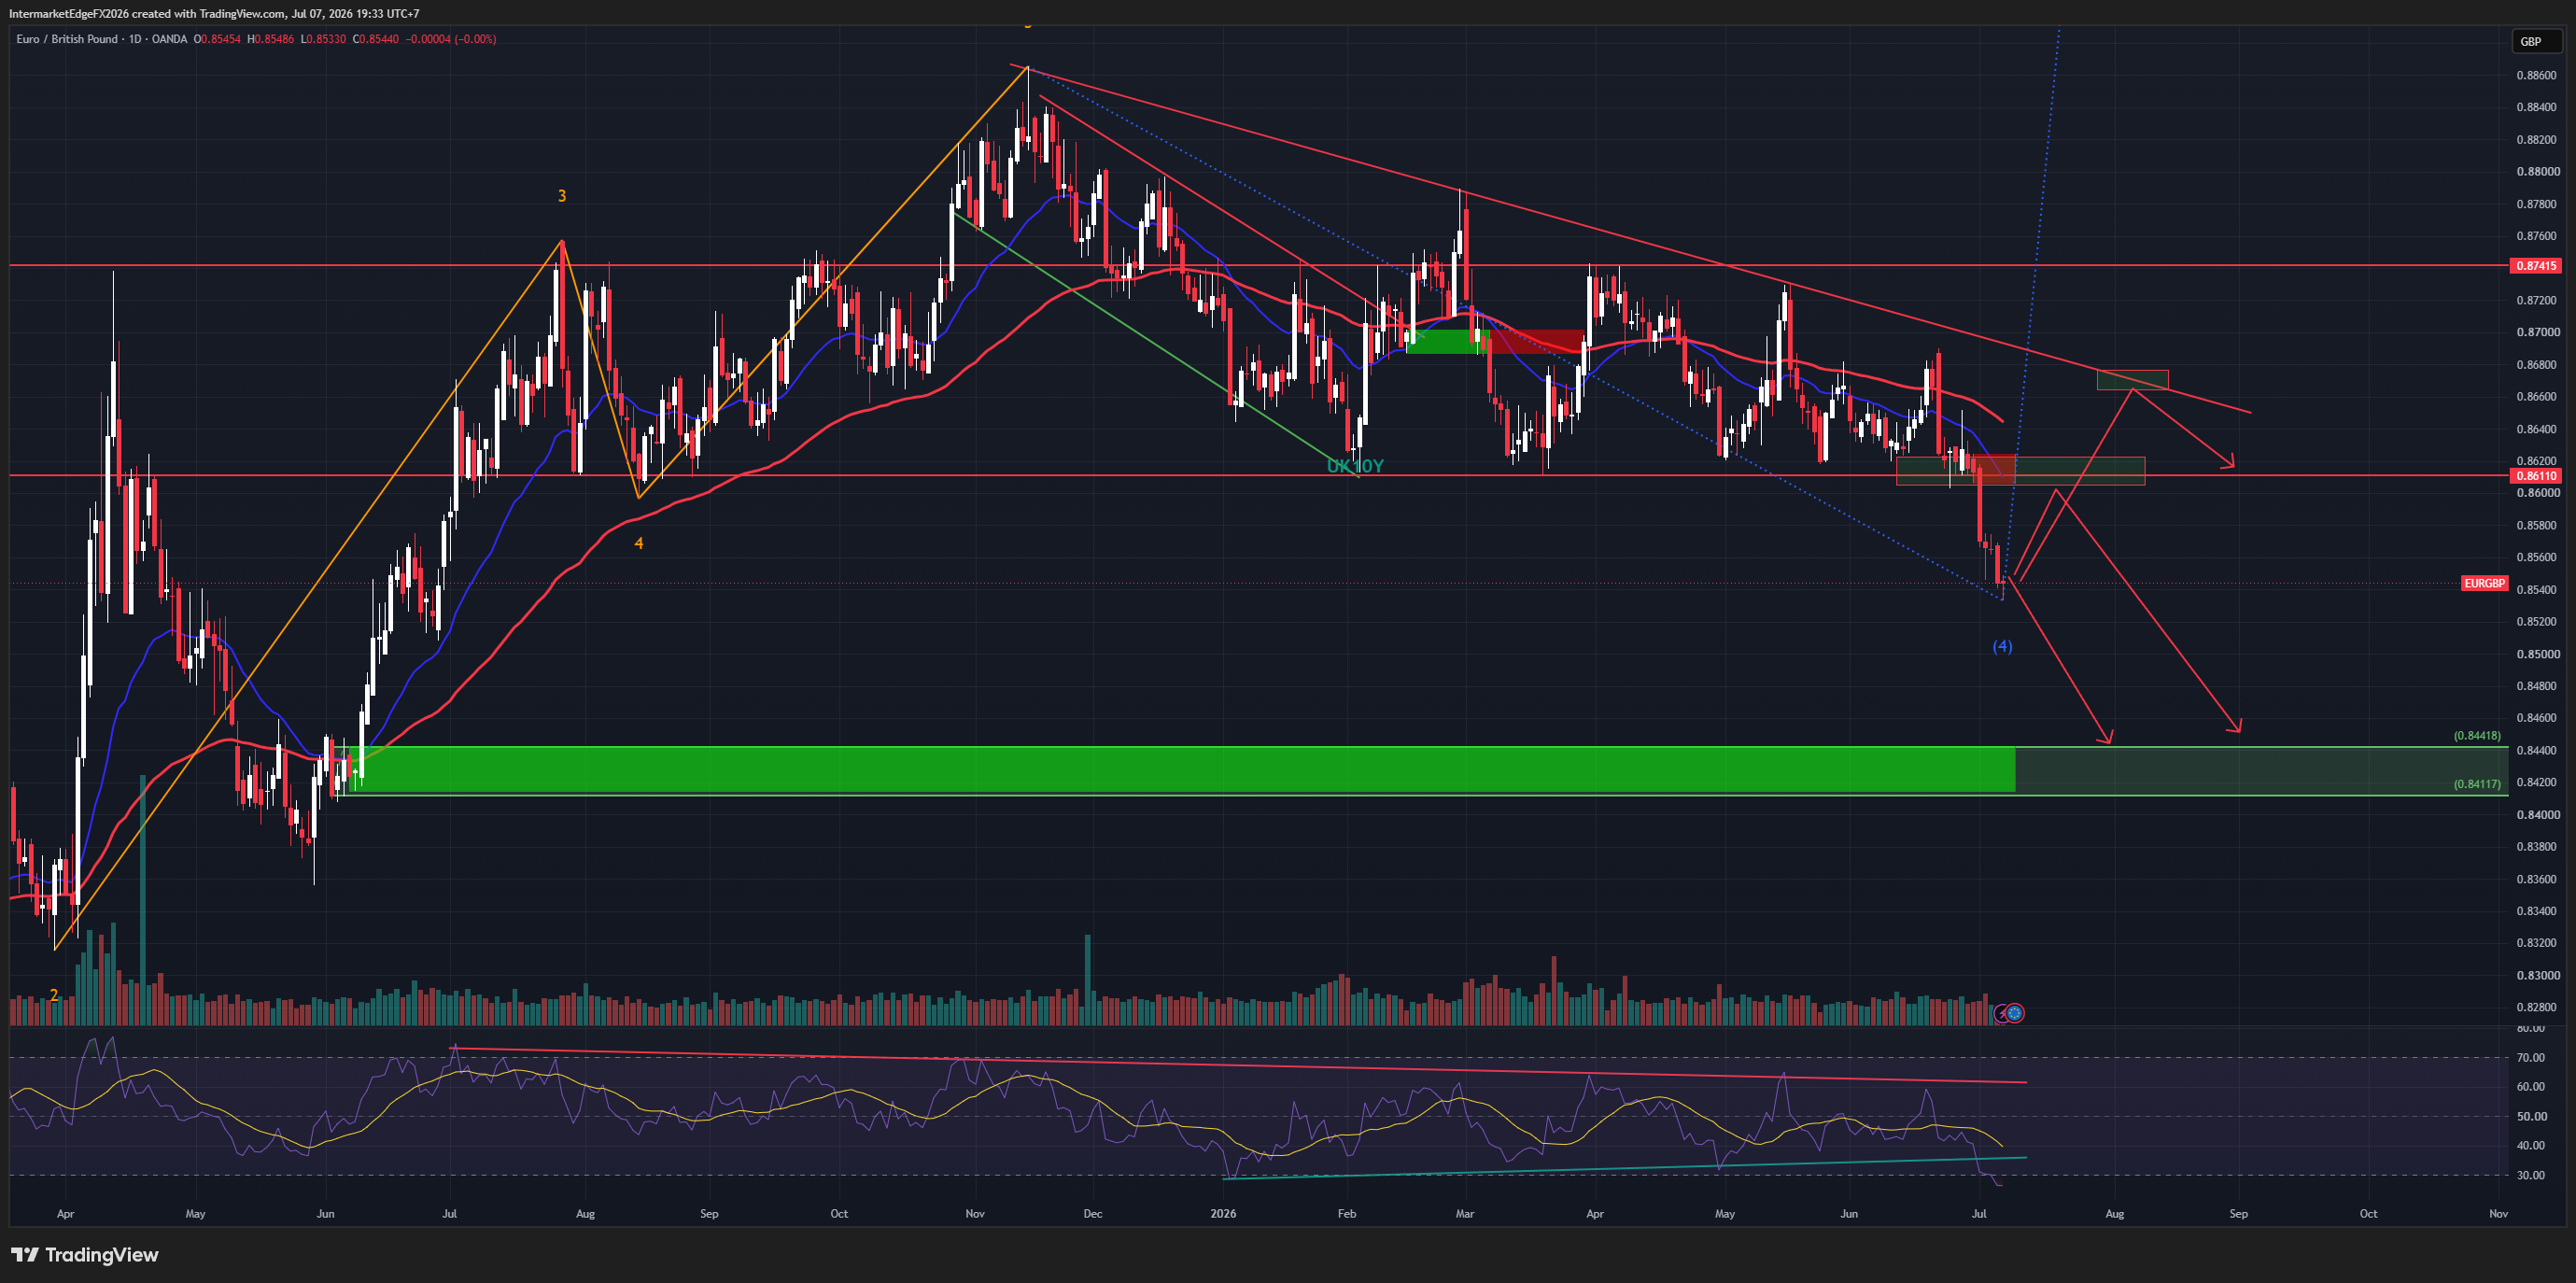
EURGBP - The -1.84% DE-GB Spread Remains the Main Drag, Price Tests a Wave (4) Zone Near 0.8544 Ahead of 0.841-0.846

EURGBP - The -1.84% DE-GB Spread Remains the Main Drag, Price Tests a Wave (4) Zone Near 0.8544 Ahead of 0.841-0.846

EURGBP - SUMMARY 07/07/2026 Regime: The -1.84% DE-GB spread unchanged from last week, still the main drag. Medium Bear (carry). Price tests a local low zone (wave 4) near 0.8540-0.8556 after a long decline from the 0.888 peak. Bias: Medium Bear (carry), unchanged from last week. New factors: sterling posted its best weekly gain in 12 weeks vs the dollar, reportedly easing political risk (details unconfirmed), reinforcing sterling's relative strength vs the euro. ECB's Wunsch made a more hawkish remark than expected but it's individual, not policy. Data corrections: DE10Y 2.96% (not 2.99%); UK10Y 4.80% (not 4.50%); ECB neutral hold 2.00% (not cutting cycle 2.50%). D1 structure: large peak at 0.888, decline breaking 0.874, 0.870, 0.8611, now testing wave (4) at 0.8540-0.8556. Target: 0.841-0.846. Invalidation above 0.870. Scenarios: continued decline toward 0.841-0.846 (45%); range 0.850-0.861 pending confirmation (35%); bounce above 0.861 testing 0.870 (15%); decisive break above 0.870 invalidating thesis (5%). For informational purposes only, not investment advice.

Stay in the loop

Get notified about new research, macro insights, and market analysis.

InterMarketEdge

© 2026 InterMarketEdge. Financial intelligence for inter-market traders.