Tag: BoE — InterMarketEdge

Tag: BoE

EURGBP W43: Sterling Support Meets an Unresolved Price Conflict

EURGBP W43: Sterling Support Meets an Unresolved Price Conflict

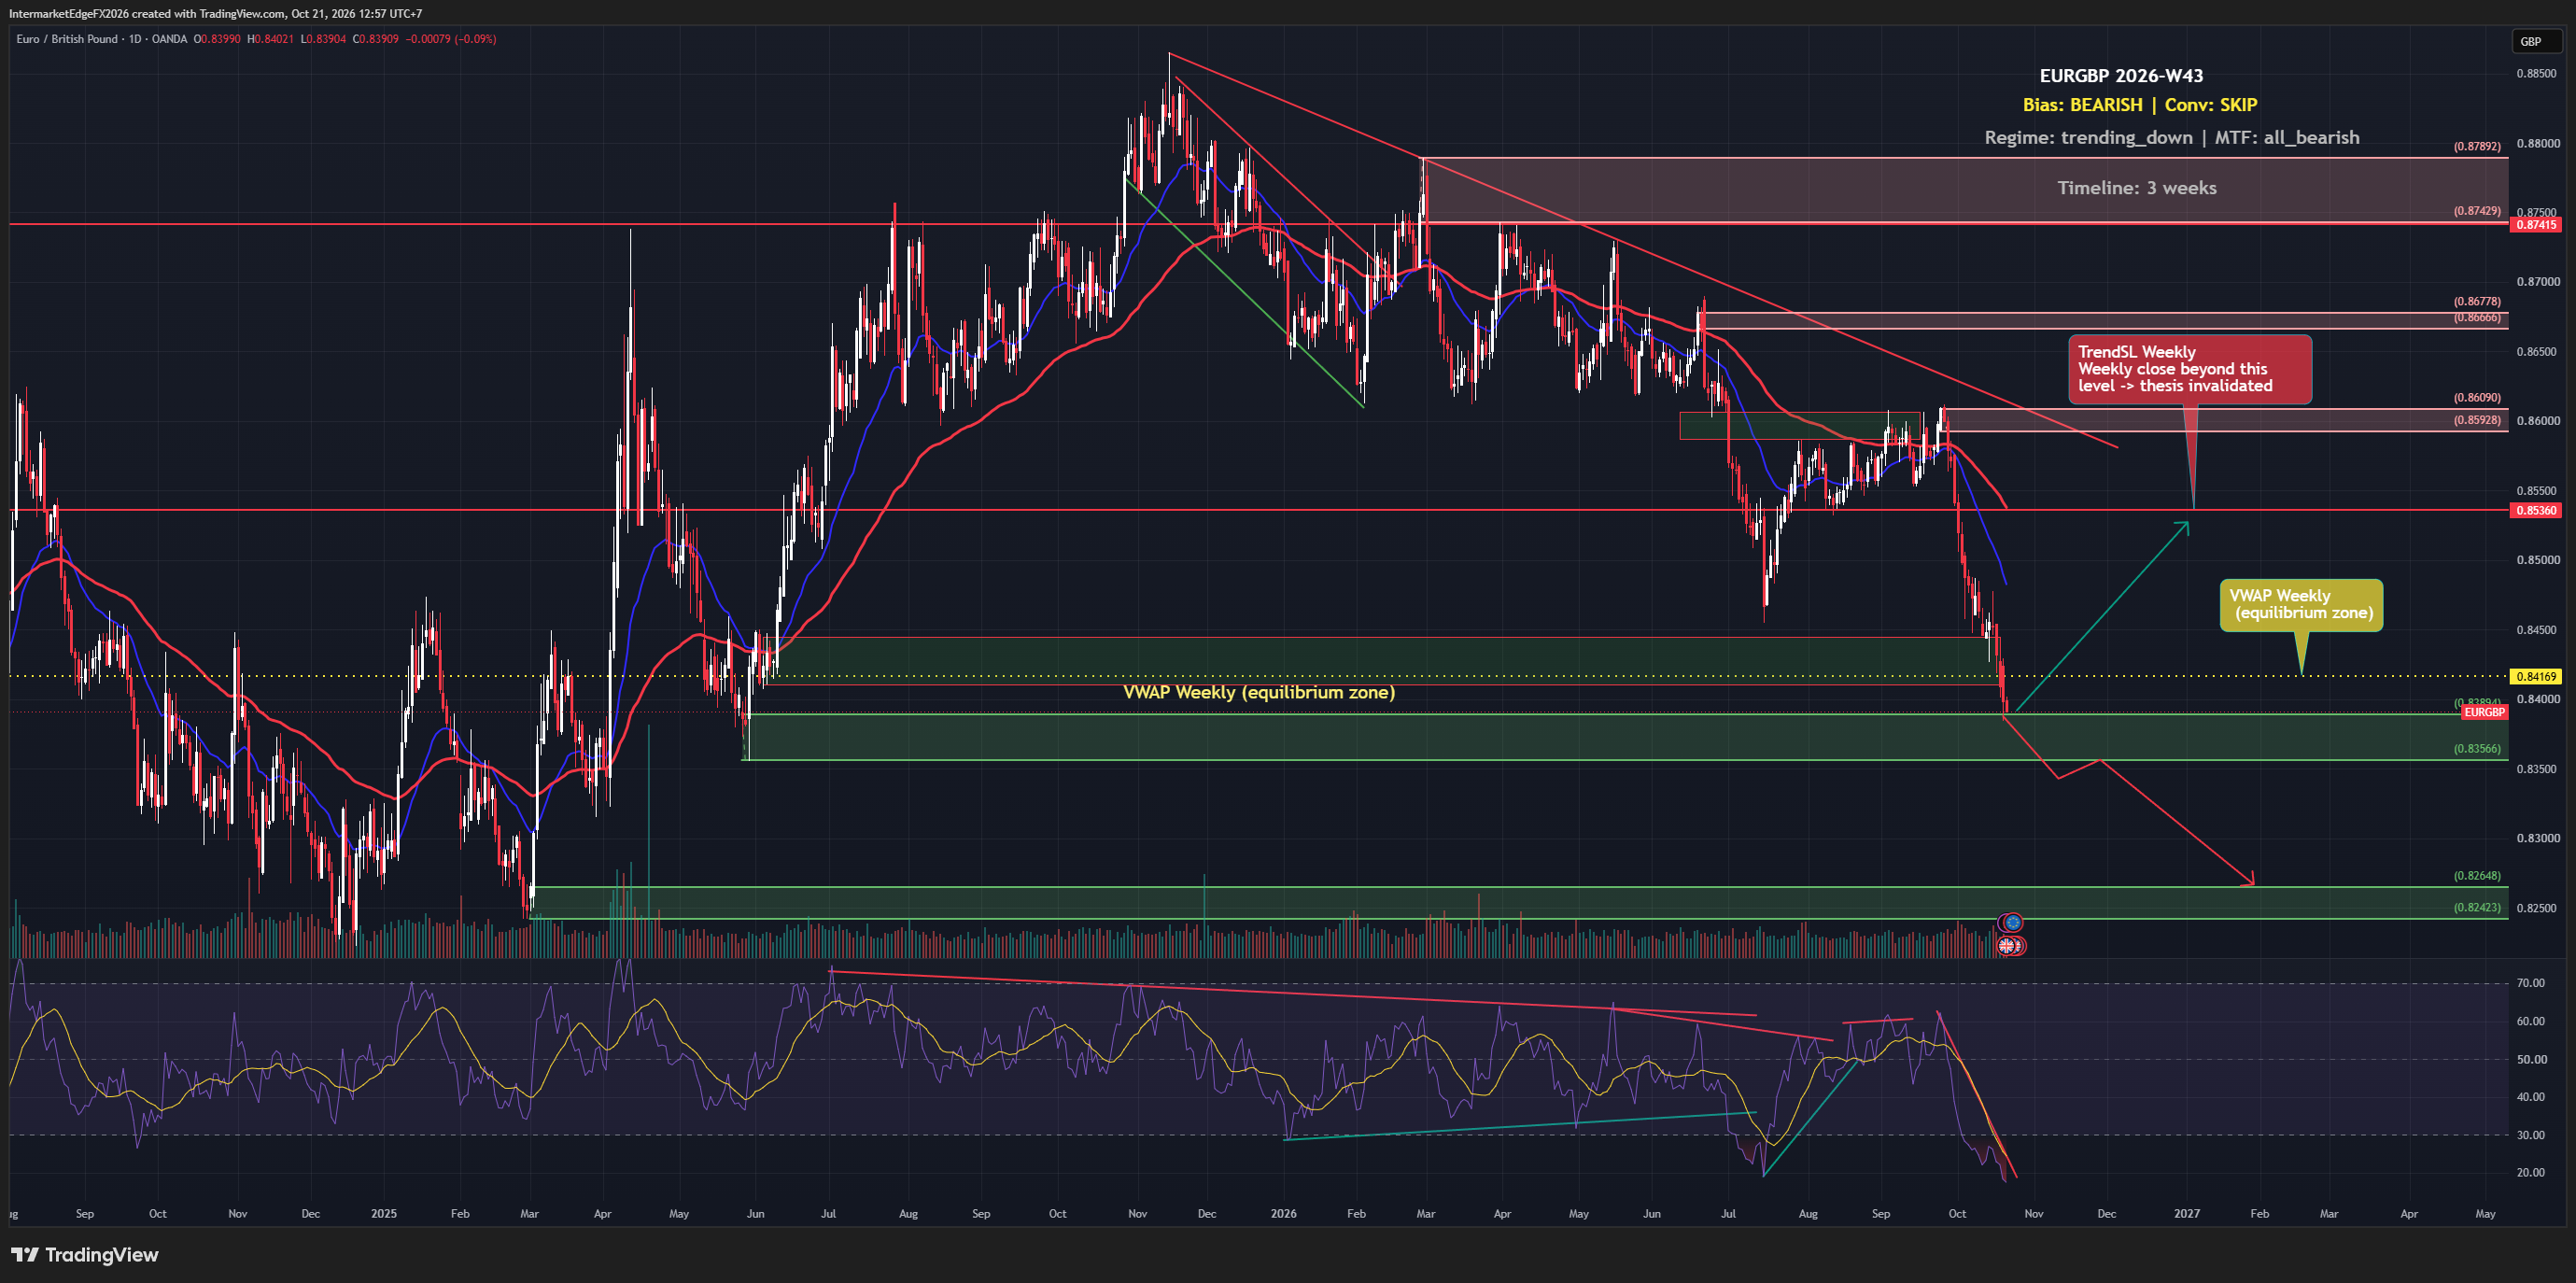
EURGBP W43: bearish three-week view; stand aside. Downward trends coexist with bullish price action. At 05:38 UTC on Wednesday, 21 October 2026, EURGBP was 0.83944, below weekly VWAP 0.84169 and below weekly TrendSL 0.85360. Source: mt5:EURGBP.sml:1m. This is a dated observation, not a live quote. Both risk conditions remain pending in this observation. If price sustains above weekly VWAP 0.84169, momentum would run against the bearish view and short exposure would warrant reduced size. A weekly close above TrendSL 0.85360 would invalidate the bearish structure: exit shorts and reassess. The momentum watch has no added daily or weekly closing requirement. FXSSI: 72% long / 28% short, collected 21 October at 05:38:28 UTC. Broker sample, provider observation time unverified; contrarian context, not an independent sell signal. COT CFTC TFF, Leveraged Funds, report date 2026-10-13: EUR 099741 net short 68,001, net change -23,740; GBP 096742 net long 10,313, change -2,119 contracts versus 6 October. Separate futures components, not direct EURGBP positions; release dates unverified. This is a pre-CPI assessment. ONS scheduled UK September CPI for 21 October at 06:00 UTC. No actual outcome is included. Hotter UK inflation could support GBP if relative rate expectations rise; softer inflation could support a recovery in EURGBP. Check price and relative yields after the release. Intermarket Edge | Institutional Macro & Intermarket Analysis For informational and educational purposes only. Not financial advice.
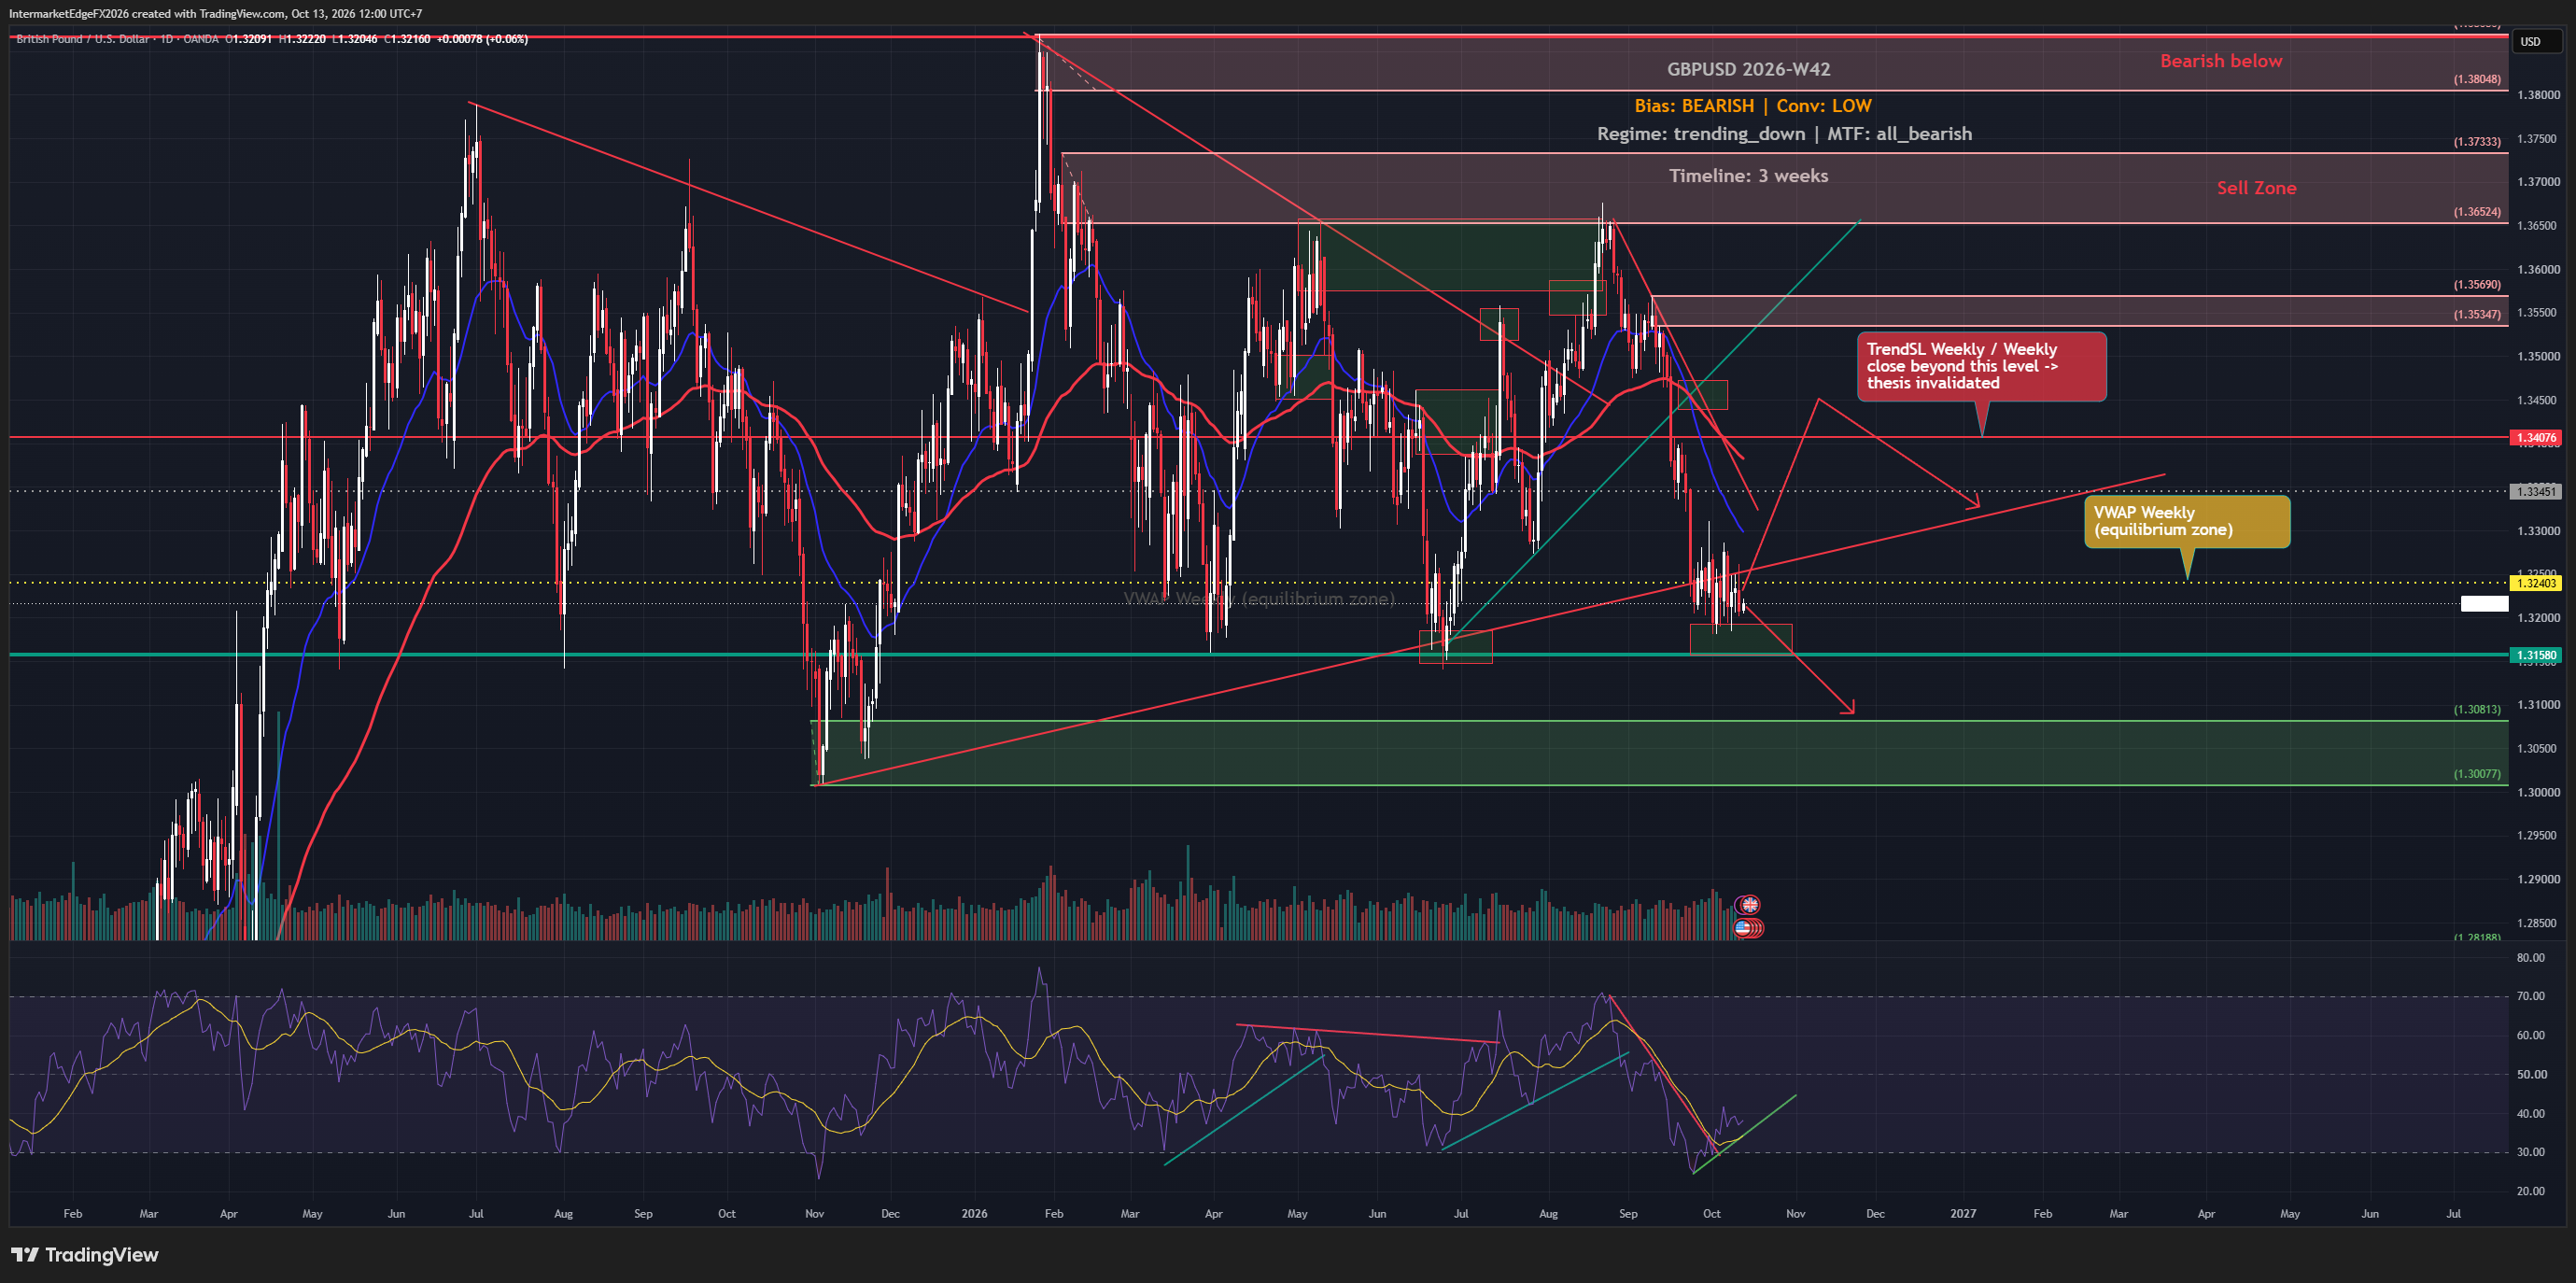
GBPUSD W43: Sterling Resilience Challenges the Bearish View

GBPUSD W43: Sterling Resilience Challenges the Bearish View

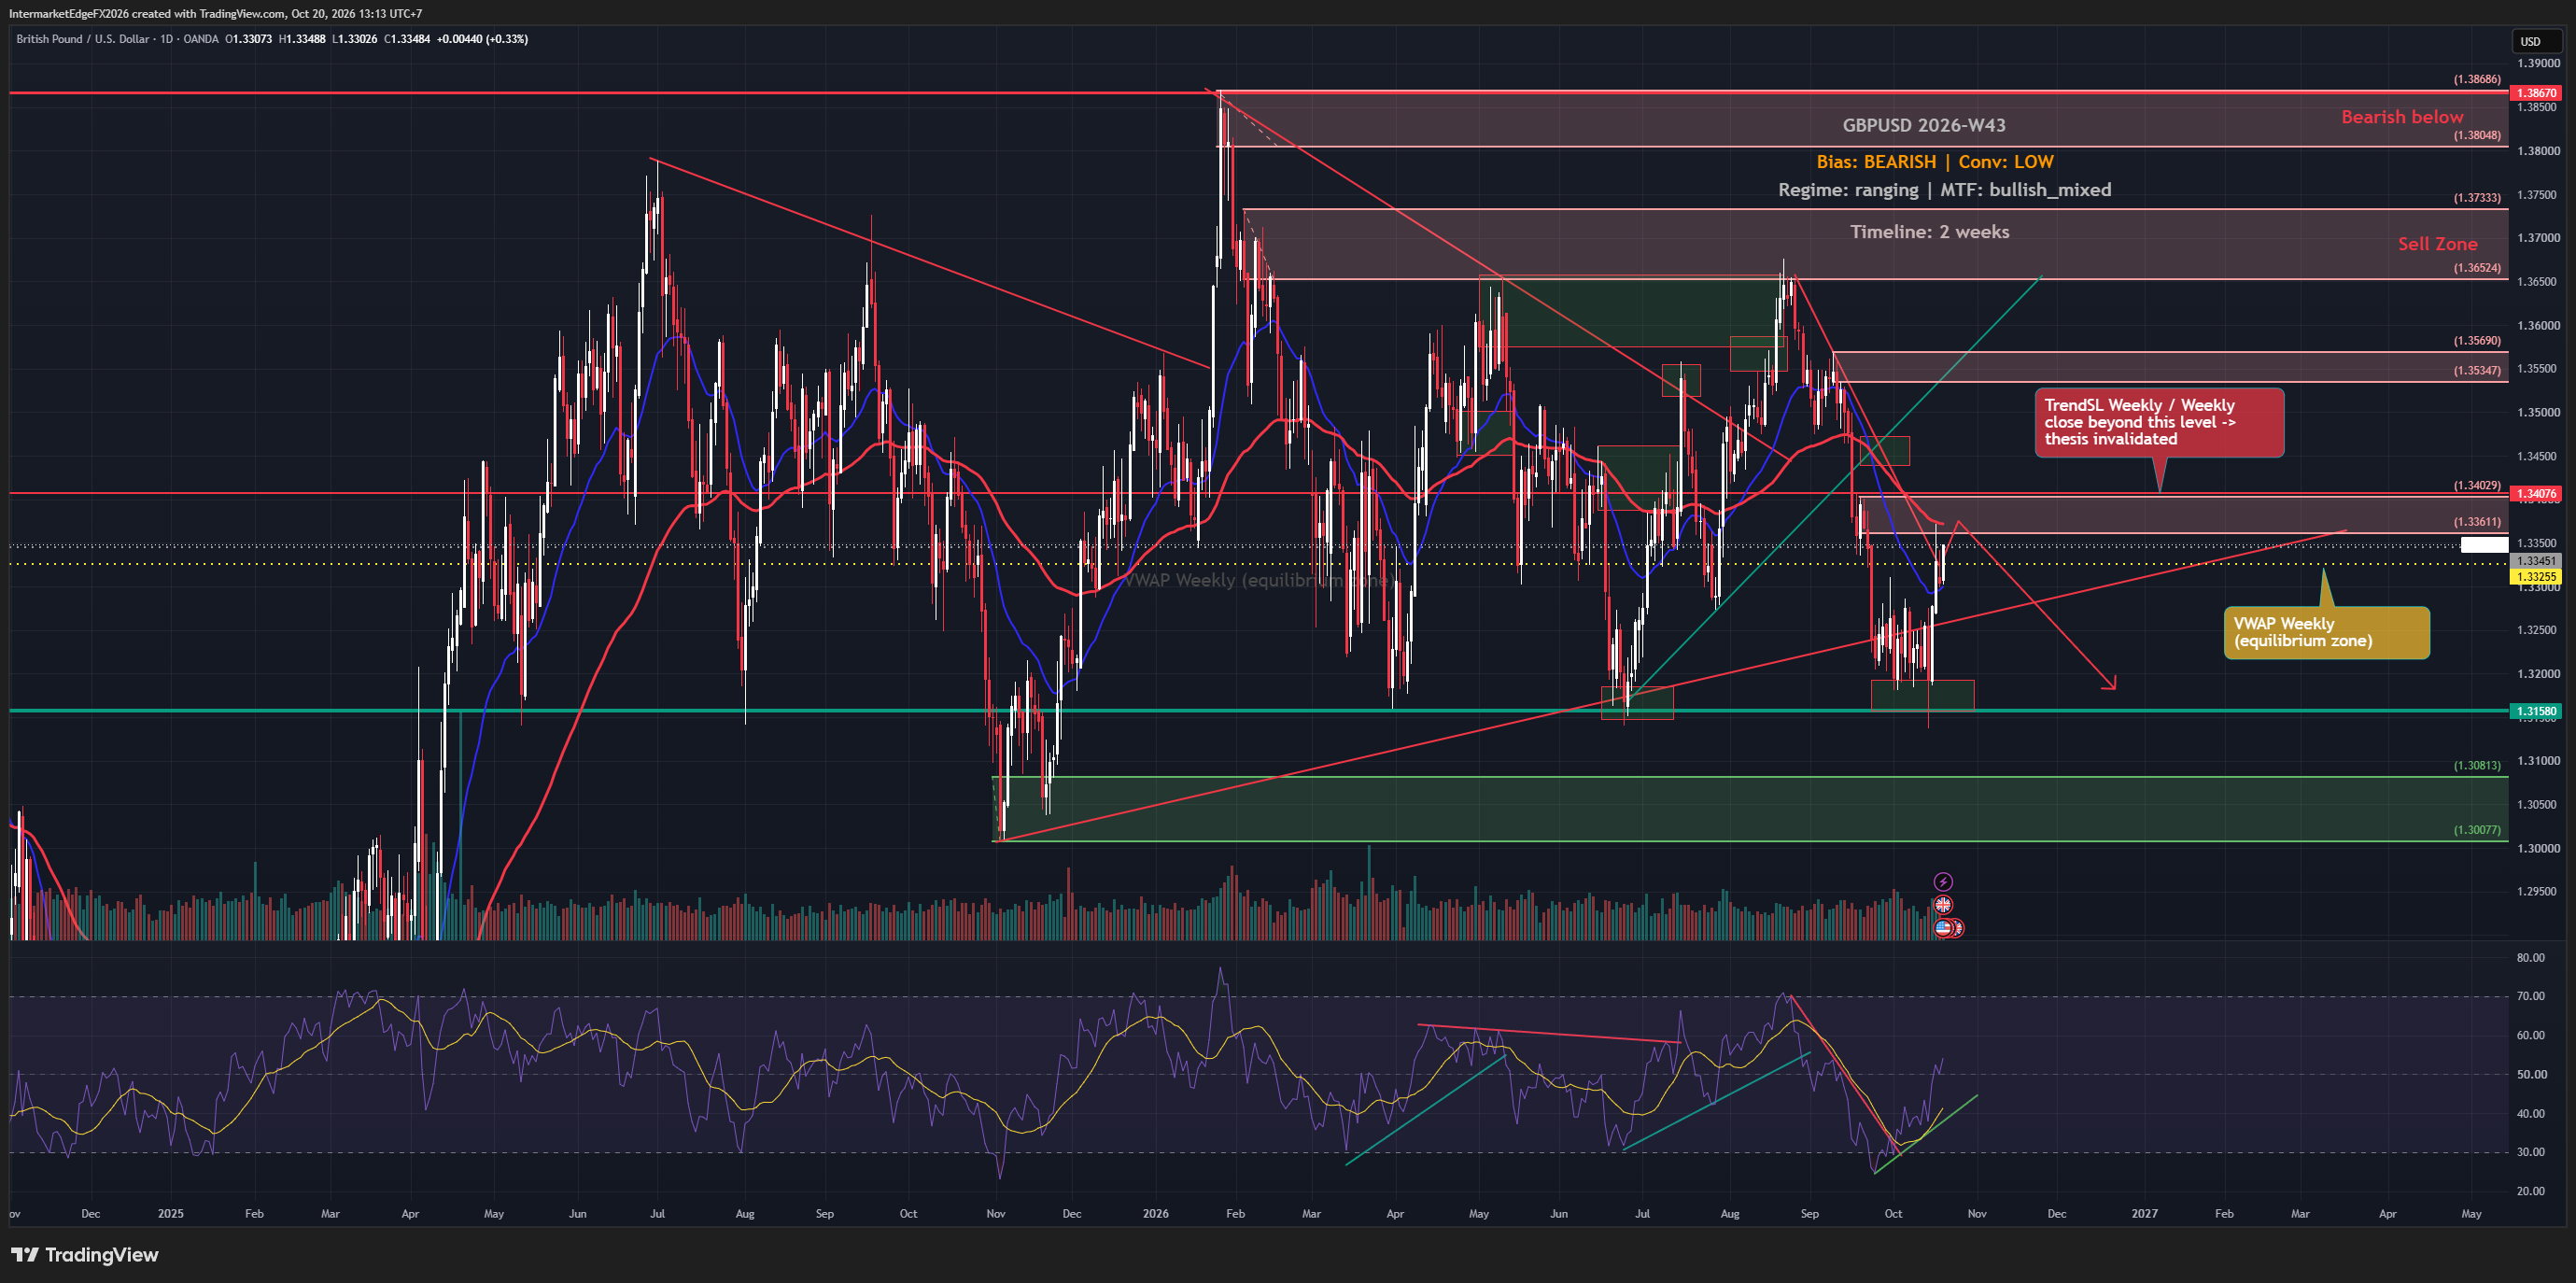
GBPUSD W43: bearish, low confidence; two-week horizon, ranging conditions and mixed bullish signals. At 05:55 UTC on 20 October 2026, GBPUSD was 1.33273, above weekly VWAP 1.33255 and below weekly TrendSL 1.34076. Source: mt5:GBPUSD.sml:1m. This is a dated observation, not a live quote. The momentum warning is already active: existing shorts warrant reduced size now. Structural invalidation remains pending: a weekly close above TrendSL 1.34076 would invalidate the bearish structure; exit shorts and reassess if that condition occurs. The weekly closing rule applies to structural invalidation, not to the momentum warning. FXSSI: 52% long / 48% short, collected at 05:54:49 UTC on 20 October. The four-percentage-point imbalance is small and provides no contrarian lean under the framework. This is a broker sample, not the entire FX market; collection time is not a separately verified provider timestamp. COT CFTC 096742, Leveraged Funds, futures only, report date 2026-10-13: net long 10,313 contracts, down 2,119 from 6 October. Lagged positioning; publication date unverified. Falling net length is not net short. Sterling strength against EUR does not establish strength against USD. The UK growth surprise is a counterweight to the bearish view; comparable UK yields are needed to verify a UK-US rate advantage. UK CPI is listed for 21 October by ForexFactory, not independently confirmed against an official calendar here. New exposure can wait for clearer agreement. Intermarket Edge | Institutional Macro & Intermarket Analysis For informational and educational purposes only. Not financial advice.
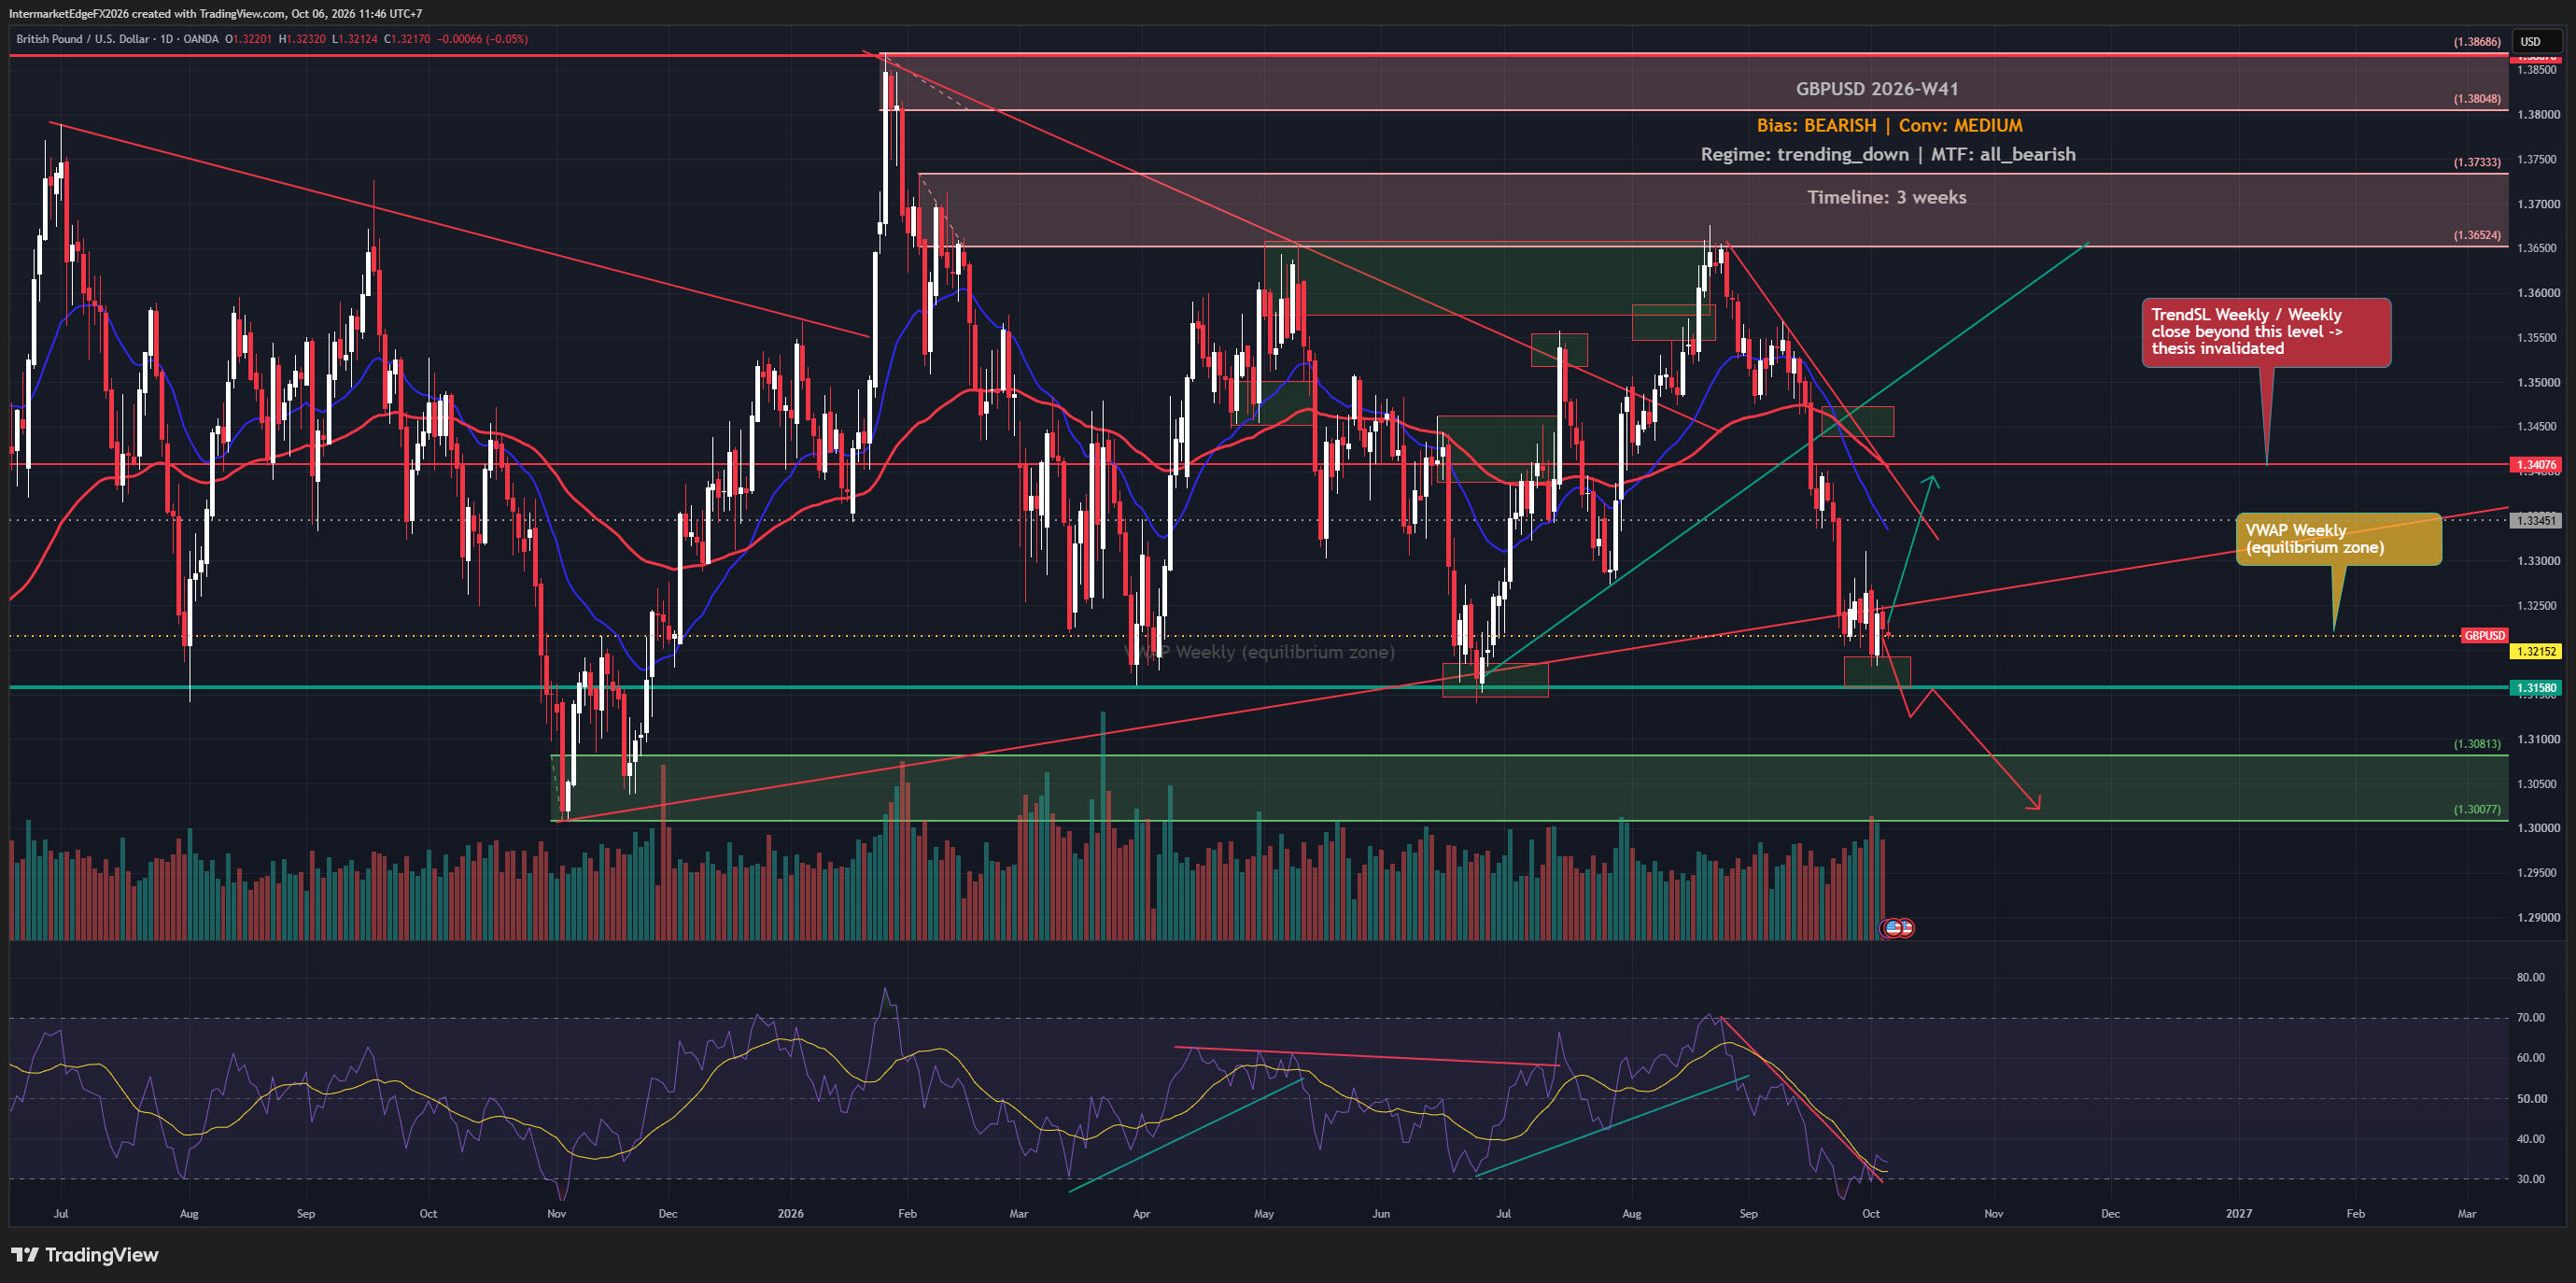
GBPUSD W42: A Bearish Trend Meets a Policy Test

GBPUSD W42: A Bearish Trend Meets a Policy Test

GBPUSD W42: bearish three-week view, low confidence. At 13/10/2026 05:01 UTC, GBPUSD was 1.32168, below weekly VWAP 1.32403 and below weekly TrendSL 1.34076. Source: mt5:GBPUSD.sml:1m, a timestamped broker quote. If price sustains above 1.32403, the momentum warning against the bearish thesis would activate and call for reducing risk. This condition remains pending; it does not require a weekly close. A completed weekly close above 1.34076 would invalidate the bearish structure, requiring an exit from the bearish thesis and reassessment. This condition remains pending. Greene's inflation concerns could support GBP if UK rate expectations rise relative to US expectations. Watch DXY and comparable UK-US yields rather than assuming a spread from US data alone. ForexFactory lists US CPI on 14 October and UK GDP plus US retail sales/PPI on 15 October; this is a secondary calendar source. Wait for the data response before assessing new entries. --- Intermarket Edge | Institutional Macro & Intermarket Analysis For informational and educational purposes only. Not financial advice.
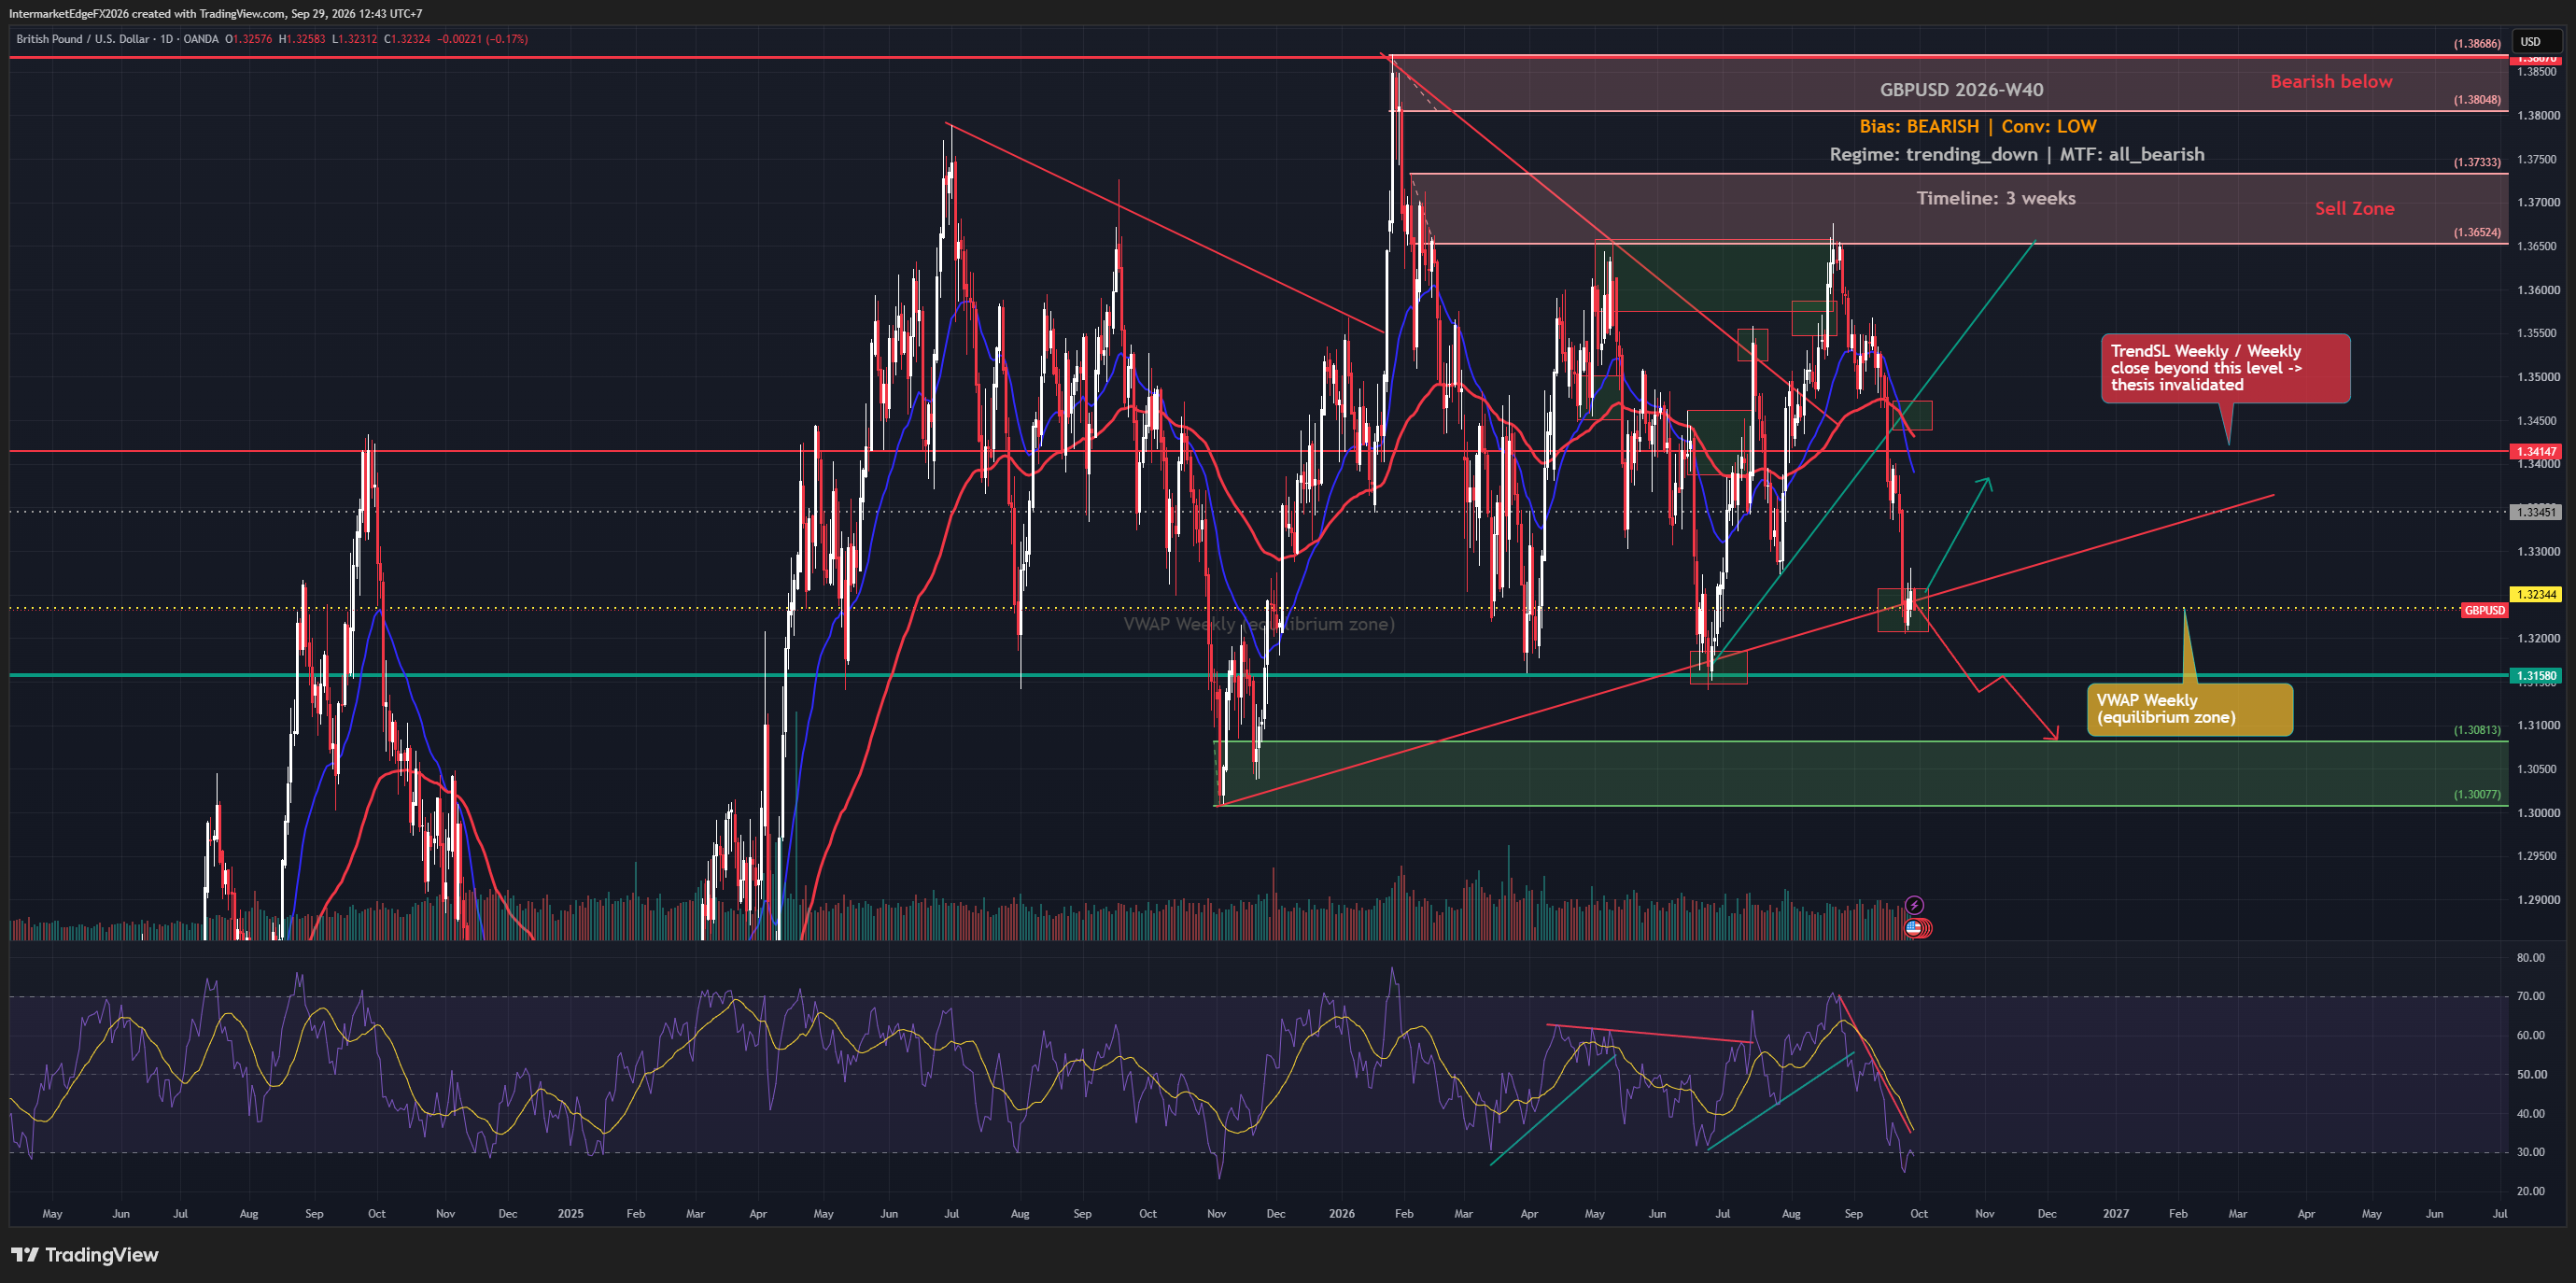
GBPUSD W41: Sterling Outperforms the Euro, but the Dollar Test Remains

GBPUSD W41: Sterling Outperforms the Euro, but the Dollar Test Remains

GBPUSD W41 | A bearish structure with an active momentum warning Sterling strength against the euro does not establish strength against USD. Amundi's more favorable GBP view also came alongside a positive dollar view. At 04:36 UTC on 06 October 2026, GBPUSD was 1.3228 (MT5 GBPUSD.sml:1m). Price is already above weekly VWAP 1.32152; the warning against bearish momentum is active now. Price is below weekly TrendSL 1.34076. Only a completed weekly close above 1.34076 would invalidate the bearish structure. That condition remains pending; an intraday touch is insufficient. The outlook remains bearish with medium conviction over a three-week review horizon. Timing is less clear. Existing shorts warrant a risk review now; a new position can wait for stronger agreement. Compare fresh dollar moves and matching UK-US yield observations rather than inferring the pair's direction from EURGBP alone. ForexFactory lists FOMC minutes for October 7 and Bailey remarks for October 8 on its UTC calendar. These are secondary-source listings, not officially verified schedules. Prices above are dated references, not live quotes. FXSSI collected on October 6 at 04:36:18 UTC: 69% Buy / 31% Sell for GBPUSD. Collection time, not provider observation time. This broker retail sample does not represent the entire FX market and is not a standalone entry signal. Intermarket Edge | Institutional Macro & Intermarket Analysis For informational purposes only. Not financial advice.
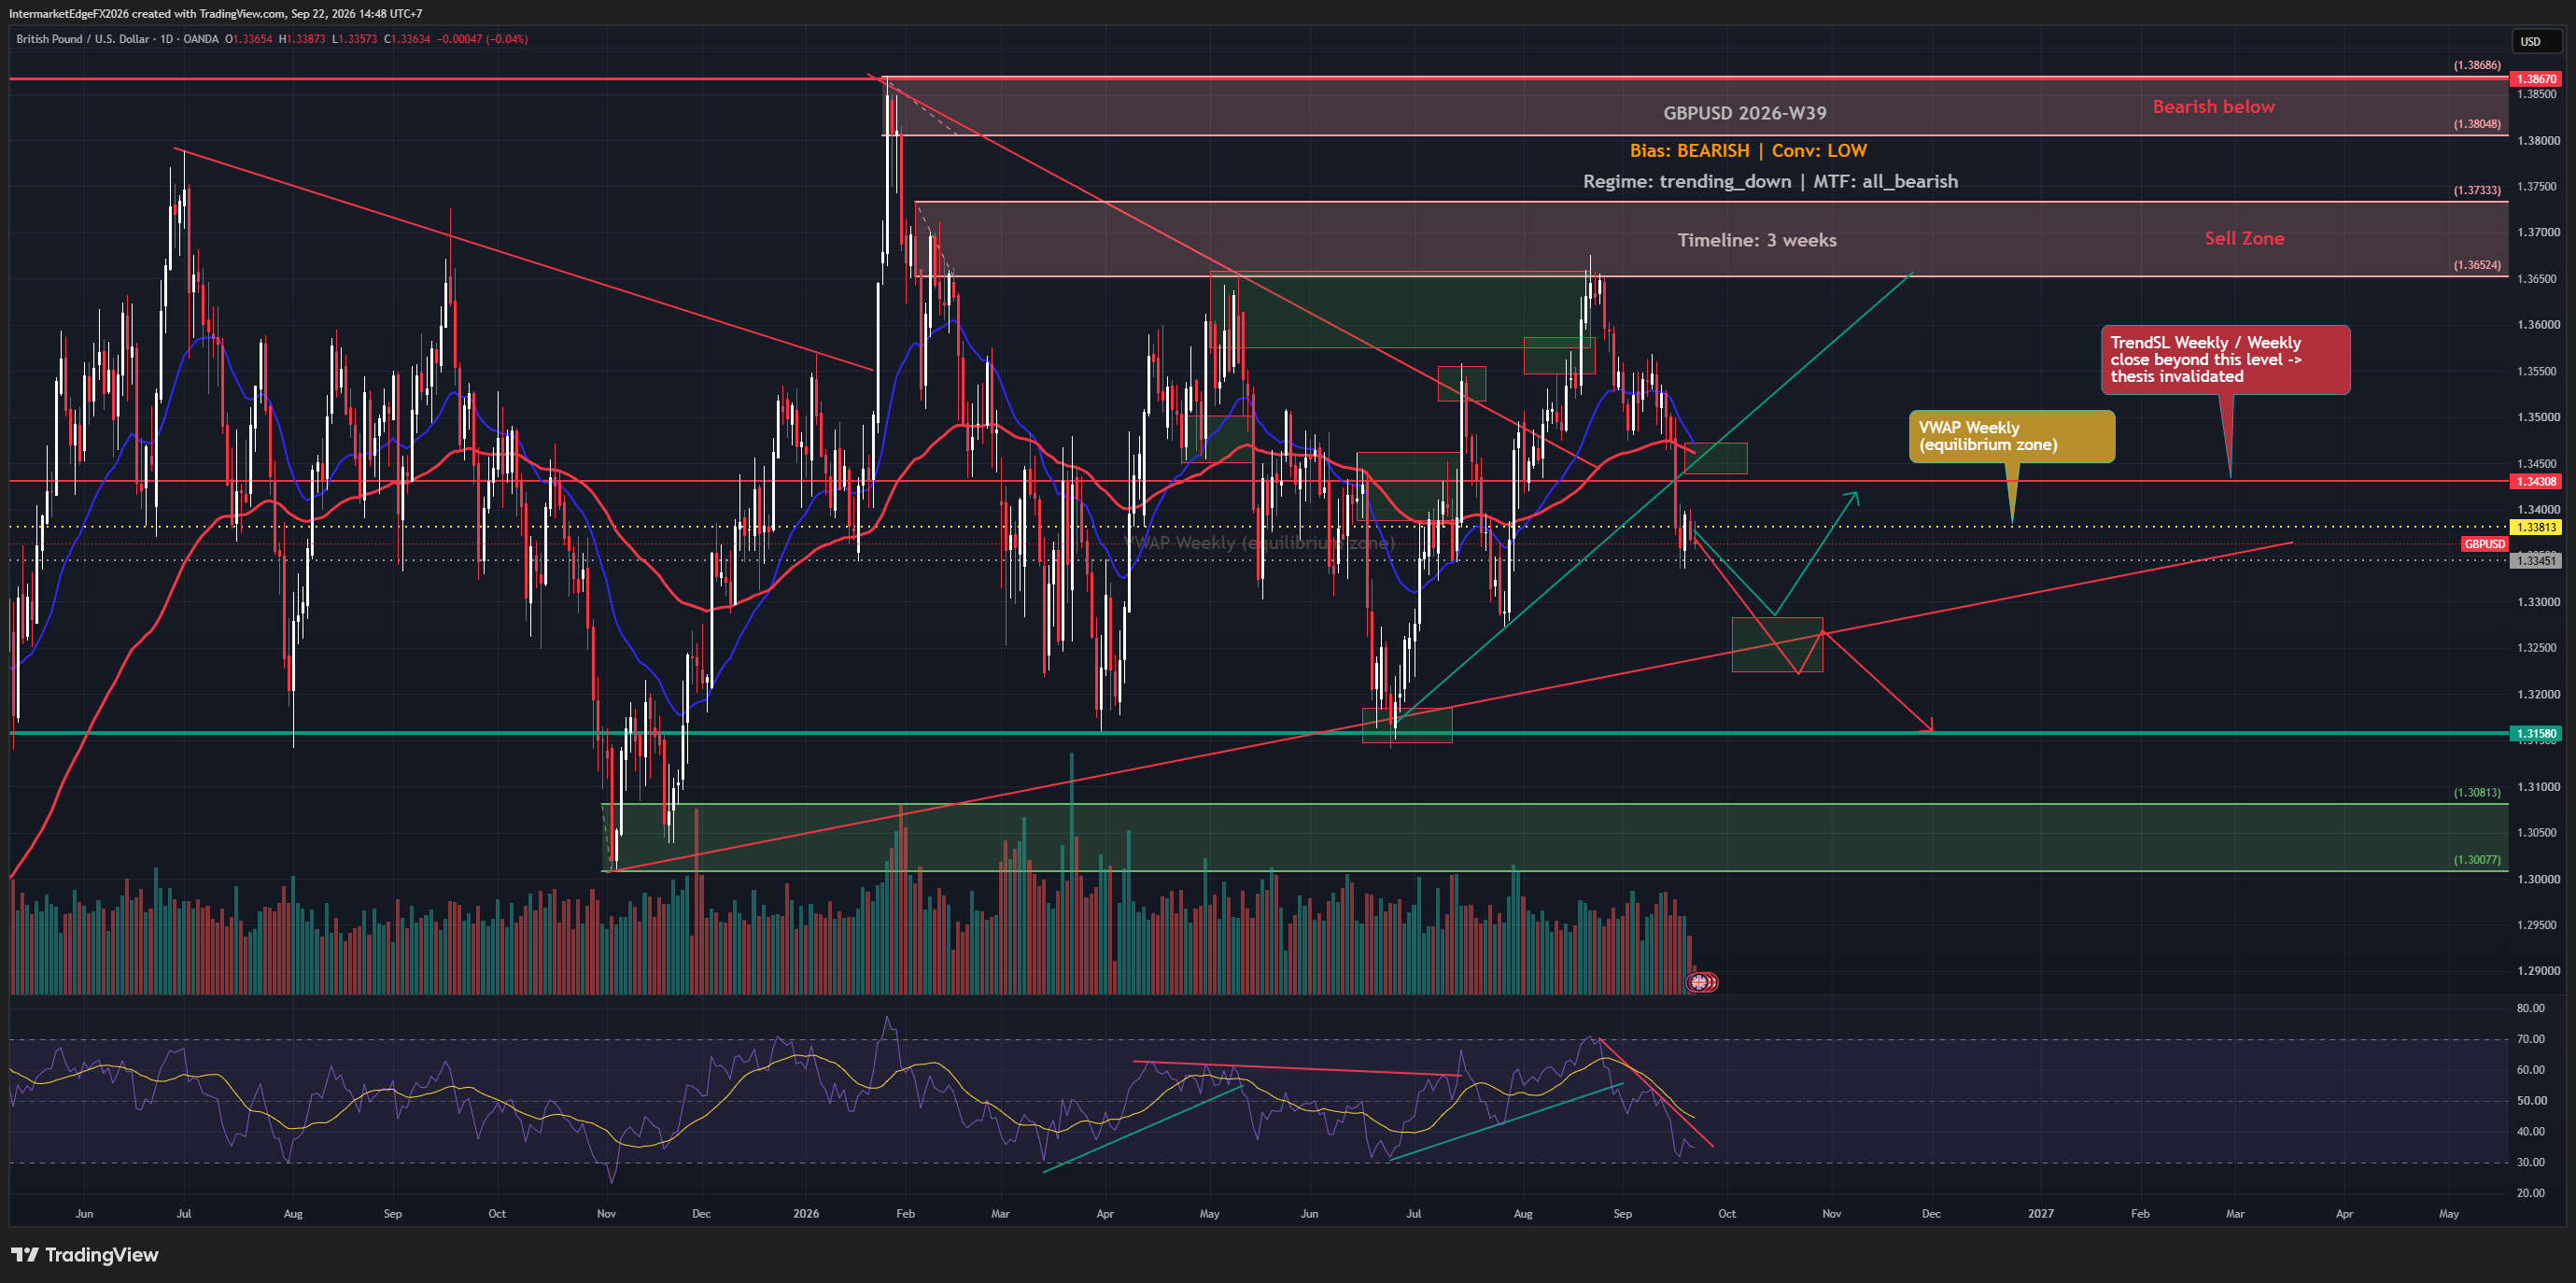
GBPUSD Week W40-2026: Sterling Remains Under Pressure as the BoE Bounce Fades

GBPUSD Week W40-2026: Sterling Remains Under Pressure as the BoE Bounce Fades

GBPUSD is sitting just above its weekly VWAP at 1.32344 as of Tuesday 29 September, close enough to look like support, but the structural current underneath is still running lower. The BoE's Deputy Governor Ramsden flagged upside inflation risks and hinted at a possible rate increase, producing a short-lived sterling rebound. The problem: US real yields at 2.85% are one of the most powerful headwinds the pound can face, and that wall hasn't moved. The structural bias for GBPUSD remains bearish, but this is a low-conviction bearish call, and that distinction matters enormously for how to treat any signal from the current price. The dominant driver is the Fed hawkish causal chain: rising US real yields attract capital toward dollar assets, which strengthens DXY, which in turn presses GBPUSD lower through the rate differential. That chain is active and has clear mechanical weight in the analysis. What makes conviction low rather than high is the internal conflict visible across signal types. Price action itself is registering near-term bullish momentum, the pair is trading above its weekly VWAP at 1.32344 as of Tuesday 29 September, which means short-term momentum is already running against the bearish thesis. That is not a future risk; it is the current reality. The BoE's hawkish shift adds a fundamental reason why sterling might hold or recover near-term, even if the longer-term rate differential remains dollar-positive. Retail positioning, 75% of retail traders net long GBPUSD as of 29 September (FXSSI, broker sample, not the full market), provides contrarian context that leans bearish, but without a calibrated framework it cannot lift conviction on its own. The multi-timeframe structure is aligned bearish from the weekly level down, which keeps the directional bias intact, but the signals that would normally support sizing a position with confidence are not consistently pointing the same way. -- Intermarket Edge

GBPUSD Week W39-2026: Pound Dips Near Seven-Week Lows as Fed-BoE Divergence Tightens the Trap

GBPUSD Week W39-2026: Pound Dips Near Seven-Week Lows as Fed-BoE Divergence Tightens the Trap

Sterling is trading near seven-week lows as the Fed-BoE policy gap favors the dollar, but this is not a clean sell setup. At the Tuesday, 22 September 2026 observation, GBPUSD was already above weekly VWAP at 1.33813 and testing it from above, so short-term momentum was running against the bearish macro thesis. The broader assessment remains bearish because the rate differential and multi-timeframe structure still point lower, but conviction is low and the timing evidence is incomplete. FXSSI reports that 67% of its broker-level retail sample is net long GBPUSD, which provides contrarian context but no calibrated directional signal and no evidence about institutional flows. The decision is to stand aside. A weekly close above TrendSL at 1.34308 would invalidate the bearish structure and require a reassessment. -- Intermarket Edge

GBPUSD Week W38-2026: Yield Pushes Toward 5% but the Dollar Refuses to Confirm

GBPUSD Week W38-2026: Yield Pushes Toward 5% but the Dollar Refuses to Confirm

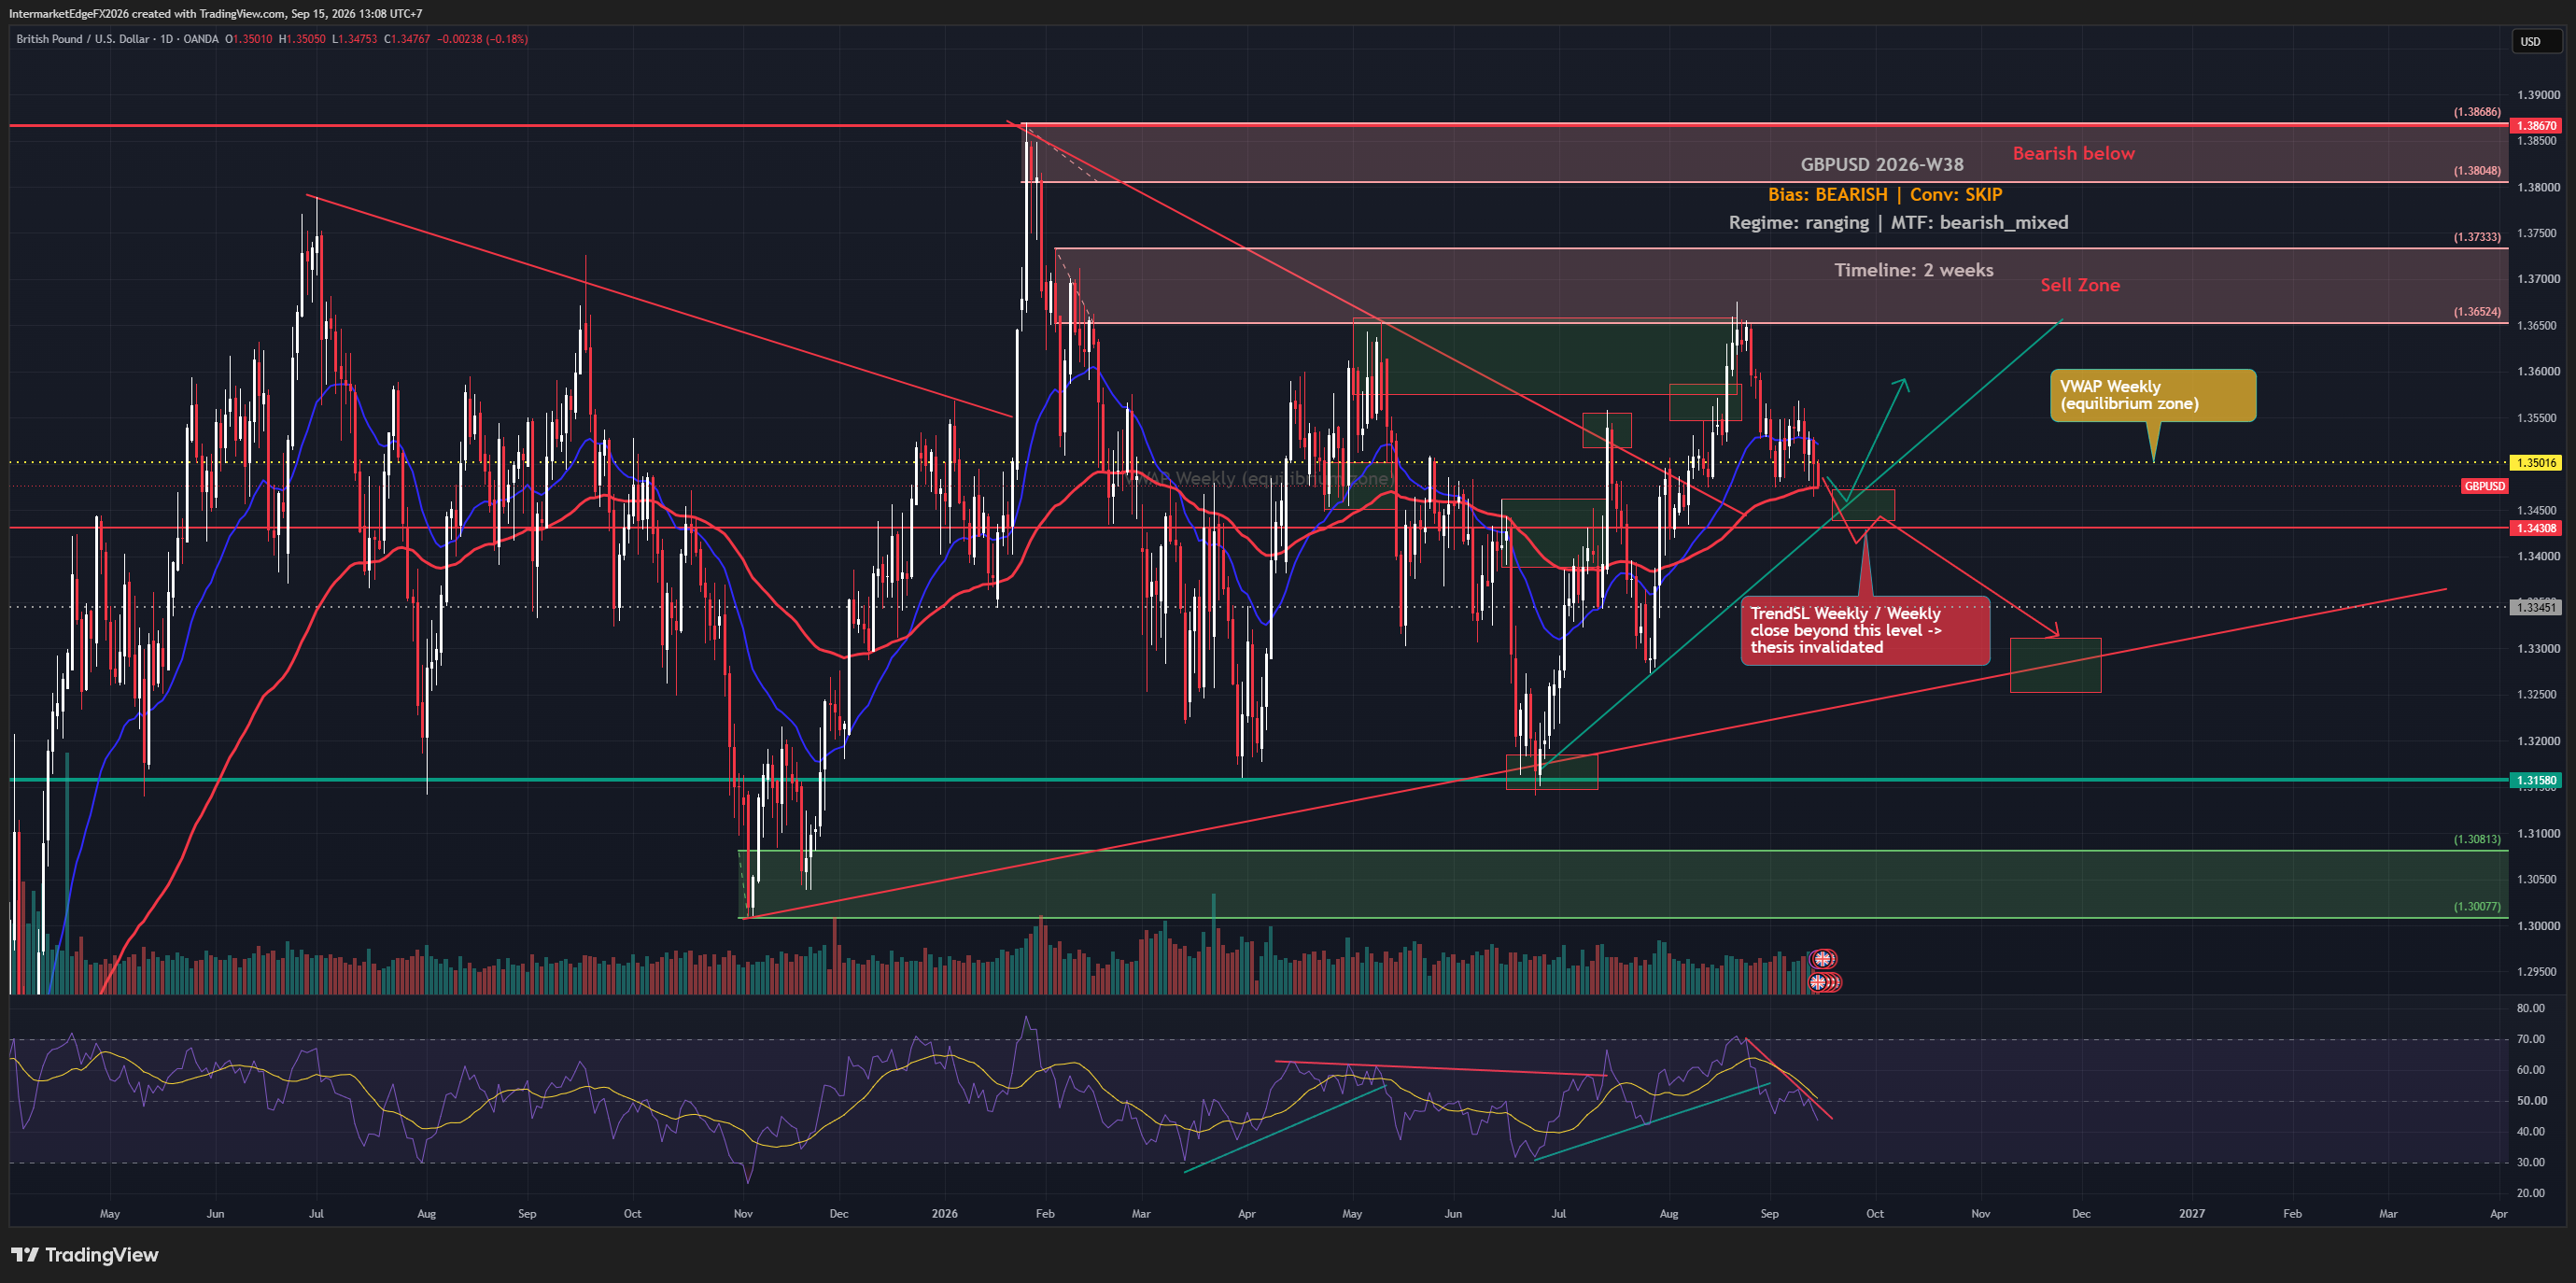
The US 10-year yield is pressing toward 5%, a level not seen since 2007, and that alone is enough to keep a bearish lean on GBPUSD for this week. But with the Federal Reserve decision due September 16 and the Bank of England following on September 17, the rate-differential story is incomplete. GBPUSD touched 1.3474 before recovering, and how it responds to those two decisions will matter far more than where it sits right now. The directional lean for GBPUSD this week is bearish, but the conviction behind that lean is deliberately thin, thin enough that staying out of a new position is the more defensible choice until the evidence consolidates. The entire bearish argument rests on one causal chain: a hawkish Fed stance pushes real yields higher, which widens the rate differential, the return gap between dollar and sterling assets, in the dollar's favor, making GBPUSD a structurally weaker pair. That chain is real and it is the clearest force in the setup. What is missing is any confirmation from price behavior or institutional positioning. COT data, which tracks how large speculative traders are aligned, contributes no directional score this week, meaning there is no evidence that professional money has built a meaningful short sterling position to amplify the macro thesis. Retail positioning at 54% long and 46% short, per broker sample data from fxssi on September 15, is effectively balanced and offers no contrarian signal in either direction. The TGA fell roughly 12% over four weeks to $843.7 billion as of September 9. A Treasury cash drawdown generally returns cash to the banking system, which can ease dollar funding conditions and work against the bullish dollar narrative at the margin. None of these cross-currents produce a clean picture. -- Intermarket Edge (Note: COT (Commitment of Traders) data is released weekly by the CFTC with a reporting-period lag -- it is not a real-time position feed. See cftc.gov for the exact release schedule.)

GBPUSD W37-2026: Bullish Technical Structure Conflicts With the Bearish Macro View

GBPUSD W37-2026: Bullish Technical Structure Conflicts With the Bearish Macro View

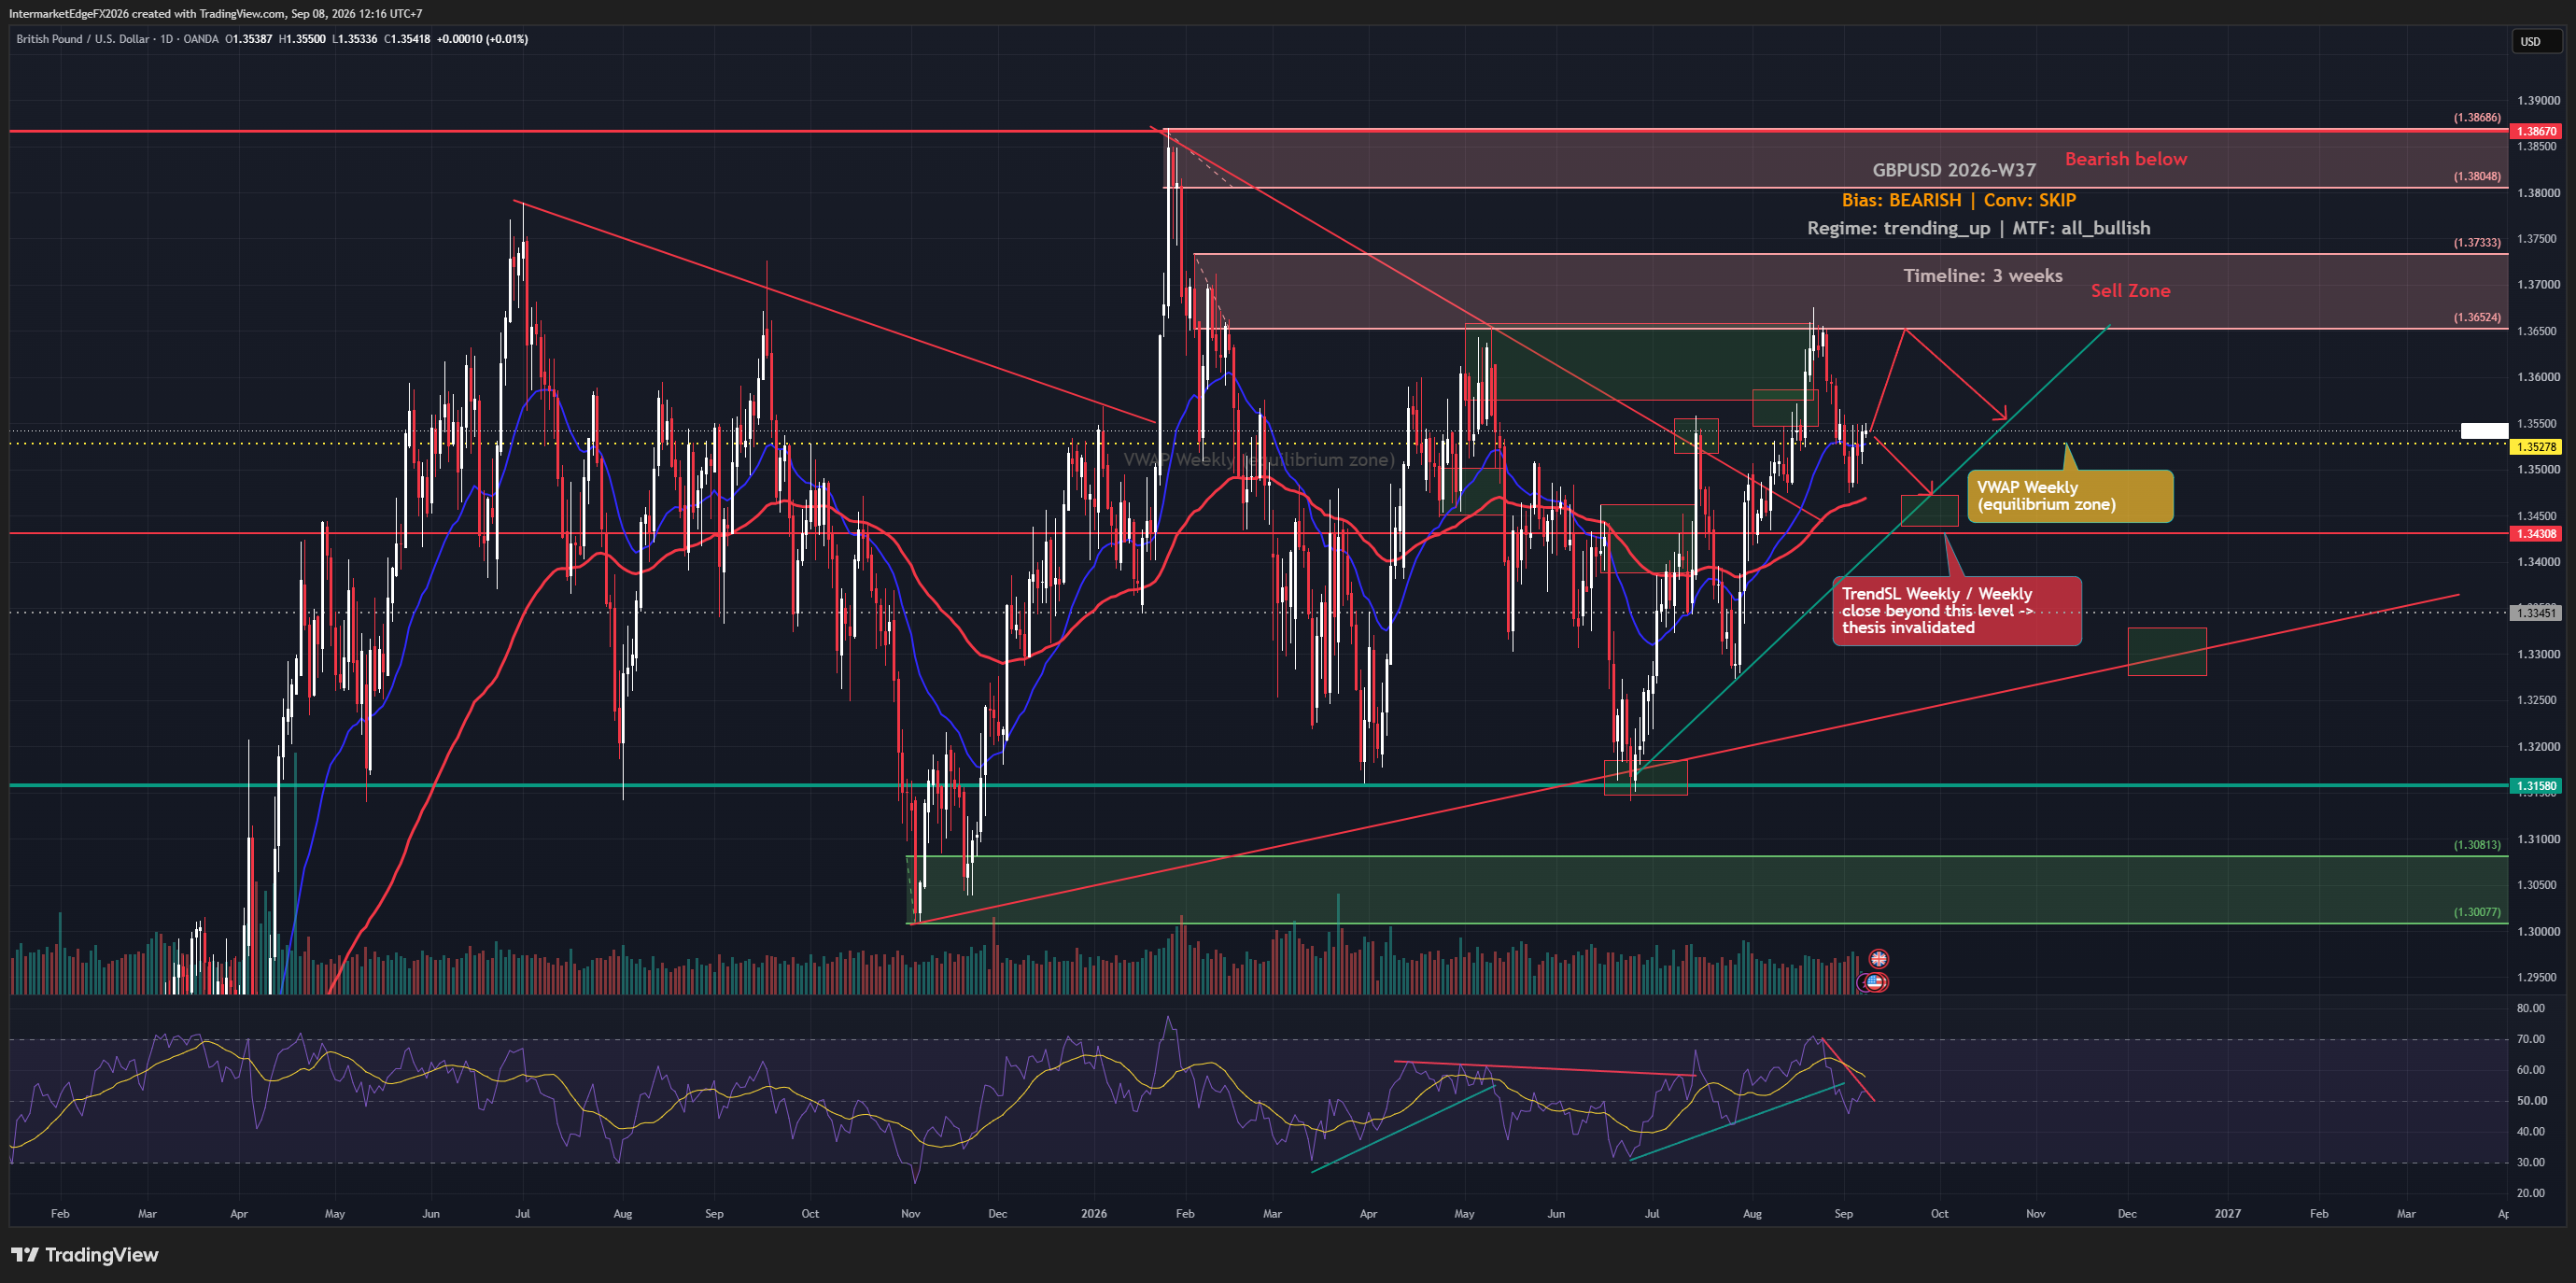
GBPUSD is technically bullish but carries a low-confidence bearish macro bias for W37-2026. The practical decision is to stand aside over a three-week analysis horizon. The locked price was 1.35479 at 05:03 UTC on Tuesday, September 8, 2026, from mt5:GBPUSD.sml:1m. Price was above weekly VWAP 1.35278 by about 20 pips and above weekly TrendSL 1.34308 by about 117 pips. The bullish structure is already active; the bearish label is not technically confirmed. A weekly close below 1.34308 is the defined bearish confirmation condition, not an automatic sell instruction. Strong US payrolls increased expectations of a Fed rate hike, while Reuters reported broad dollar softness ahead of August CPI. The CPI outcome is unknown. The US 10-year real-yield reference is 2.42%, but one level does not prove yields rose or that the US–UK rate differential widened. Huw Pill supported raising Bank Rate to 4% and warned about persistent second-round inflation effects from energy shocks. John Healey pledged fiscal discipline, but sterling received little clear direction from the speech. The COT input is directionally bearish for GBPUSD; its report week, release date and net position are missing, so it cannot establish current crowding or flows. Watch US PPI on September 10, then UK monthly GDP and US CPI on September 11, per ForexFactory calendar data. Outcomes remain unknown. Reassess after the releases and price reaction. Intermarket Edge For informational and educational purposes only. Not financial advice.
EURGBP Week W36-2026: Technicals Hold Bullish Structure Above 0.85647, But the Macro Story Has a Hole in It

EURGBP Week W36-2026: Technicals Hold Bullish Structure Above 0.85647, But the Macro Story Has a Hole in It

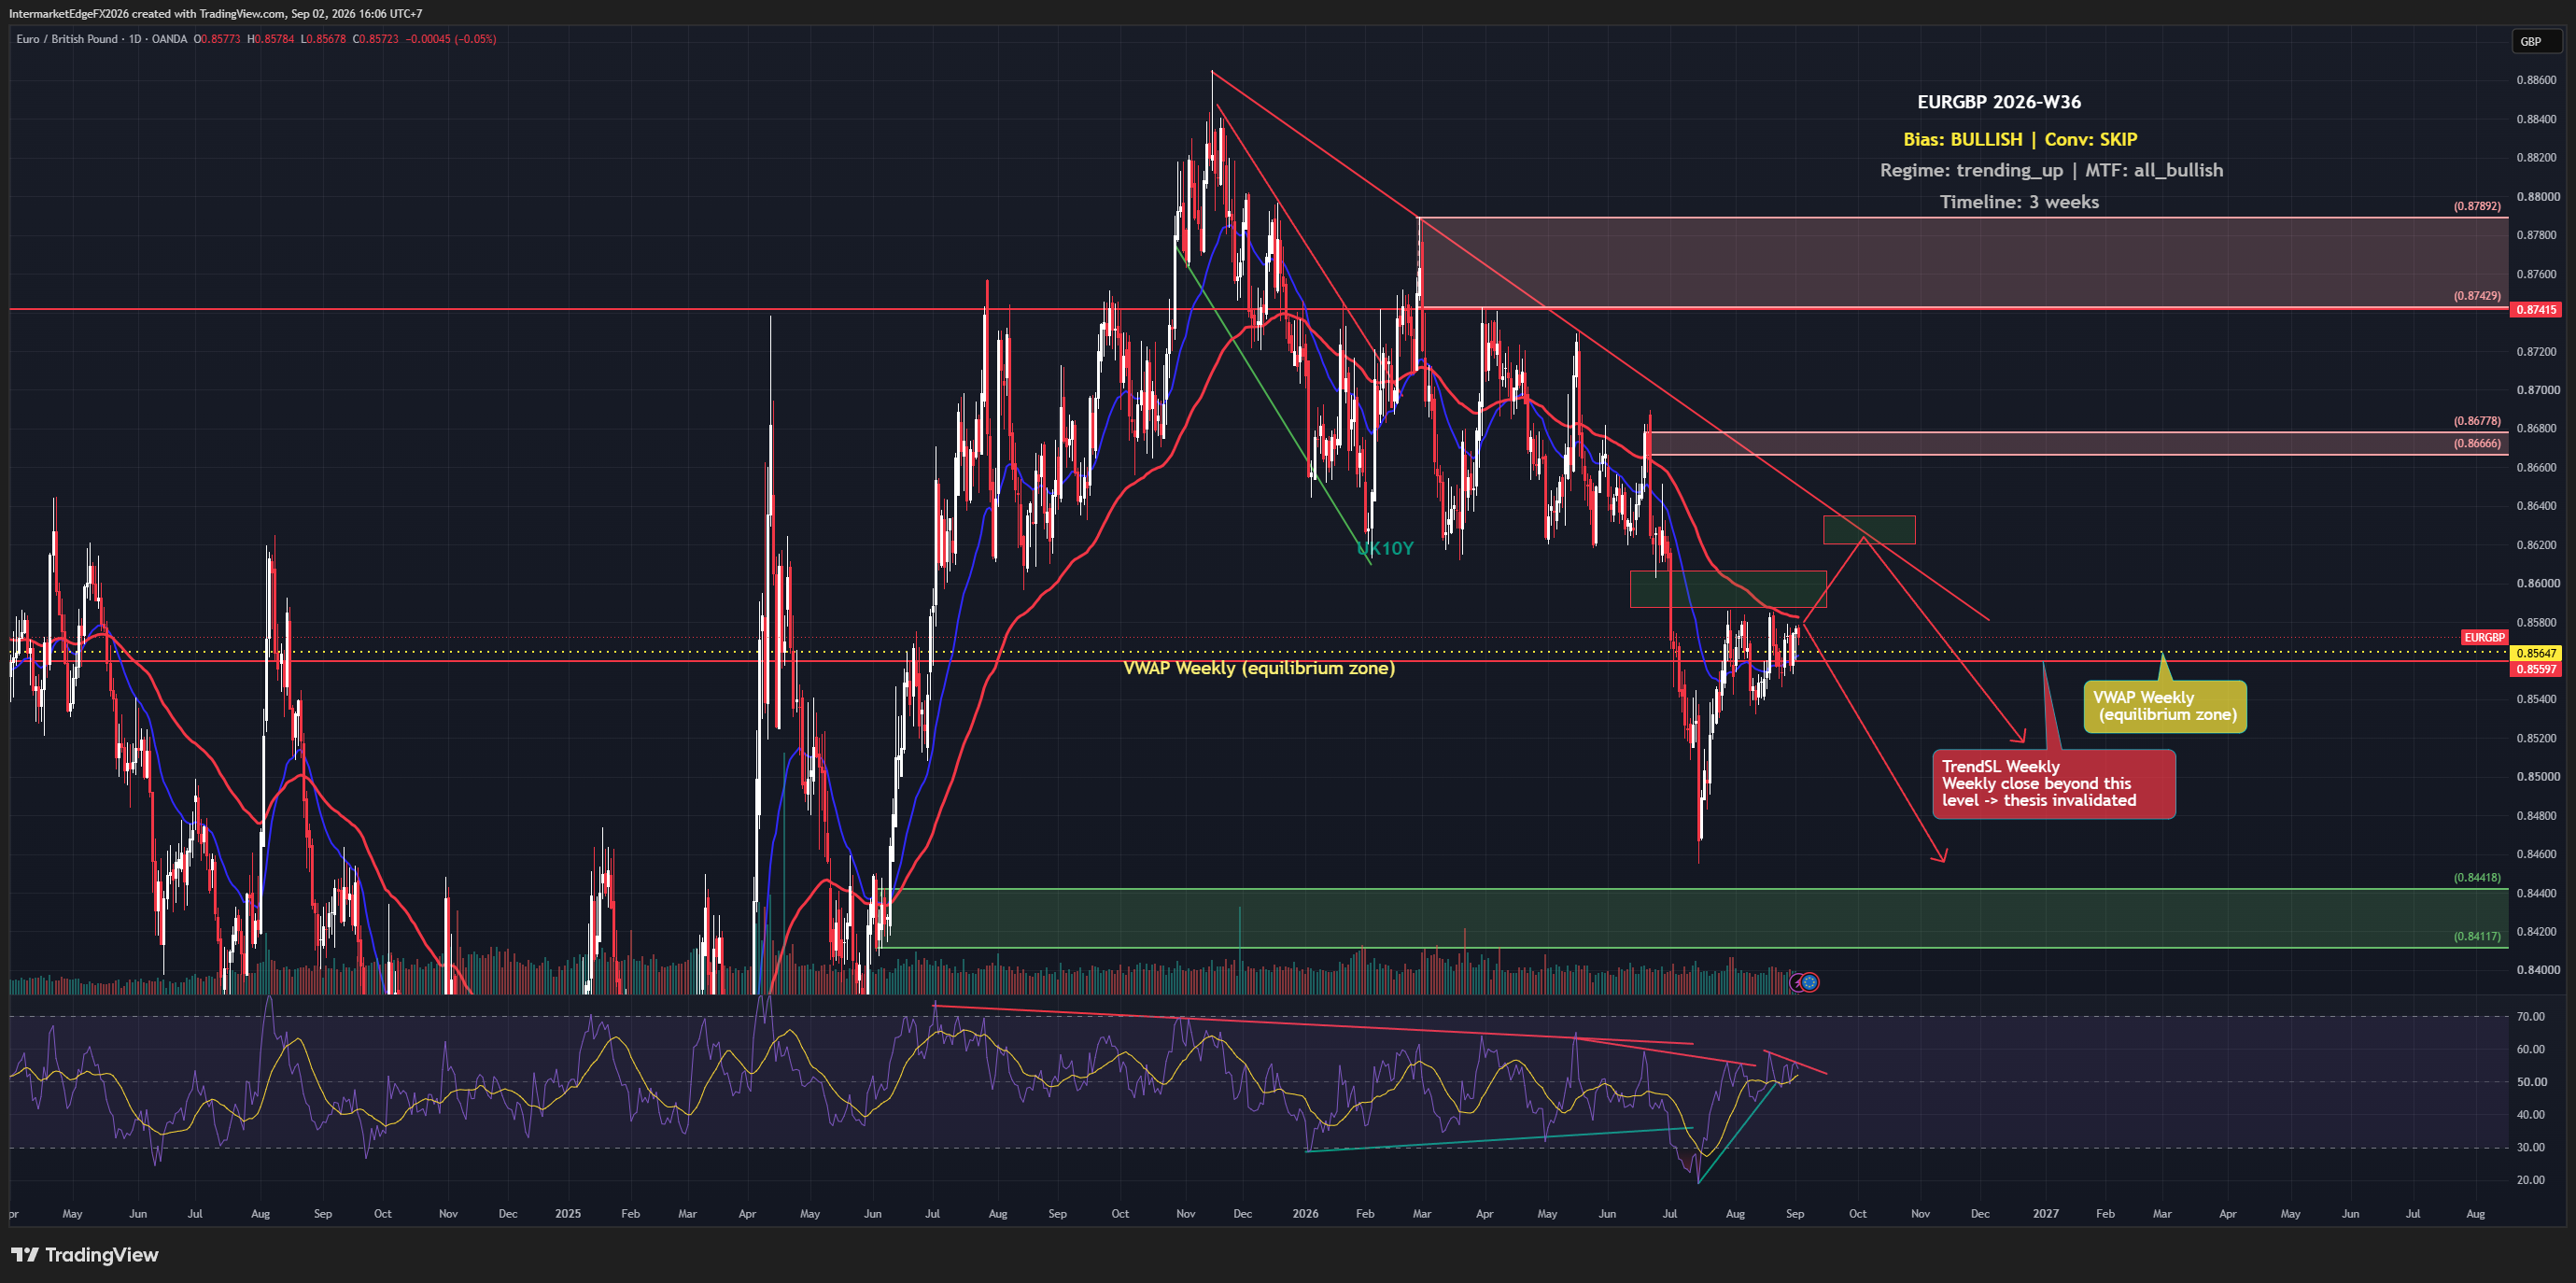
EURGBP is trading above its weekly VWAP at 0.8577 as of Wednesday, 02 September 2026, with charts aligned bullish across every timeframe. The catch: the entire bullish case rests on technical structure alone, no macro confirmation, no positioning signal, nothing beyond price telling you which way to lean. That narrow foundation is exactly what makes this week's setup worth watching carefully rather than trading aggressively. The bullish bias on EURGBP this week is real but structurally thin. Daily, weekly, and monthly technical trend signals are all pointing the same direction, that multi-timeframe alignment, where price structure agrees across short, medium, and long horizons, is the strongest argument for the upside case. It reduces the probability that you are catching a random short-term noise move against a larger trend. What it does not do is tell you why the move should continue or how far it goes. The stated fundamental driver for this pair is the ECB versus BoE rate differential, the gap between where the two central banks are setting rates and where markets expect them to go, which directly affects the relative attractiveness of holding euros versus pounds. That differential is a plausible and historically significant driver for EURGBP. The problem this week is that the macro evidence has produced no confirming signal. The rate differential is the narrative, but the data behind it has not fired. That gap between a coherent story and an absent signal is the defining tension. The practical consequence is that the conviction level here amounts to a deliberate decision to stand aside. The technical foundation is present; everything else that would normally underpin a higher-confidence directional trade, positioning data, a macro catalyst, sentiment confirmation, is not contributing. -- Intermarket Edge

Stay in the loop

Get notified about new research, macro insights, and market analysis.

InterMarketEdge

© 2026 InterMarketEdge. Financial intelligence for inter-market traders.