Instrument Deep Dive — InterMarketEdge

Instrument Deep Dive

Full L0–L8 structural analysis on a single instrument — conviction, invalidation, and time horizon

EURGBP Week W31-2026: Price Pushes Above VWAP at 0.85345 as BoE Decision Looms and ECB's Lane Flags Oil as a Medium-Sized Shock

EURGBP Week W31-2026: Price Pushes Above VWAP at 0.85345 as BoE Decision Looms and ECB's Lane Flags Oil as a Medium-Sized Shock

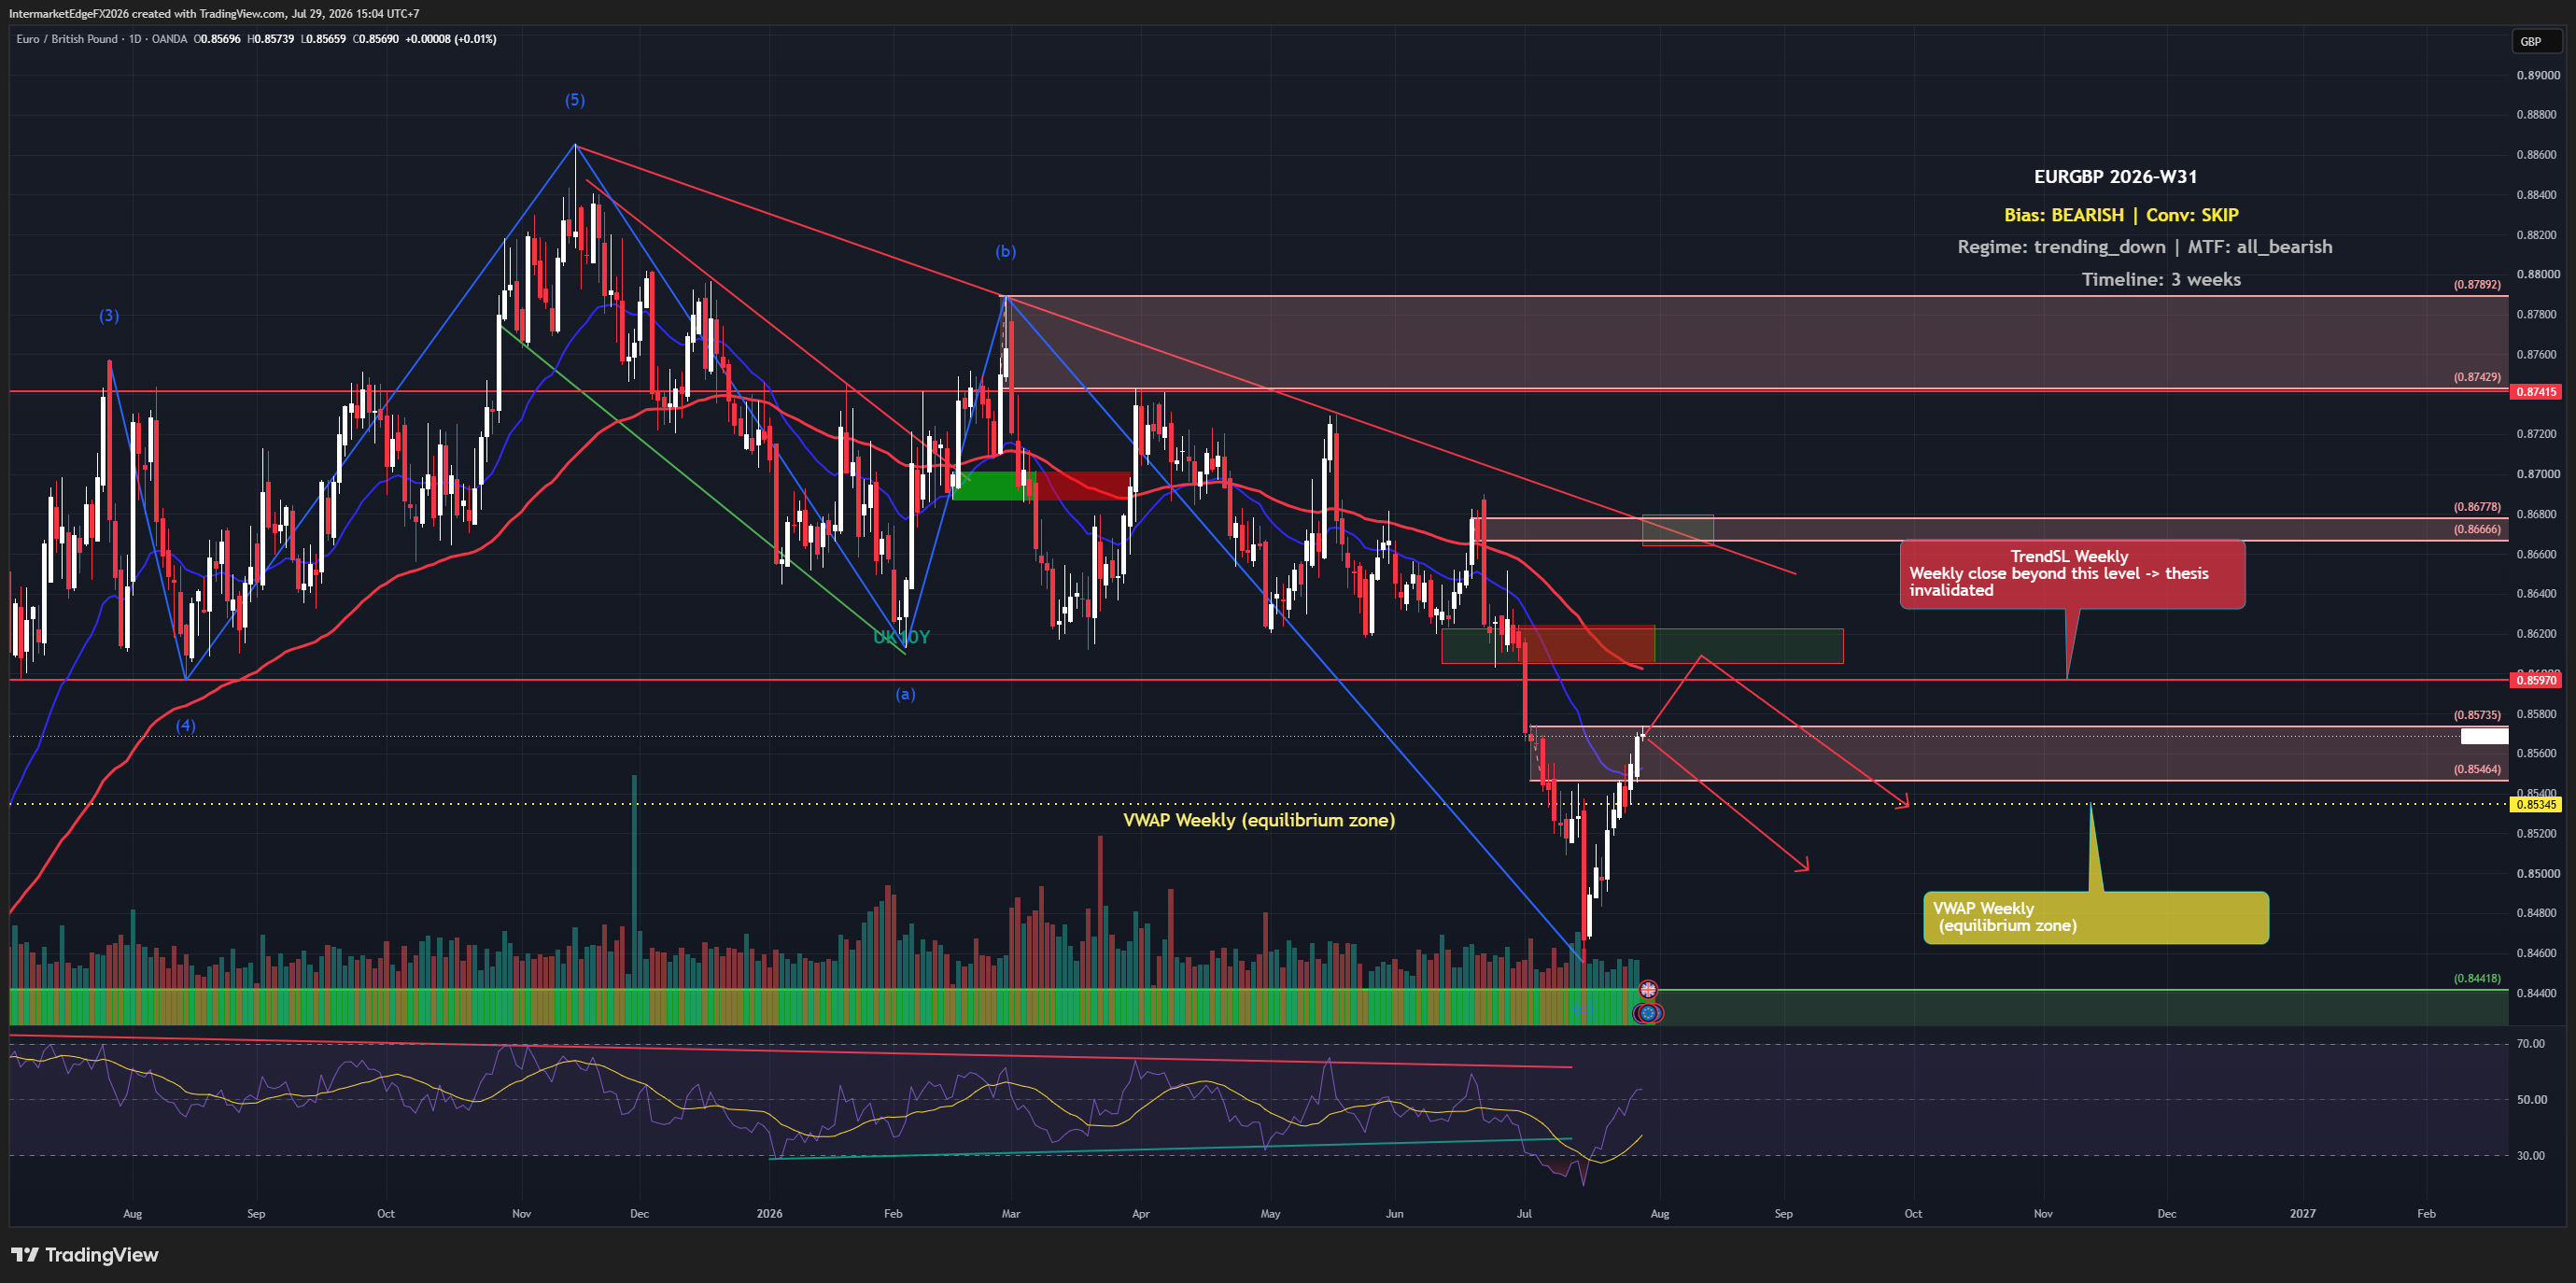
EURGBP is trading at 0.85703 as of Wednesday, 29 July 2026, above the weekly VWAP of 0.85345 and pressing up toward the trend stop-loss at 0.8597. The broader trend regime remains down, multi-timeframe alignment is fully bearish, and the ECB just printed a softer-than-expected core CPI reading. Yet the near-term price action is running directly against the directional bias, and conviction is low enough that sitting on the sidelines is the disciplined call right now. The structural bias for EURGBP during the week of 2026-W31 is bearish, sitting within a confirmed trending-down regime where multi-timeframe alignment is fully bearish across all measured timeframes. In a clean trending environment, the appropriate FX implication is trend-following, meaning the directional lean is to sell rallies rather than chase breakdowns. However, and this is the critical caveat that shapes the entire week's approach: conviction is too low to justify entering a directional trade at this time. The sole active signal driving any conviction this week comes from price action itself, and it is pointing bullish, running directly against the stated bearish bias. All other inputs that would normally reinforce a short case, including positioning data, macro rules, liquidity conditions, and sentiment readings, are producing no active signals at all this week. That vacuum means the bearish thesis rests almost entirely on regime classification rather than on converging, real-time evidence. The structural driver cited for the pair remains the ECB versus Bank of England rate differential, but no macro rules are currently firing to quantify or confirm how that differential is expressing itself in price this week. The ECB's softer-than-expected core CPI miss modestly shifts the rate-differential calculus in favour of sterling over the euro on the margin, which is consistent with the short-term price pressure we are observing. -- Intermarket Edge
GBPUSD Week W31-2026: Sellers Push Price to Lowest Since July 2 as Fed Decision Looms and Rate Differential Widens Against Sterling

GBPUSD Week W31-2026: Sellers Push Price to Lowest Since July 2 as Fed Decision Looms and Rate Differential Widens Against Sterling

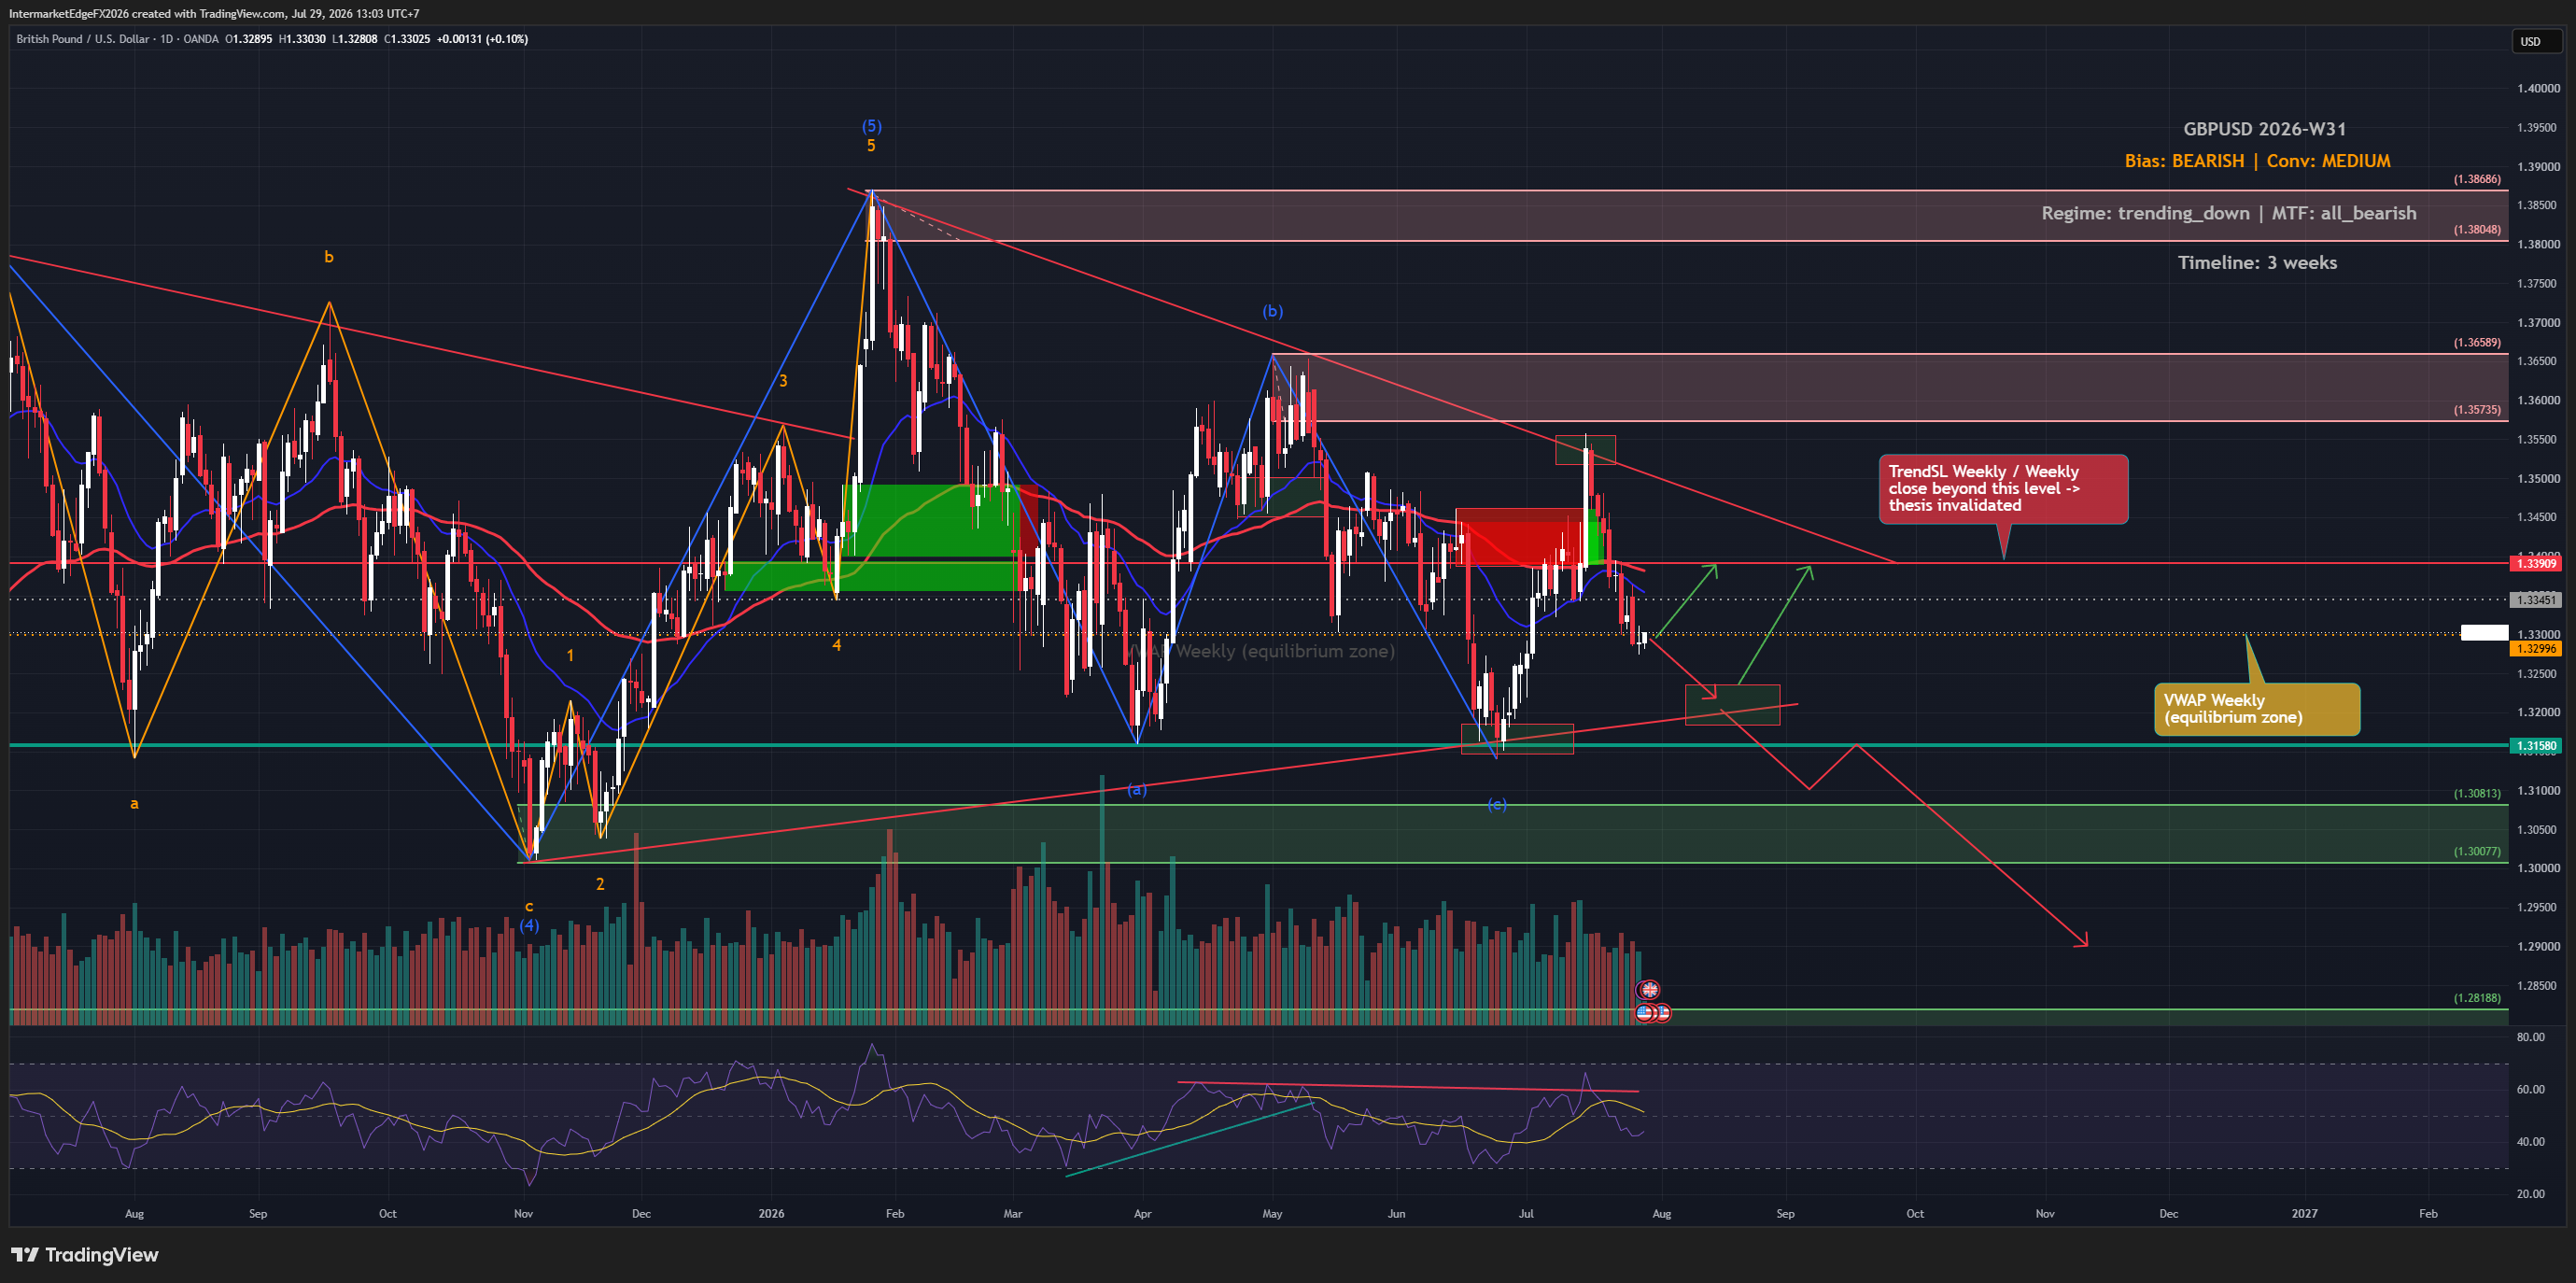
GBPUSD is trading at 1.32988 as of Wednesday, 29 July 2026 at 05:39 UTC, testing from underneath its weekly VWAP at 1.32996, a technically fragile position heading into one of the most catalyst-dense 48-hour windows of the quarter. The Fed decision, BOE rate announcement, UK GDP, and US Core PCE all land within two sessions. With multi-timeframe alignment firmly bearish and the macro rate-differential story still pointing toward USD strength, the setup demands discipline over conviction. The core bearish thesis on GBPUSD rests on a rate-differential argument: the BOE versus Fed policy divergence currently favors USD strength, with the Fed maintaining a restrictive stance anchored by elevated real yields while the Bank of England faces a more ambiguous inflation and growth environment. The Fed hawkish causal chain is the dominant driver here, a tightening bias from the Fed mechanically supports the dollar (USD bullish) and, as the quote currency in GBPUSD, exerts downward pressure on the pair. DXY bullish pressure adds a compounding secondary vector, reinforcing the USD-strength narrative from a broader basket perspective. Multi-timeframe alignment is uniformly bearish, which increases trend-follow confidence when price and structure agree with the macro backdrop. That said, the conviction level here is medium, not high, and the reason matters: there is a genuine signal conflict that traders should not dismiss. Both price action and COT positioning (directional survey data, note the brief does not specify report week, net-position figures, or release date, so this should be read as indicative rather than a precise citable statistic) are reading bullish. This means you have institutional-grade positioning and near-term price momentum potentially working against the bearish macro thesis. The practical implication is clear: this is not a setup to chase aggressively. -- Intermarket Edge

XAUUSD Week W29-2026: Breaks Below $4,000 as US-Iran Conflict Fuels Fed Rate-Hike Bets, Bullish Thesis Hangs by a Thread

XAUUSD Week W29-2026: Breaks Below $4,000 as US-Iran Conflict Fuels Fed Rate-Hike Bets, Bullish Thesis Hangs by a Thread

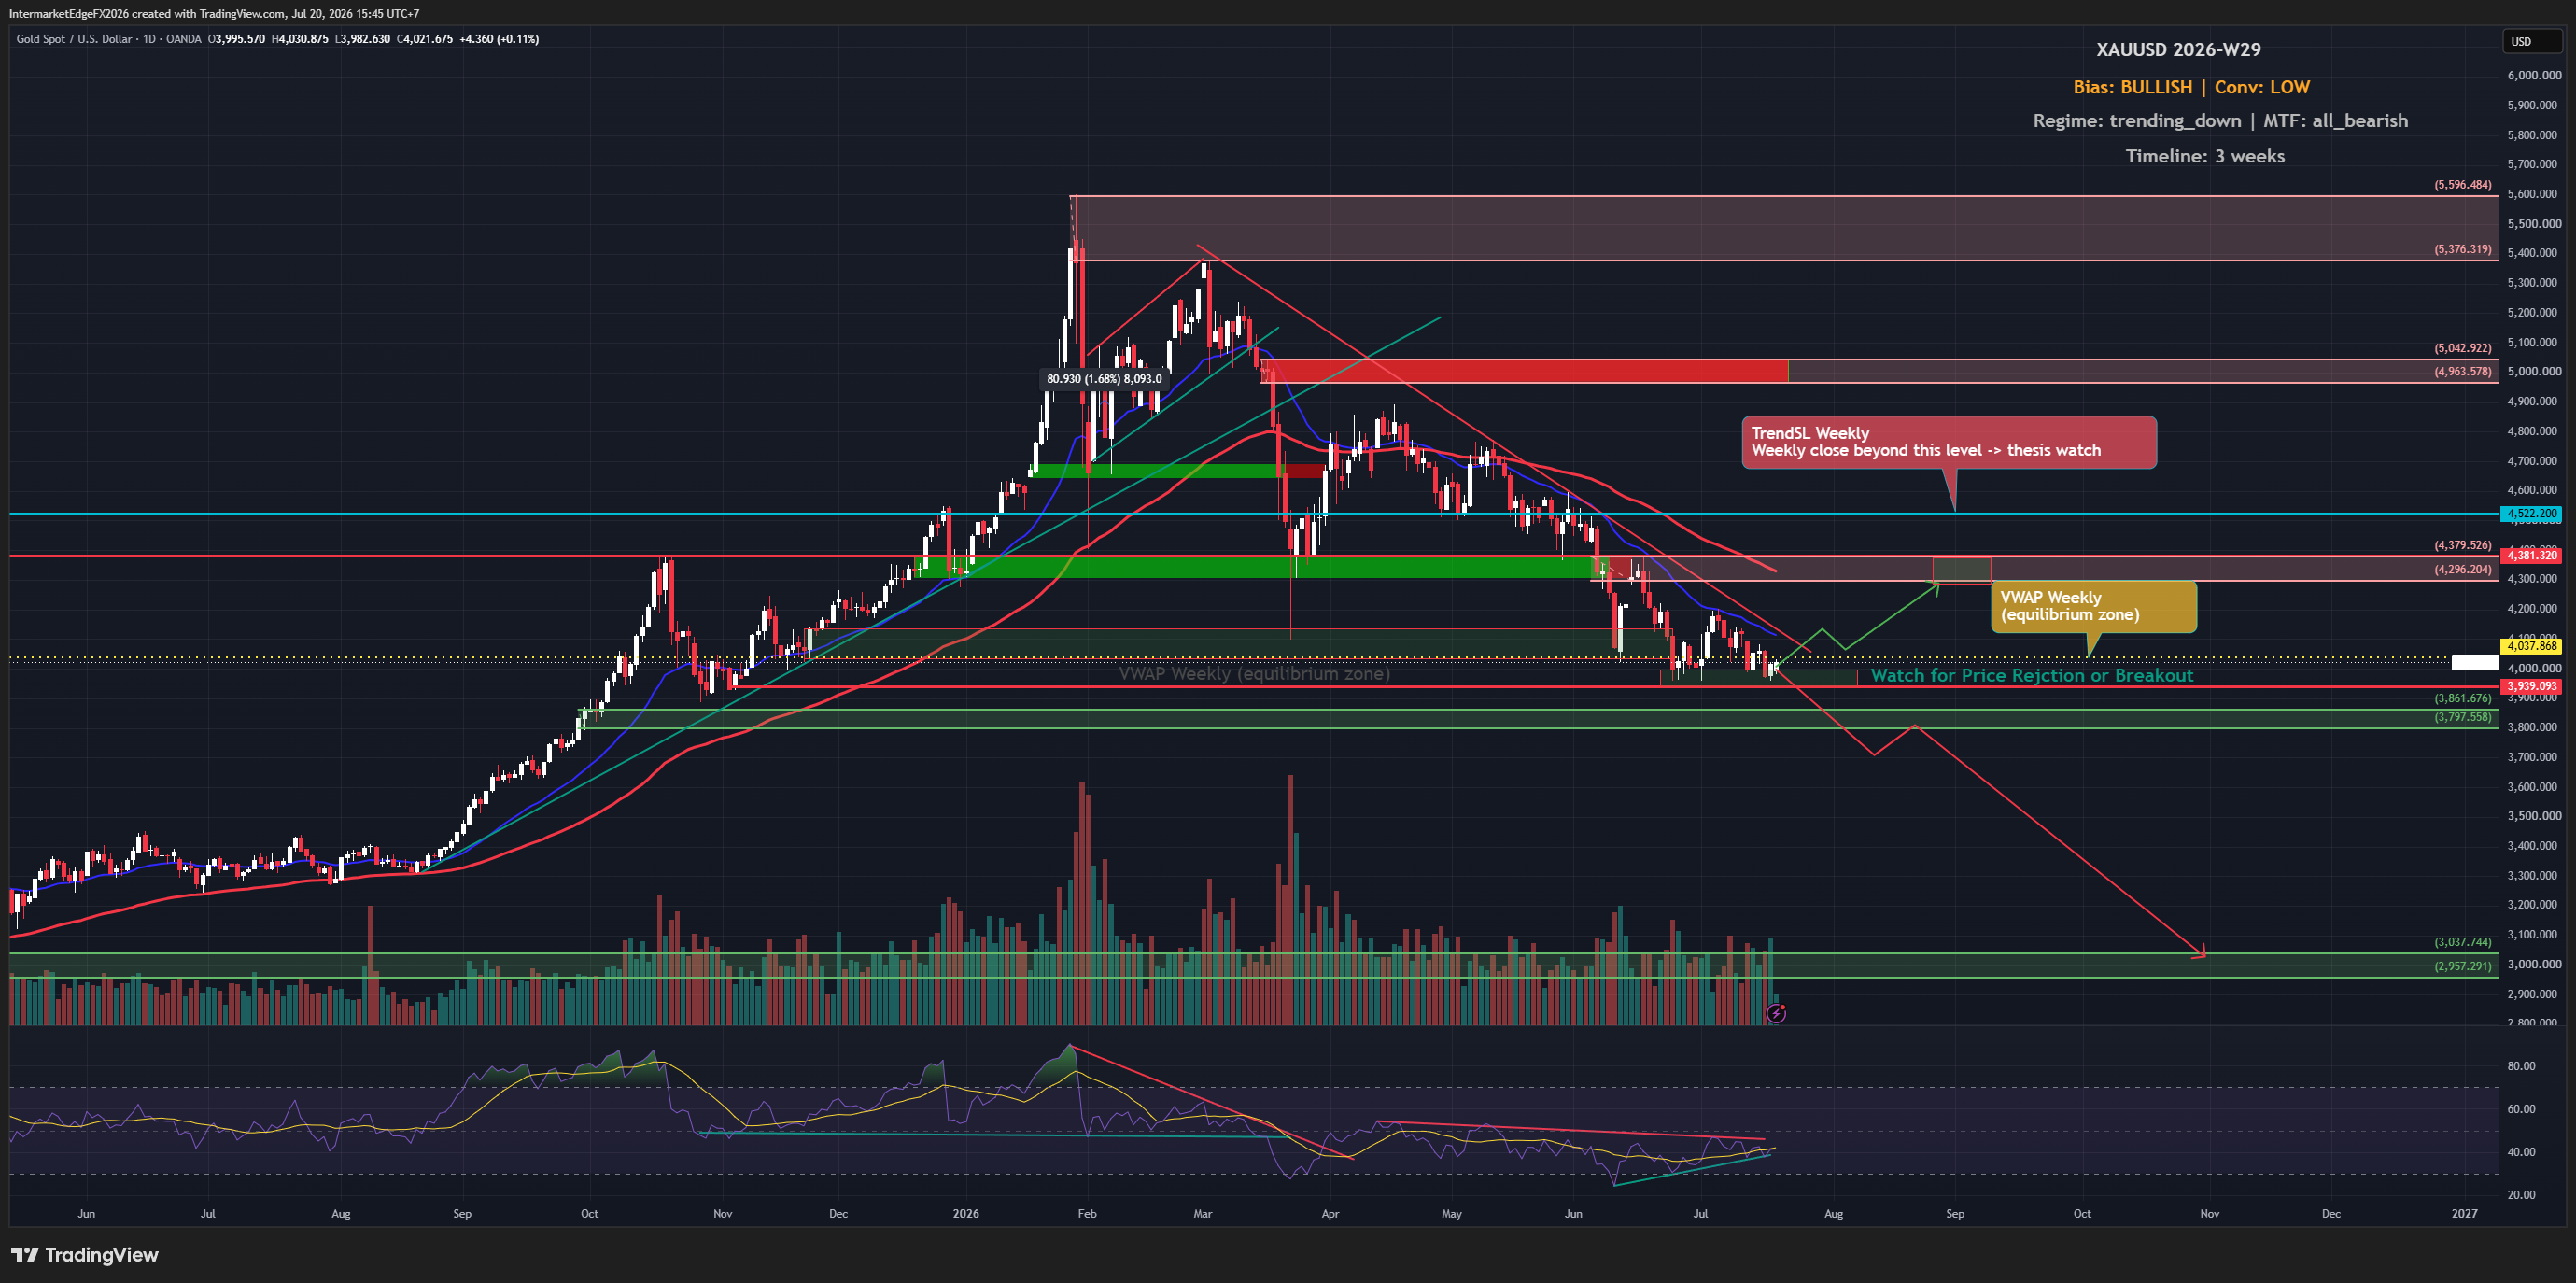
Gold closed at 3,992, slipping below the $4,000 psychological level — a technically meaningful break given price is now also under the weekly VWAP at 4,037.87. That VWAP breach is one of this framework's thesis-break conditions: price sustained below that level signals short-term momentum is running against any bullish case. The driver is counterintuitive but real: the US-Iran conflict is pushing oil sharply higher, reviving higher-for-longer inflation fears and hardening Fed rate-hike expectations. Gold, which typically benefits from geopolitical stress, is instead being sold because the war-inflation channel is hawkish, not a safe-haven trigger right now. Gold is on track for its biggest weekly loss in six weeks. This is happening despite a genuinely dovish CPI print — Core CPI MoM came in at 0.0% vs 0.2% forecast, a meaningful miss that would normally support gold via USD weakness. DXY bias is indeed bearish (low conviction), but that tailwind is being overwhelmed by the rate-hike repricing story. MTF alignment is all-bearish. Regime is trending_down (confidence 0.70), and the FX implication is trend-follow — meaning the path of least resistance is lower. COT and macro signals tilt bullish on paper, but the technical picture and recent price action are speaking louder. Overall bias is logged as bullish with low conviction — an honest reflection of conflicting signals. With price below VWAP and momentum firmly downward, this is not a long entry environment. The TrendSL at 4,522.20 is far above current price; a weekly close above that would be required to validate any bullish structural recovery — that is not a near-term scenario. Watch whether $4,000 becomes resistance on any bounce. -- Intermarket Edge

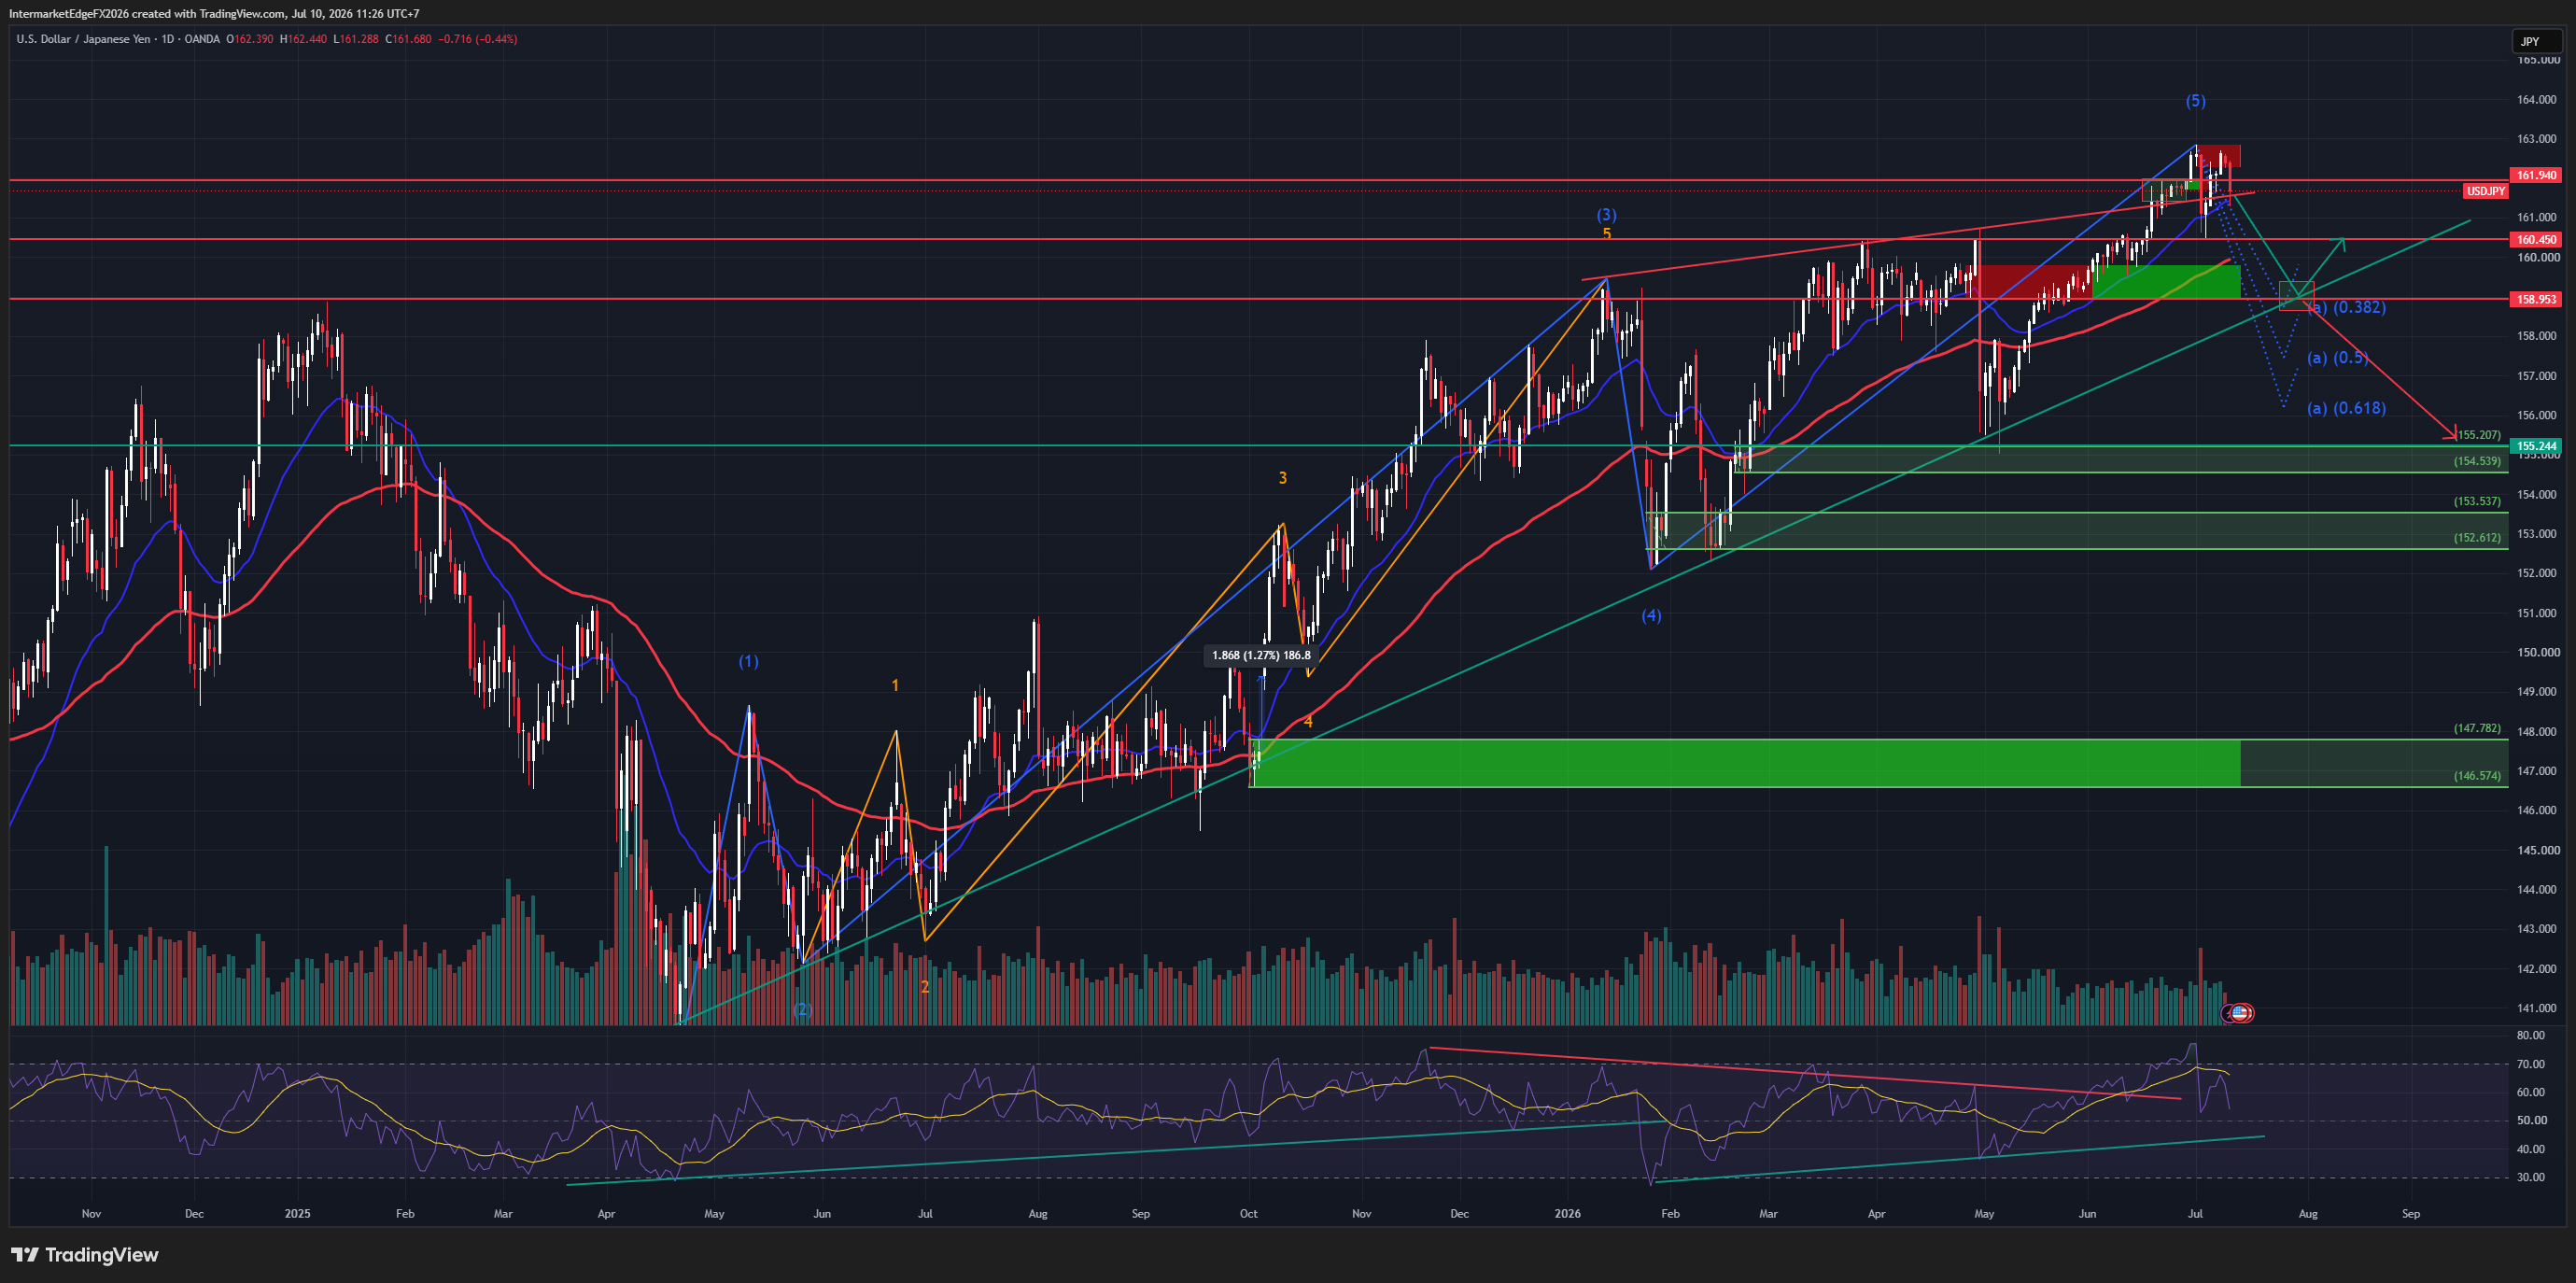
USDJPY - Yen Jumps on Intervention Fears, Last Week's Wave (a) Thesis Toward 158.953 Is Playing Out Exactly as Scripted

USDJPY - Yen Jumps on Intervention Fears, Last Week's Wave (a) Thesis Toward 158.953 Is Playing Out Exactly as Scripted

USDJPY - SUMMARY 10/07/2026 Regime: Yen jumps on MoF intervention fears, directly confirming last week's "ambush tactics" thesis. Medium Bear near-term unchanged, strongly reinforced by today's real news. Bias: Medium Bear near-term. New factors: Japan encouraging pension funds to invest domestically, June CGPI import index +29.7% y/y (seventh straight monthly rise). VIX fell 6.16% intraday, fourth straight day of cooling since the Iran shock. Data corrections: JP10Y 2.78% (not 1.47%); US-JP spread +1.76% (not the pipeline's own 3.069%). D1 structure: wave (5) peak near 163, now in corrective wave (a), broke through 160.450-161.940 (now resistance), testing 161.55-161.58 just below invalidation 161.940. Target: 158.953, 157, 155.207-154.539. Scenarios: continued decline toward 158.953-157 (45%); range pending confirmation (35%); extended decline toward 155.207-154.539 (15%); bounce invalidating the thesis (5%). Close monitoring of official MoF or BoJ statements needed in coming days. For informational purposes only, not investment advice.

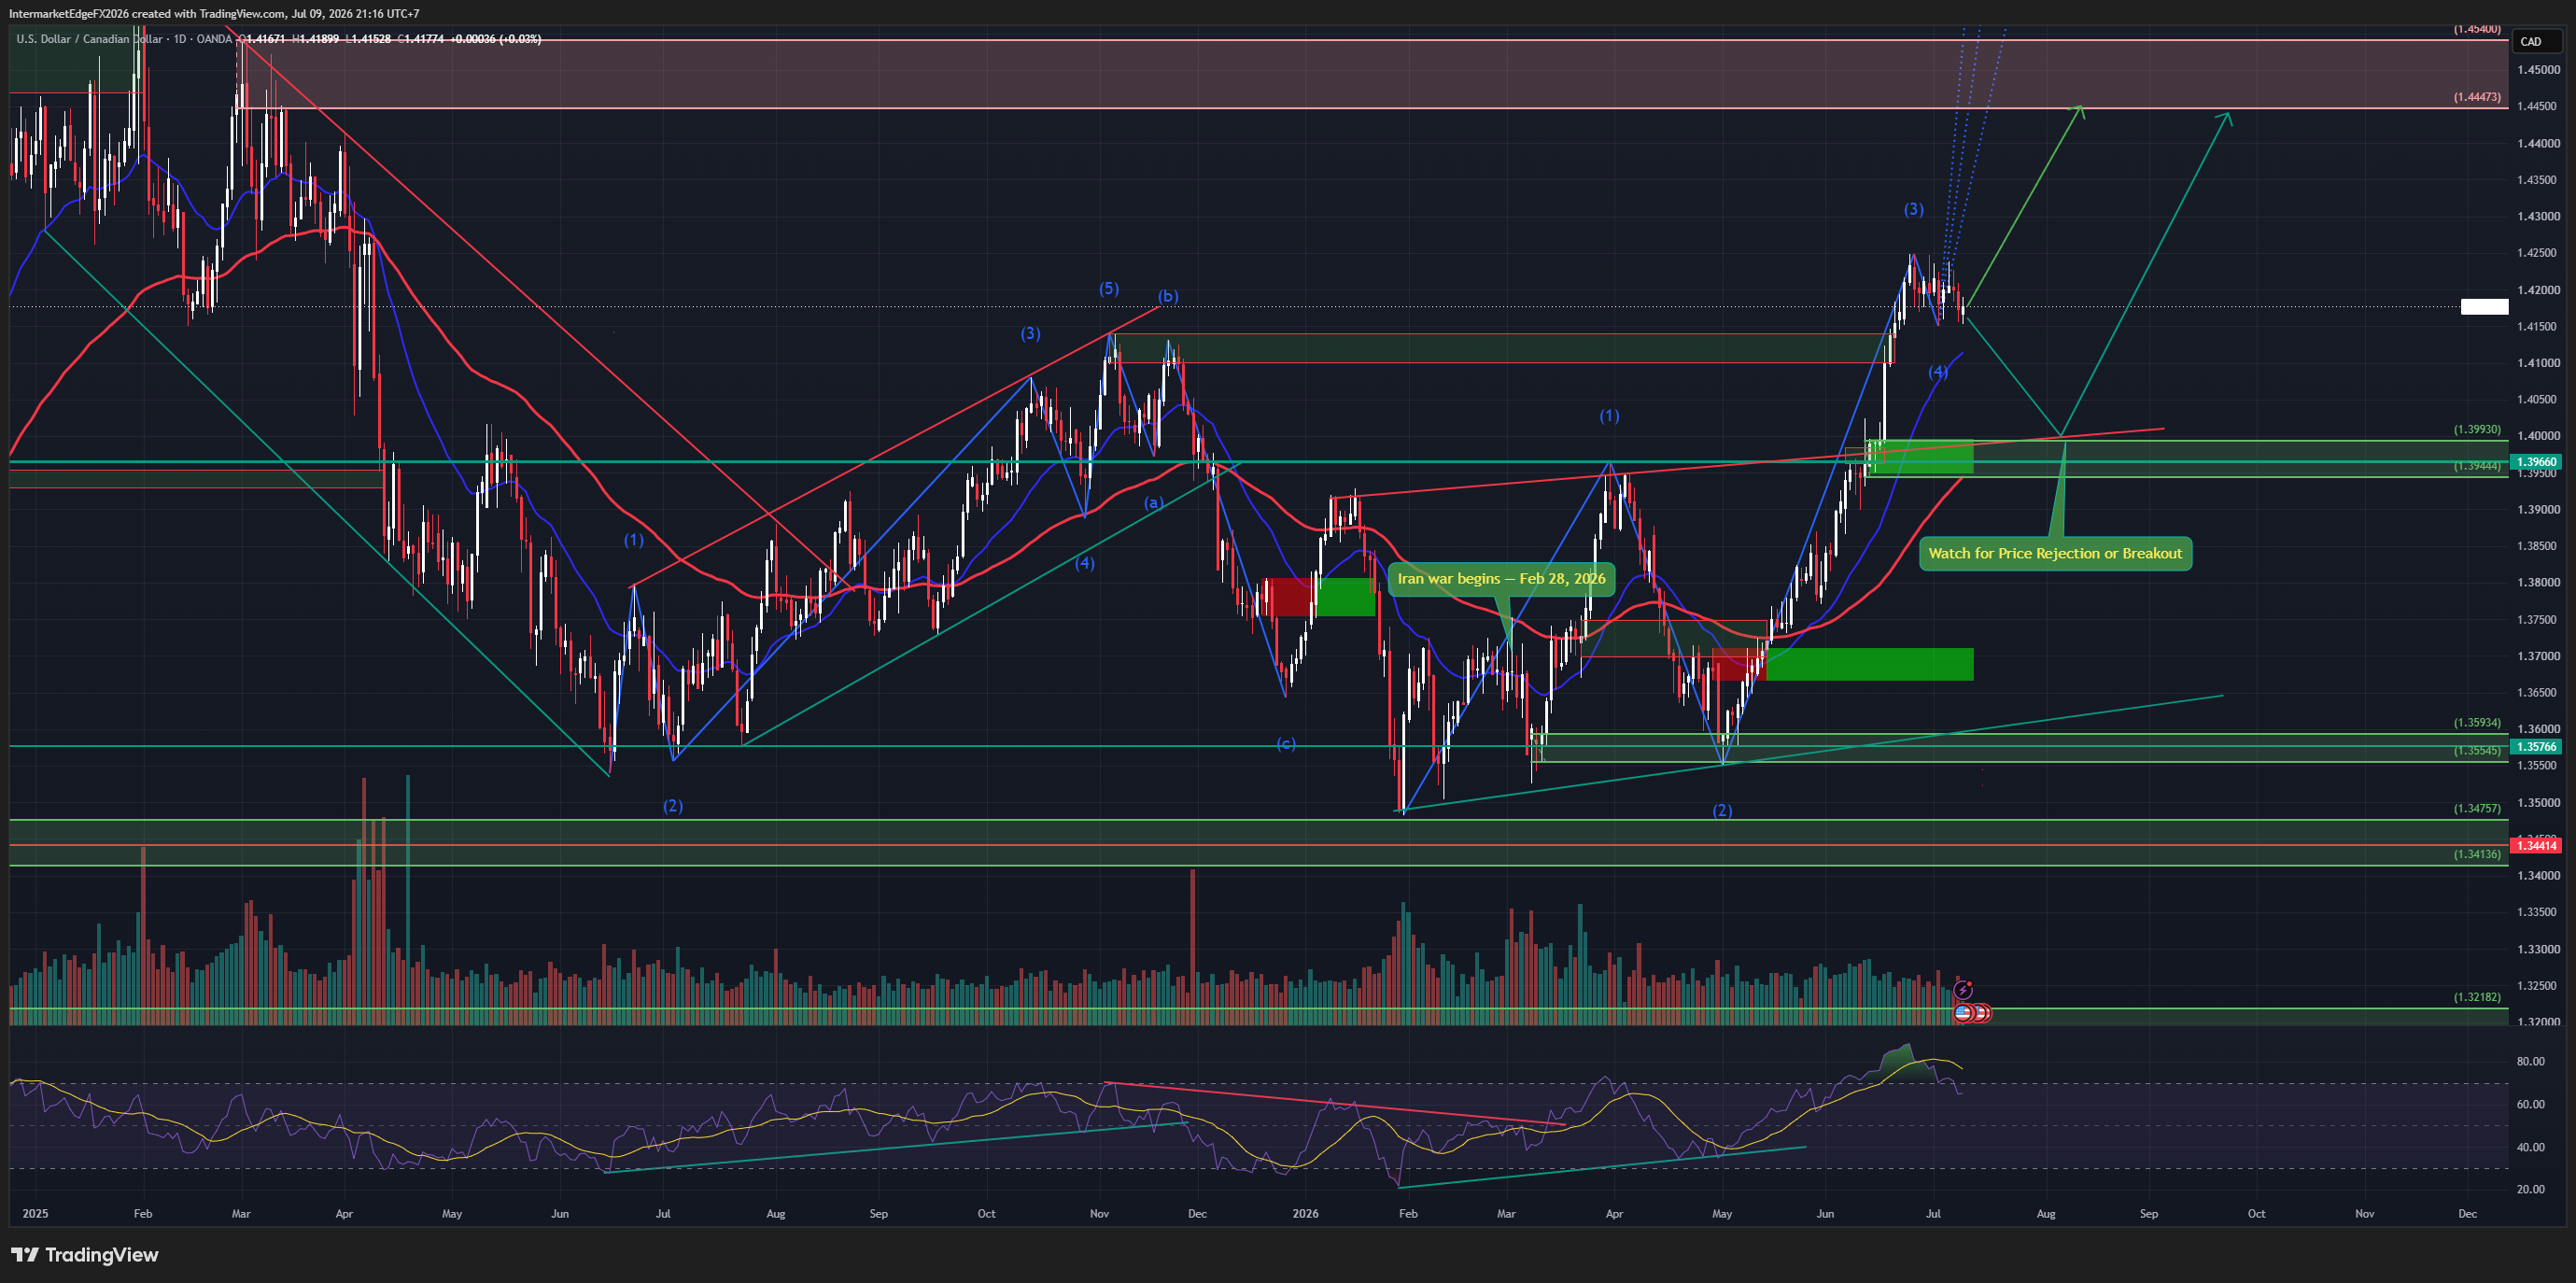
USDCAD - Wave 4 Recovers From a Deeper-Than-Expected Pullback, Price Retests the 1.4174 Decision Zone Ahead of Wave 5 Toward 1.4447-1.4540

USDCAD - Wave 4 Recovers From a Deeper-Than-Expected Pullback, Price Retests the 1.4174 Decision Zone Ahead of Wave 5 Toward 1.4447-1.4540

USDCAD - SUMMARY 09/07/2026 Regime: Wave 4 completed a deeper-than-expected correction (1.394-1.397 instead of 1.415-1.417), now recovering to retest the 1.415-1.417 pivot from above. Medium-High Bull unchanged. Bias: Medium-High Bull. New factors: sharp two-way oil volatility from Iran (detailed in the USOIL piece), down 2.85% today creating near-term weak-CAD pressure. VIX cooling for 3 straight days (18.4 → 17.47 → 16.45). BoC's Macklem shifted mixed-to-hawkish. Data corrections: US2Y 4.18% (not 3.693%); US CPI 4.2% (not 2.4%). D1 structure: wave (3) peaked ~1.42 on target, wave (4) fell deeper than expected to 1.394-1.397, now recovering to retest the 1.415-1.417 pivot. Wave (5) target: 1.4447 then 1.4540. Invalidation below 1.400. Scenarios: holds and continues toward 1.4447-1.4540 (40%); range 1.400-1.420 pending confirmation (40%); break below 1.400 invalidating the thesis (20%). No confirmed date/time yet for the FOMC minutes despite newsflow noting market attention. For informational purposes only, not investment advice.

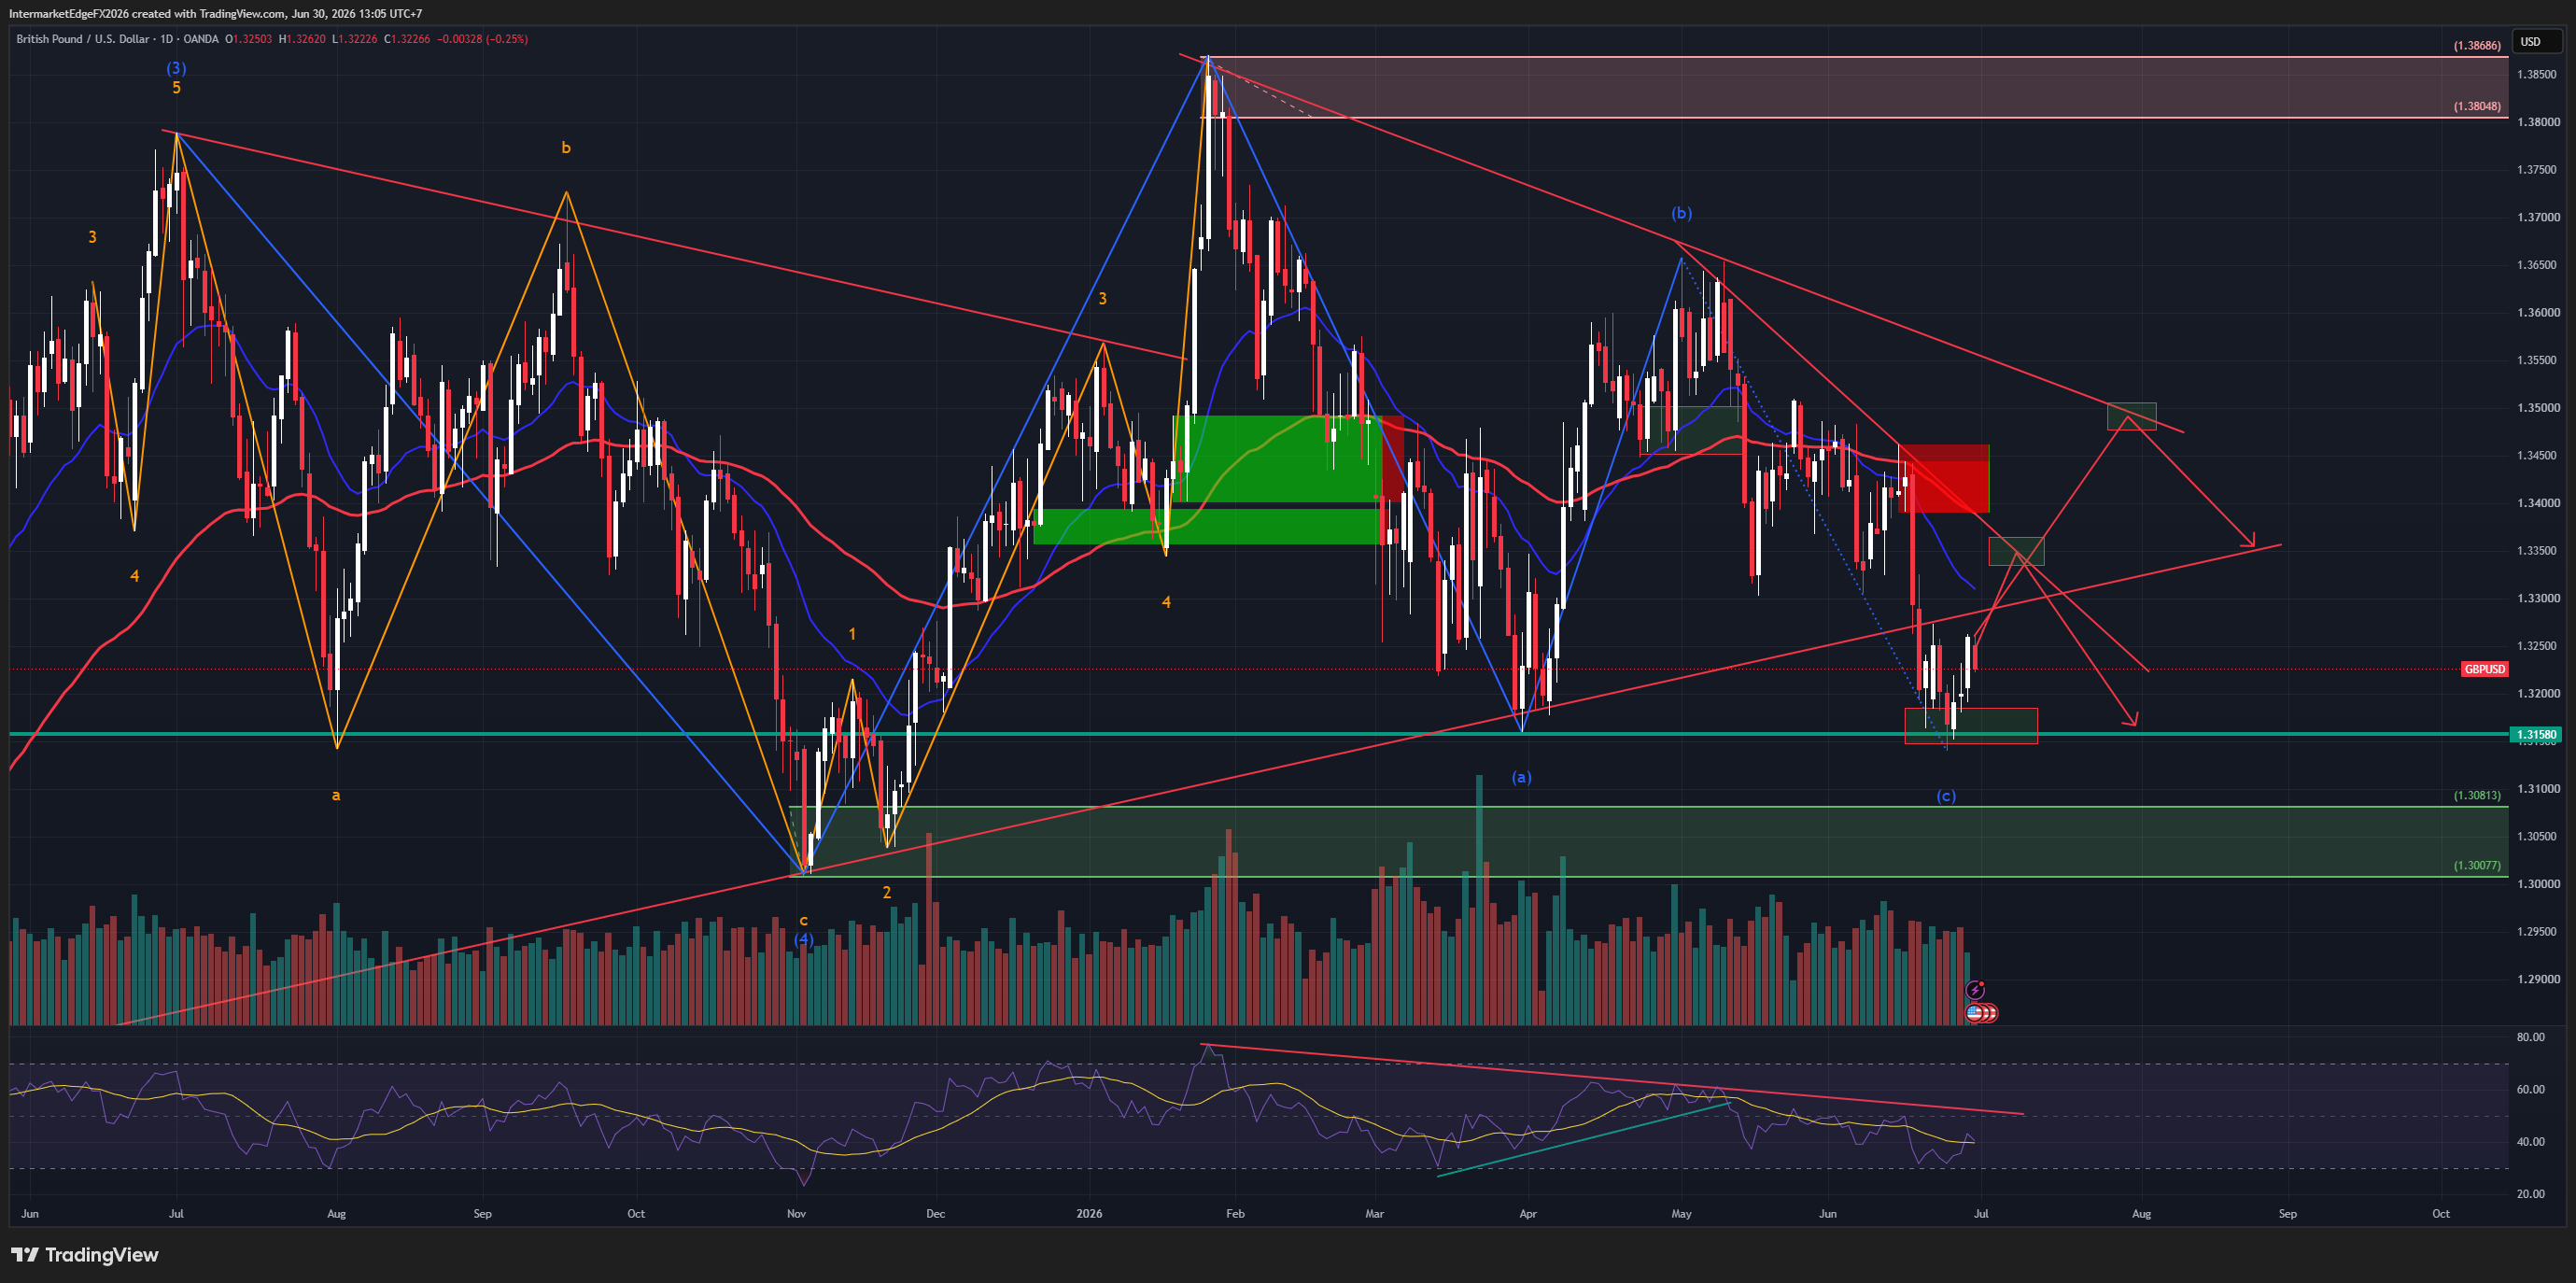
GBPUSD - Technical Bounce After a Sharp Sell-off, but Structure Still Tilts Lower as UK Political Instability Meets Fed Hawkishness

GBPUSD - Technical Bounce After a Sharp Sell-off, but Structure Still Tilts Lower as UK Political Instability Meets Fed Hawkishness

GBPUSD - SUMMARY 30/06/2026 Regime: Technical Bounce, Medium-High Bear Medium Term. GBPUSD 1.3229 (+0.34%), bouncing from the 1.3150-1.3208 support zone after a sharp decline from the wave 3/(b) peak near 1.370. This is a technical reaction at support, not yet a reversal. Bias: Medium-High Bear medium term, neutral within near-term bounce. Two dominant forces: UK political instability post-Starmer resignation 22 June (unresolved), Fed Warsh hawkishness strengthening USD broadly (CPI 4.2%, real yield +0.174%). Actual GB-US 10Y spread of +0.346% (pipeline wrongly reports 0.126%) gives GBP a larger carry advantage than reported, but entirely overwhelmed by political risk premium. Data corrections: US CPI 4.2% (not 2.4%); UK10Y 4.72% (not 4.50%); GB-US spread +0.346% (not 0.126%). D1 structure: converging pattern following the decline from 1.370. Resistance: 1.335-1.340. Support: 1.3150-1.3208 (already bounced). Two-way breakout: above 1.345 or below 1.310-1.315. Scenarios: bounce fails, resumes to 1.300-1.310 (50%); sideways awaiting catalyst (30%); breakout above 1.345 (15%); sharp breakdown below 1.300 (5%). Event risk: UK GDP + Chicago PMI today, NFP 3 July is the dominant weekly catalyst. Do not chase the bounce before the converging pattern breaks clearly. For informational purposes only. Not financial advice.

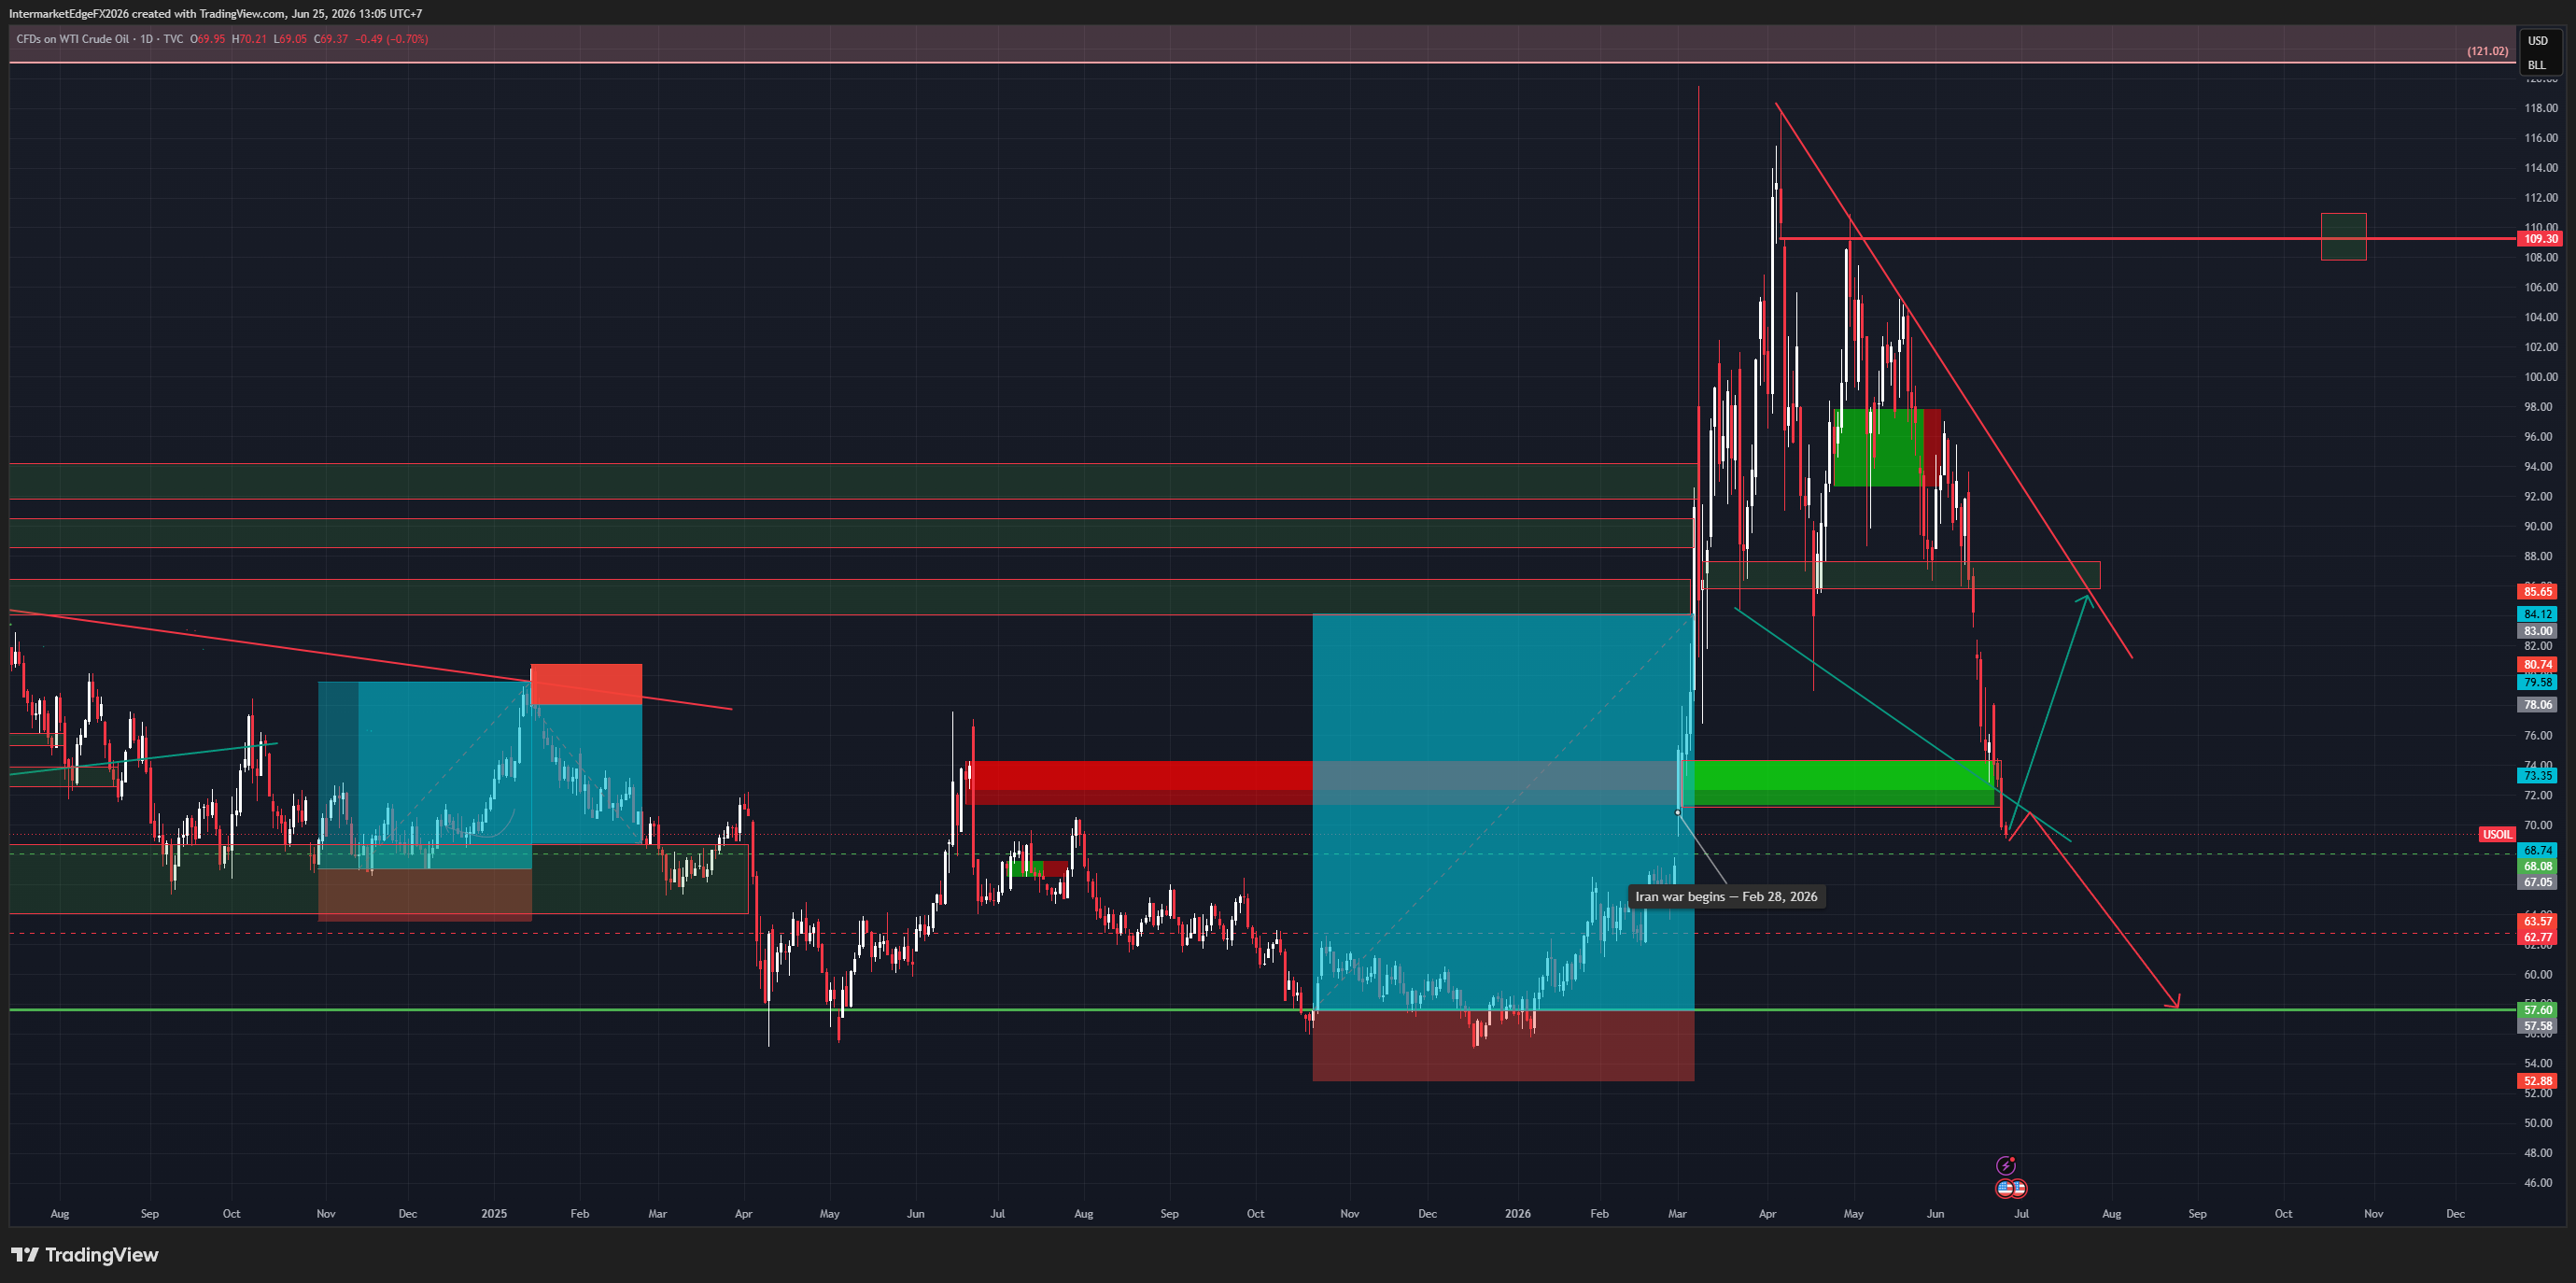
USOIL - Below $71 Confirms the War Premium Fully Erased, Persian Gulf Flows Accelerate as the Market Shrugs Off a -6M Draw

USOIL - Below $71 Confirms the War Premium Fully Erased, Persian Gulf Flows Accelerate as the Market Shrugs Off a -6M Draw

USOIL $69.36 | Below $71, war premium fully erased | 25 June 2026 Last week: "Do not chase shorts into 71.11. A break confirms a further leg, target 67 then 63." It broke. Oil now $69.36, below the pre-war starting point. The most notable signal: the EIA drew 6.088M (forecast just 3.9M), the second consecutive larger-than-expected draw. The market shrugged it off entirely. Oil kept falling. When good news is ignored, the selling force dominates. Three forces: Persian Gulf flows accelerating as Hormuz reopens; global supply recovering + OPEC+ +411kbpd; DXY 101 at a 13-month high. Leading headlines: "Oil Sinks Toward Pre-War Levels", "Crude Oil Falls Below $70", "Oil Market Shrugs Off Large Crude Stock Draw." D1 structure: 71.11 broken (now resistance). Nearby support 67.05 then 63.57 then 62.77. Deep: 57.60 (pre-war bottom). Invalidation: daily close above 74.49. Three scenarios: → Continued decline to 67.05 then 63.57. Probability: 45% → Hormuz fully reopens, accelerates to 57.60. Probability: 25% → Technical bounce to test 71.11 (broken support), resumes lower. Probability: 20% The tell: two consecutive bullish draws, price still falls. The market has answered. Conviction: High Bear (upgraded from Medium Bear). --- Intermarket Edge | Institutional Macro & Intermarket Analysis For informational purposes only. Not financial advice.

EURUSD - Wave (c) Confirmed After Breaking 1.141, a 13-Month DXY High and PMI Beat Push Euro Toward the 1.119 Projection

EURUSD - Wave (c) Confirmed After Breaking 1.141, a 13-Month DXY High and PMI Beat Push Euro Toward the 1.119 Projection

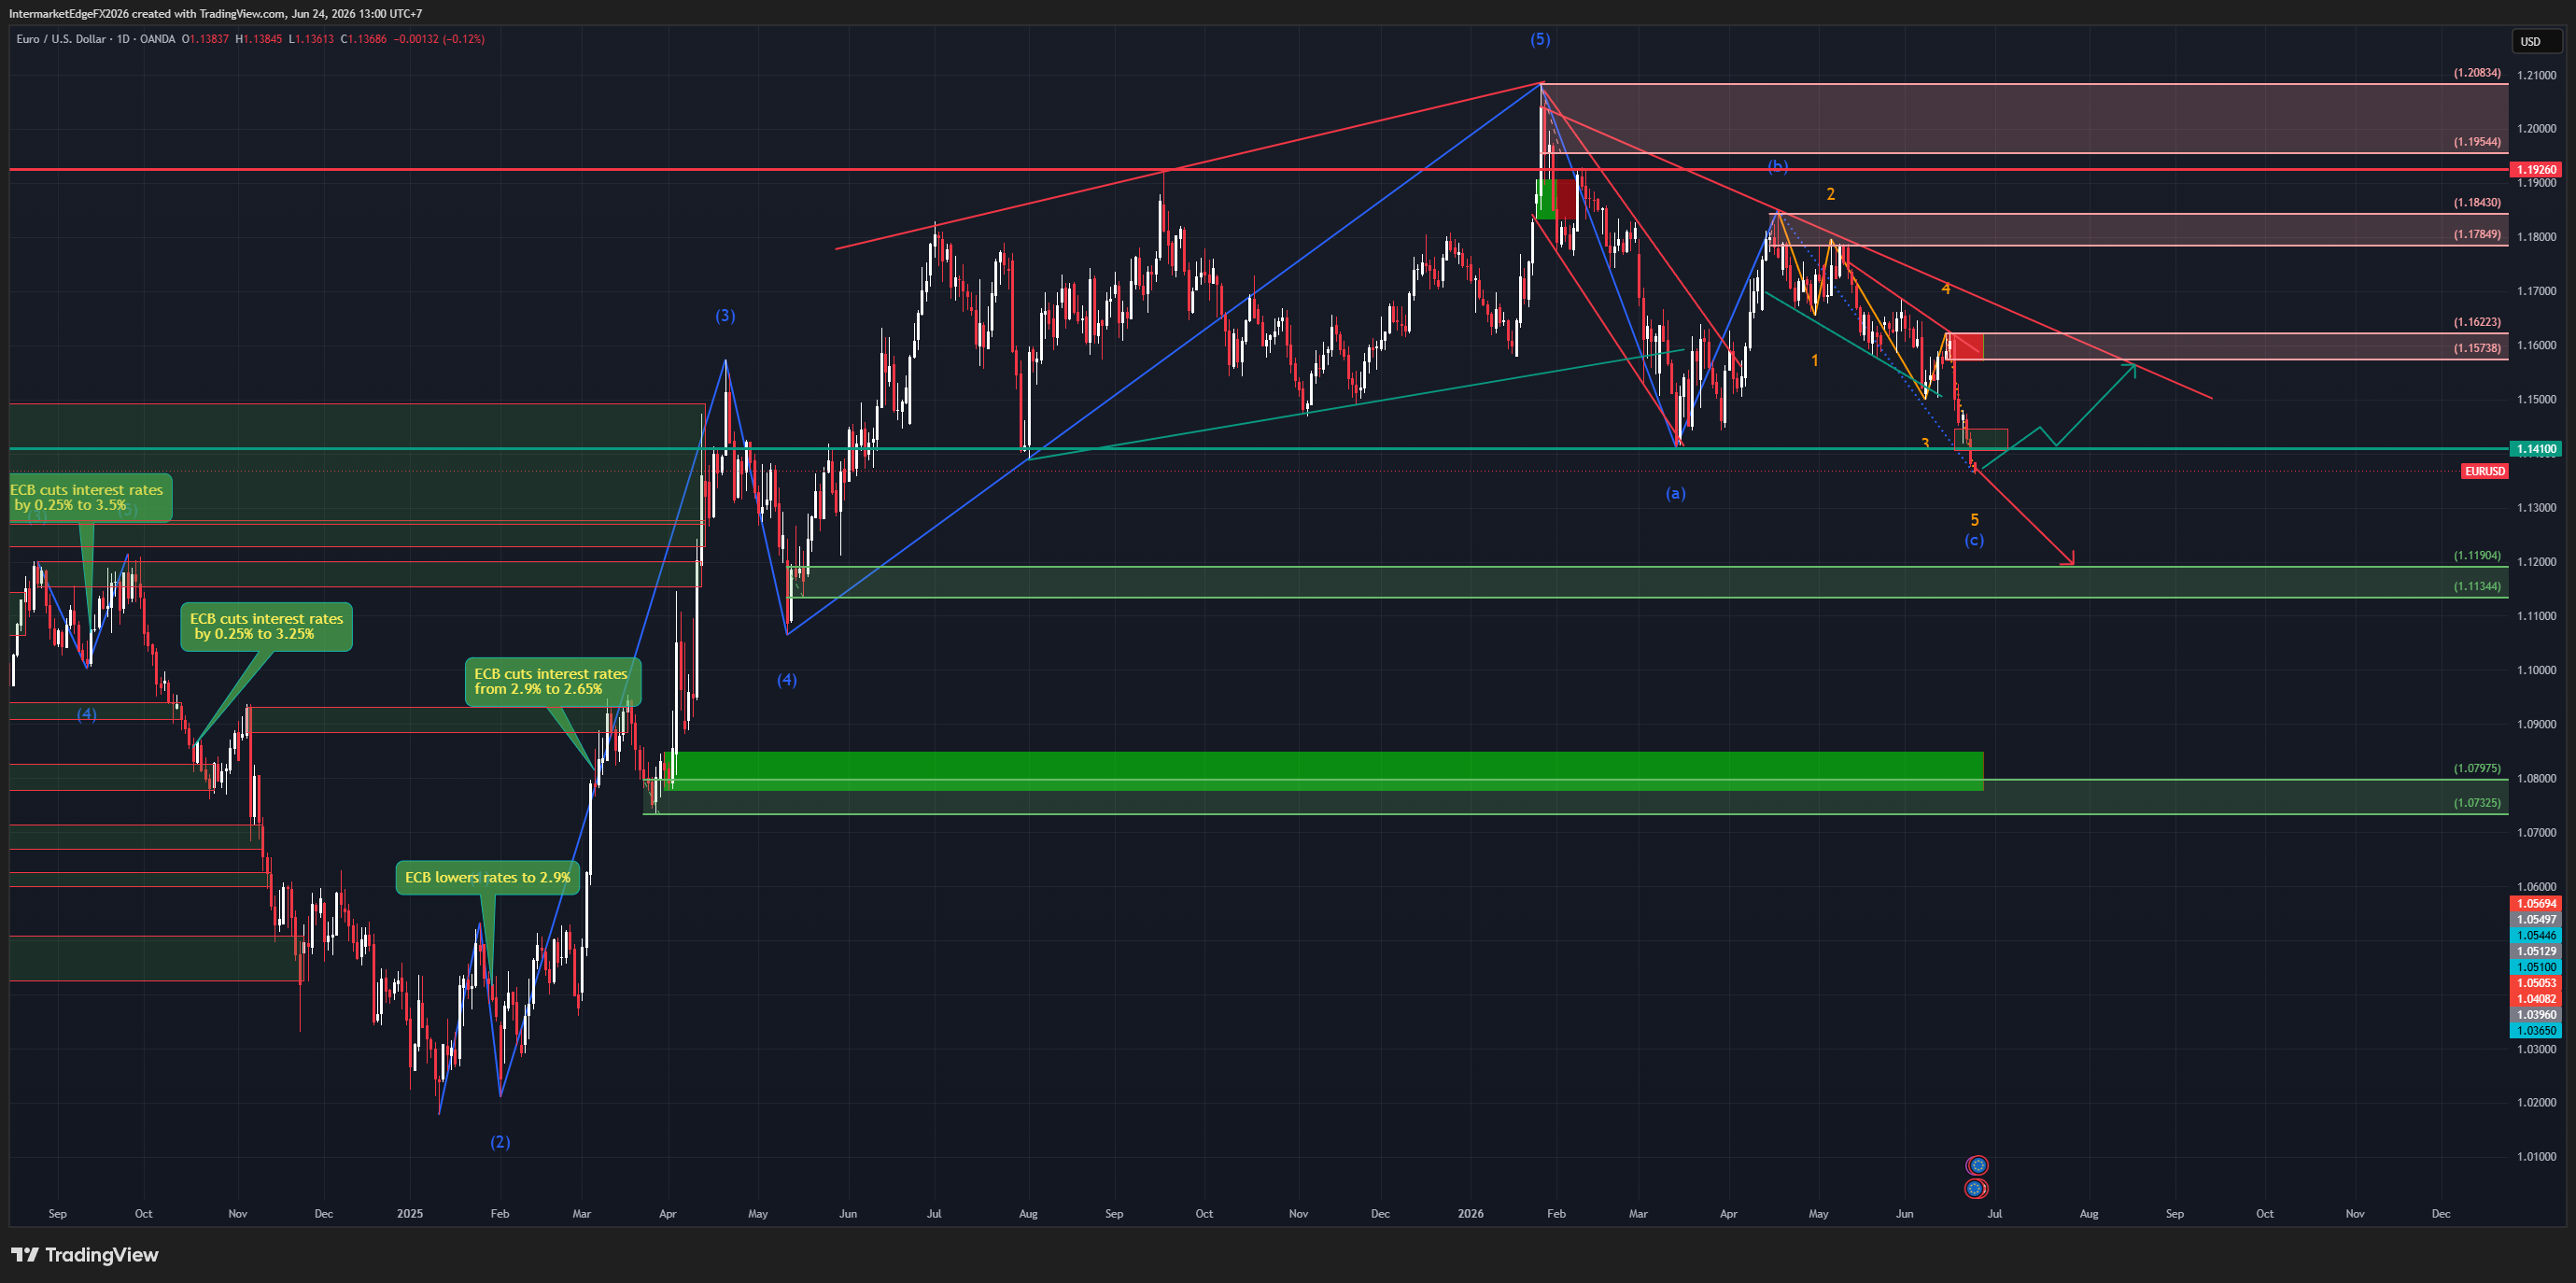
EURUSD 1.1370 | Wave (c) confirmed after breaking 1.141 | 24 June 2026 Last week's analysis set 1.141 as the bearish confirmation level. It broke. Wave (c) is now the base case, no longer a scenario. Three forces have converged since last week. DXY climbed to 101.476, a 13-month high. US PMI Manufacturing 55.7 beat the 54.7 forecast -- the economy is strong, the hike case is intact. Risk-off intensified: VIX 19.40, NAS -3.1% as tech slumped on rate bets. The euro leg has no catalyst. ECB 2.00% neutral. Vujcic: "haven't discussed the neutral rate." DE10Y fell to 2.920%, widening the DE-US spread to -1.570%. The pipeline showed wrong numbers. CPI US: 2.4% (actual 4.2%). DE10Y: 2.99% (actual 2.920%). ECB: 2.50% (actual 2.00%). Real yield: 0.290%, not 2%. D1 structure: wave (c) running with clear sub-waves. Sub-1 ~1.157, sub-2 bounce, sub-3 running (~1.137). Expect sub-4 bounce then sub-5 target 1.119. Deeper: 1.113 then 1.079-1.073. Three scenarios: → Sub-5 to 1.119. Probability: 45% → Strong data + risk-off accelerates through 1.119 to 1.079. Probability: 25% → Surprise weak data, sub-4 bounces to 1.145-1.150, resumes. Probability: 20% Invalidation: daily close above 1.192. Warning: reclaim 1.141. Conviction: High Bear (upgraded from Med-High). Every channel bearish, no divergence. --- Intermarket Edge | Institutional Macro & Intermarket Analysis For informational purposes only. Not financial advice.

EURGBP - The PM Resigned and the Pair Didn't Flinch, a 1.86% Carry Crushes Political Risk at the 0.86110 Support

EURGBP - The PM Resigned and the Pair Didn't Flinch, a 1.86% Carry Crushes Political Risk at the 0.86110 Support

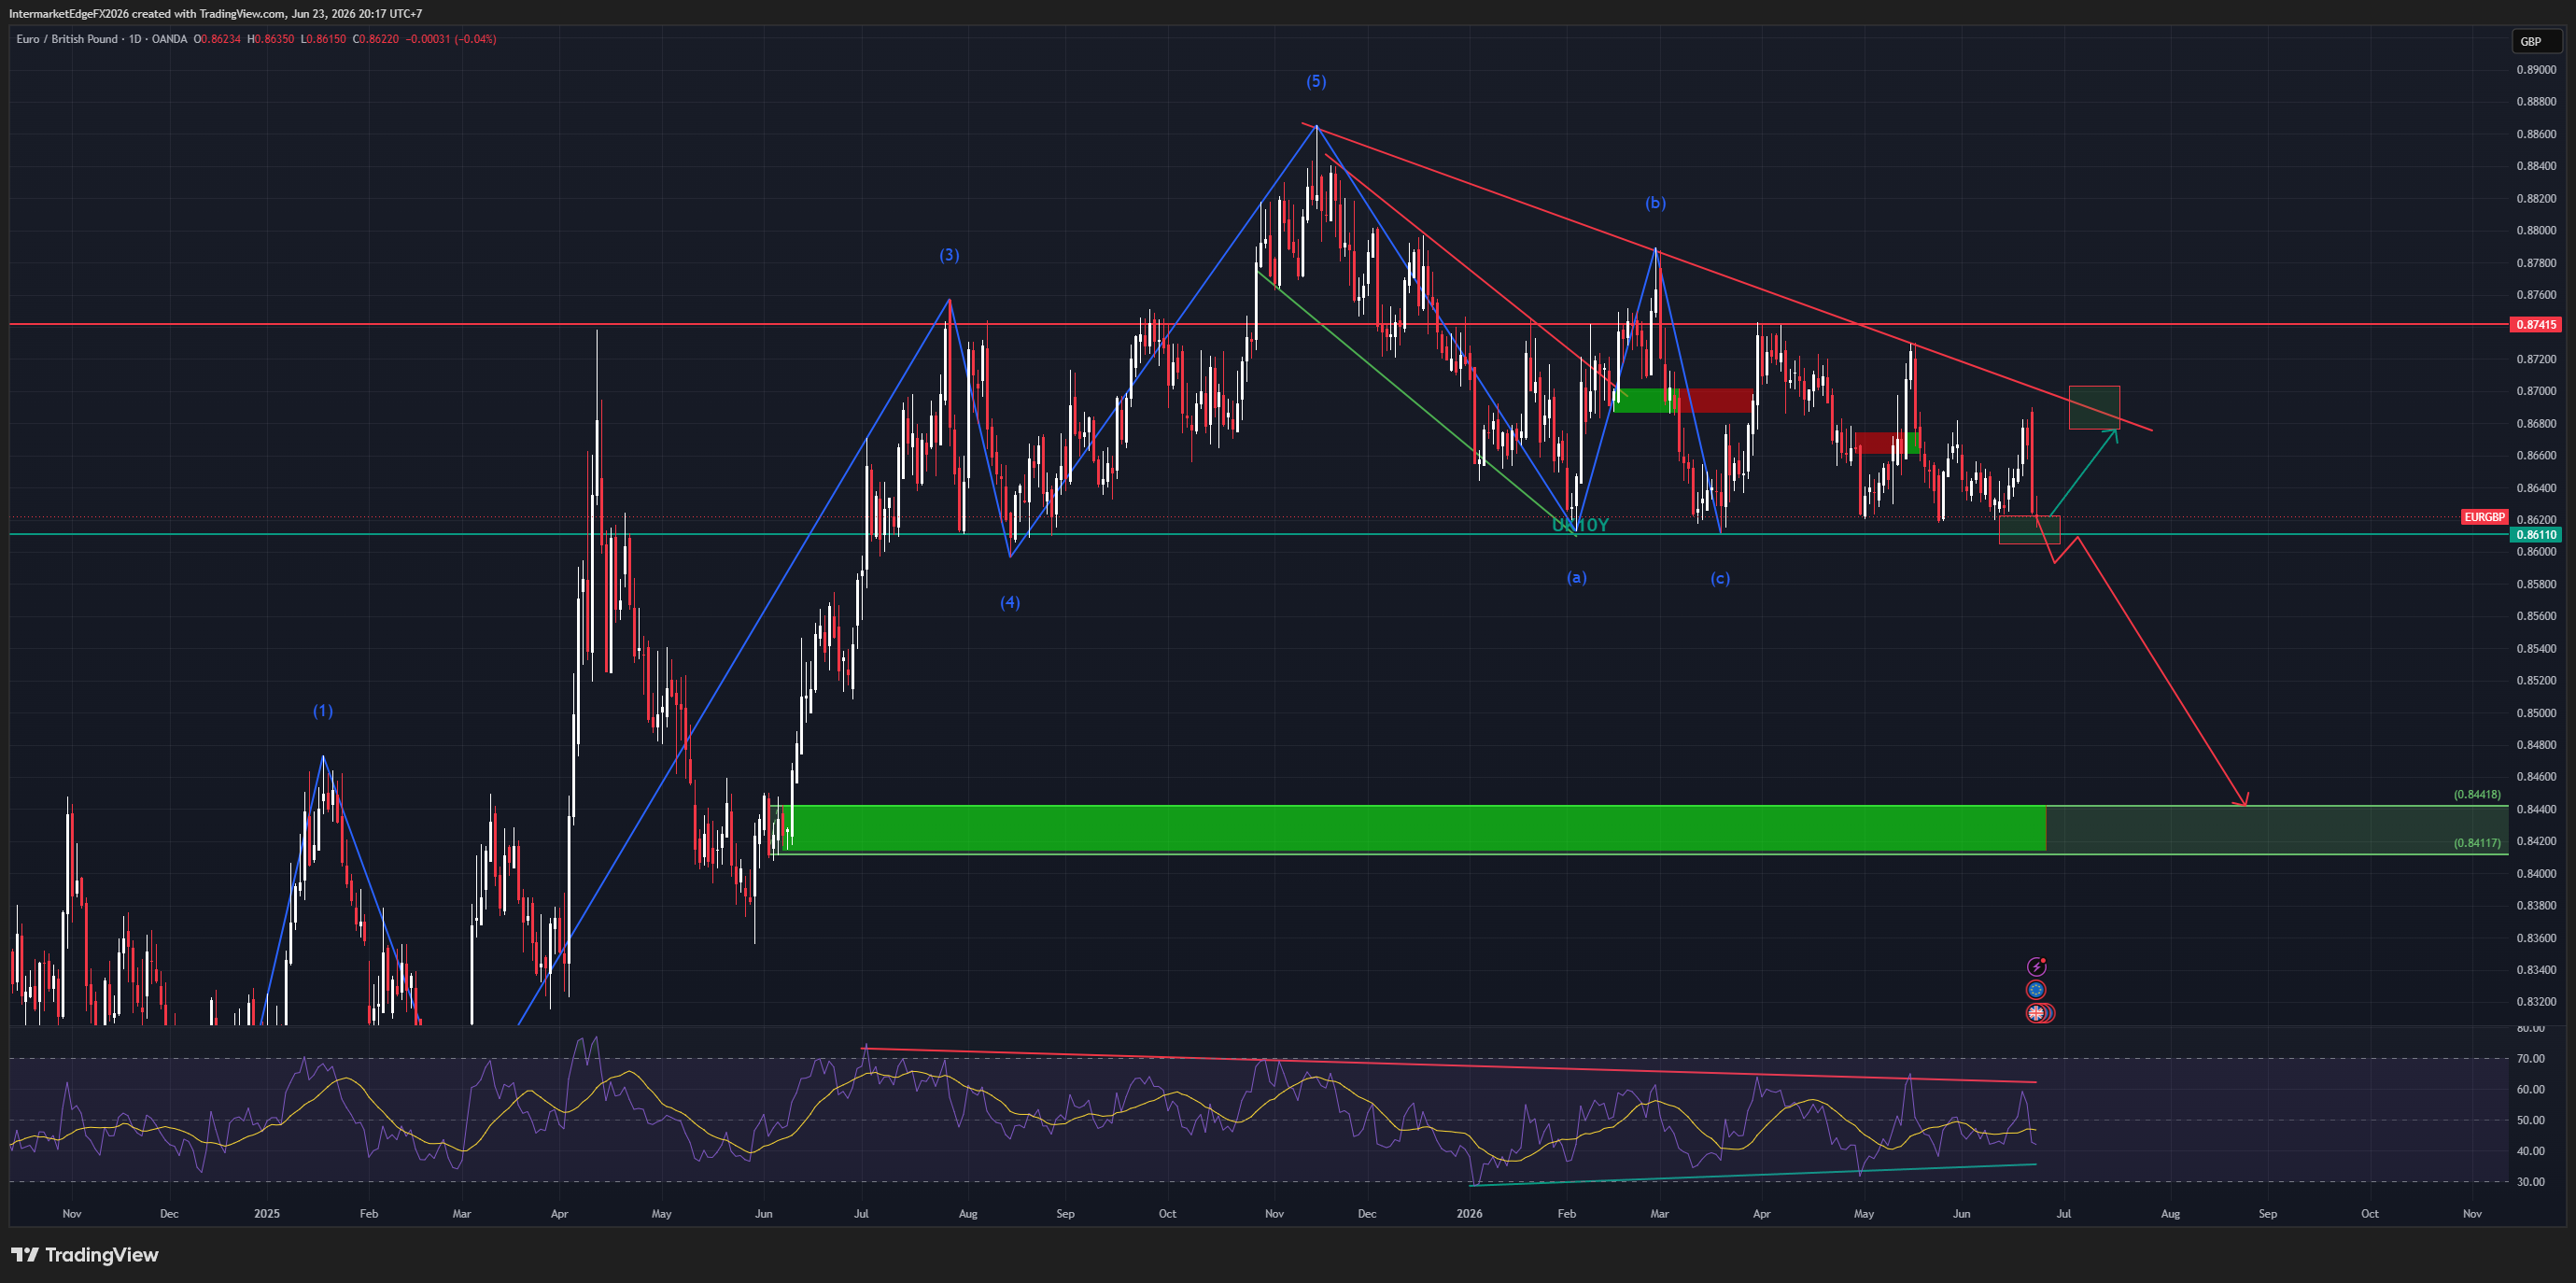
EURGBP 0.8622 | 1.86% carry crushes political risk | 23 June 2026 The UK Prime Minister just resigned. The pound should be weaker. EURGBP should be bouncing. But the pair barely moved, still pinned at the 0.86110 support. This is not an anomaly. This is the strongest bear signal of the week. Carry decides. UK10Y 4.770% above DE10Y 2.910% by 1.860 percentage points. The spread is nearly identical to last week (1.862%). Starmer's exit did not narrow carry, and when a pair doesn't react to a PM-level shock, the structural force is overwhelming. EUR is not strong enough to push it higher either. EURUSD 1.1392 falling. ECB neutral at 2.00%. Lane/Lagarde rhetoric mixed. The pipeline showed wrong numbers. UK10Y: 4.50% (actual 4.770%). DE10Y: 2.99% (actual 2.910%). ECB: 2.50% (actual 2.00%). D1 structure: descending channel intact from the 0.888 top. Wave (c) testing the 0.86110 support. A break opens 0.84418 then 0.84117. Invalidation: 0.87415. Three scenarios: → Break 0.86110, wave (c) to 0.84418 then 0.84117. Probability: 40% → Hold 0.86110, carry pins, range 0.860-0.865. Probability: 25% → Political crisis escalates, UK yields drop, delayed bounce to 0.87415. Probability: 20% The tell: EURGBP didn't react to a PM resignation. The 1.86% carry controls this pair. As long as it holds, the downside has the higher probability. Conviction: Medium-High Bear, increased versus last week. --- Intermarket Edge | Institutional Macro & Intermarket Analysis For informational purposes only. Not financial advice.

Stay in the loop

Get notified about new research, macro insights, and market analysis.

InterMarketEdge

© 2026 InterMarketEdge. Financial intelligence for inter-market traders.