Tag: DXY — InterMarketEdge

Tag: DXY

EURUSD W41: Fiscal Stress Weighs, but the Entry Case Remains Unclear

EURUSD W41: Fiscal Stress Weighs, but the Entry Case Remains Unclear

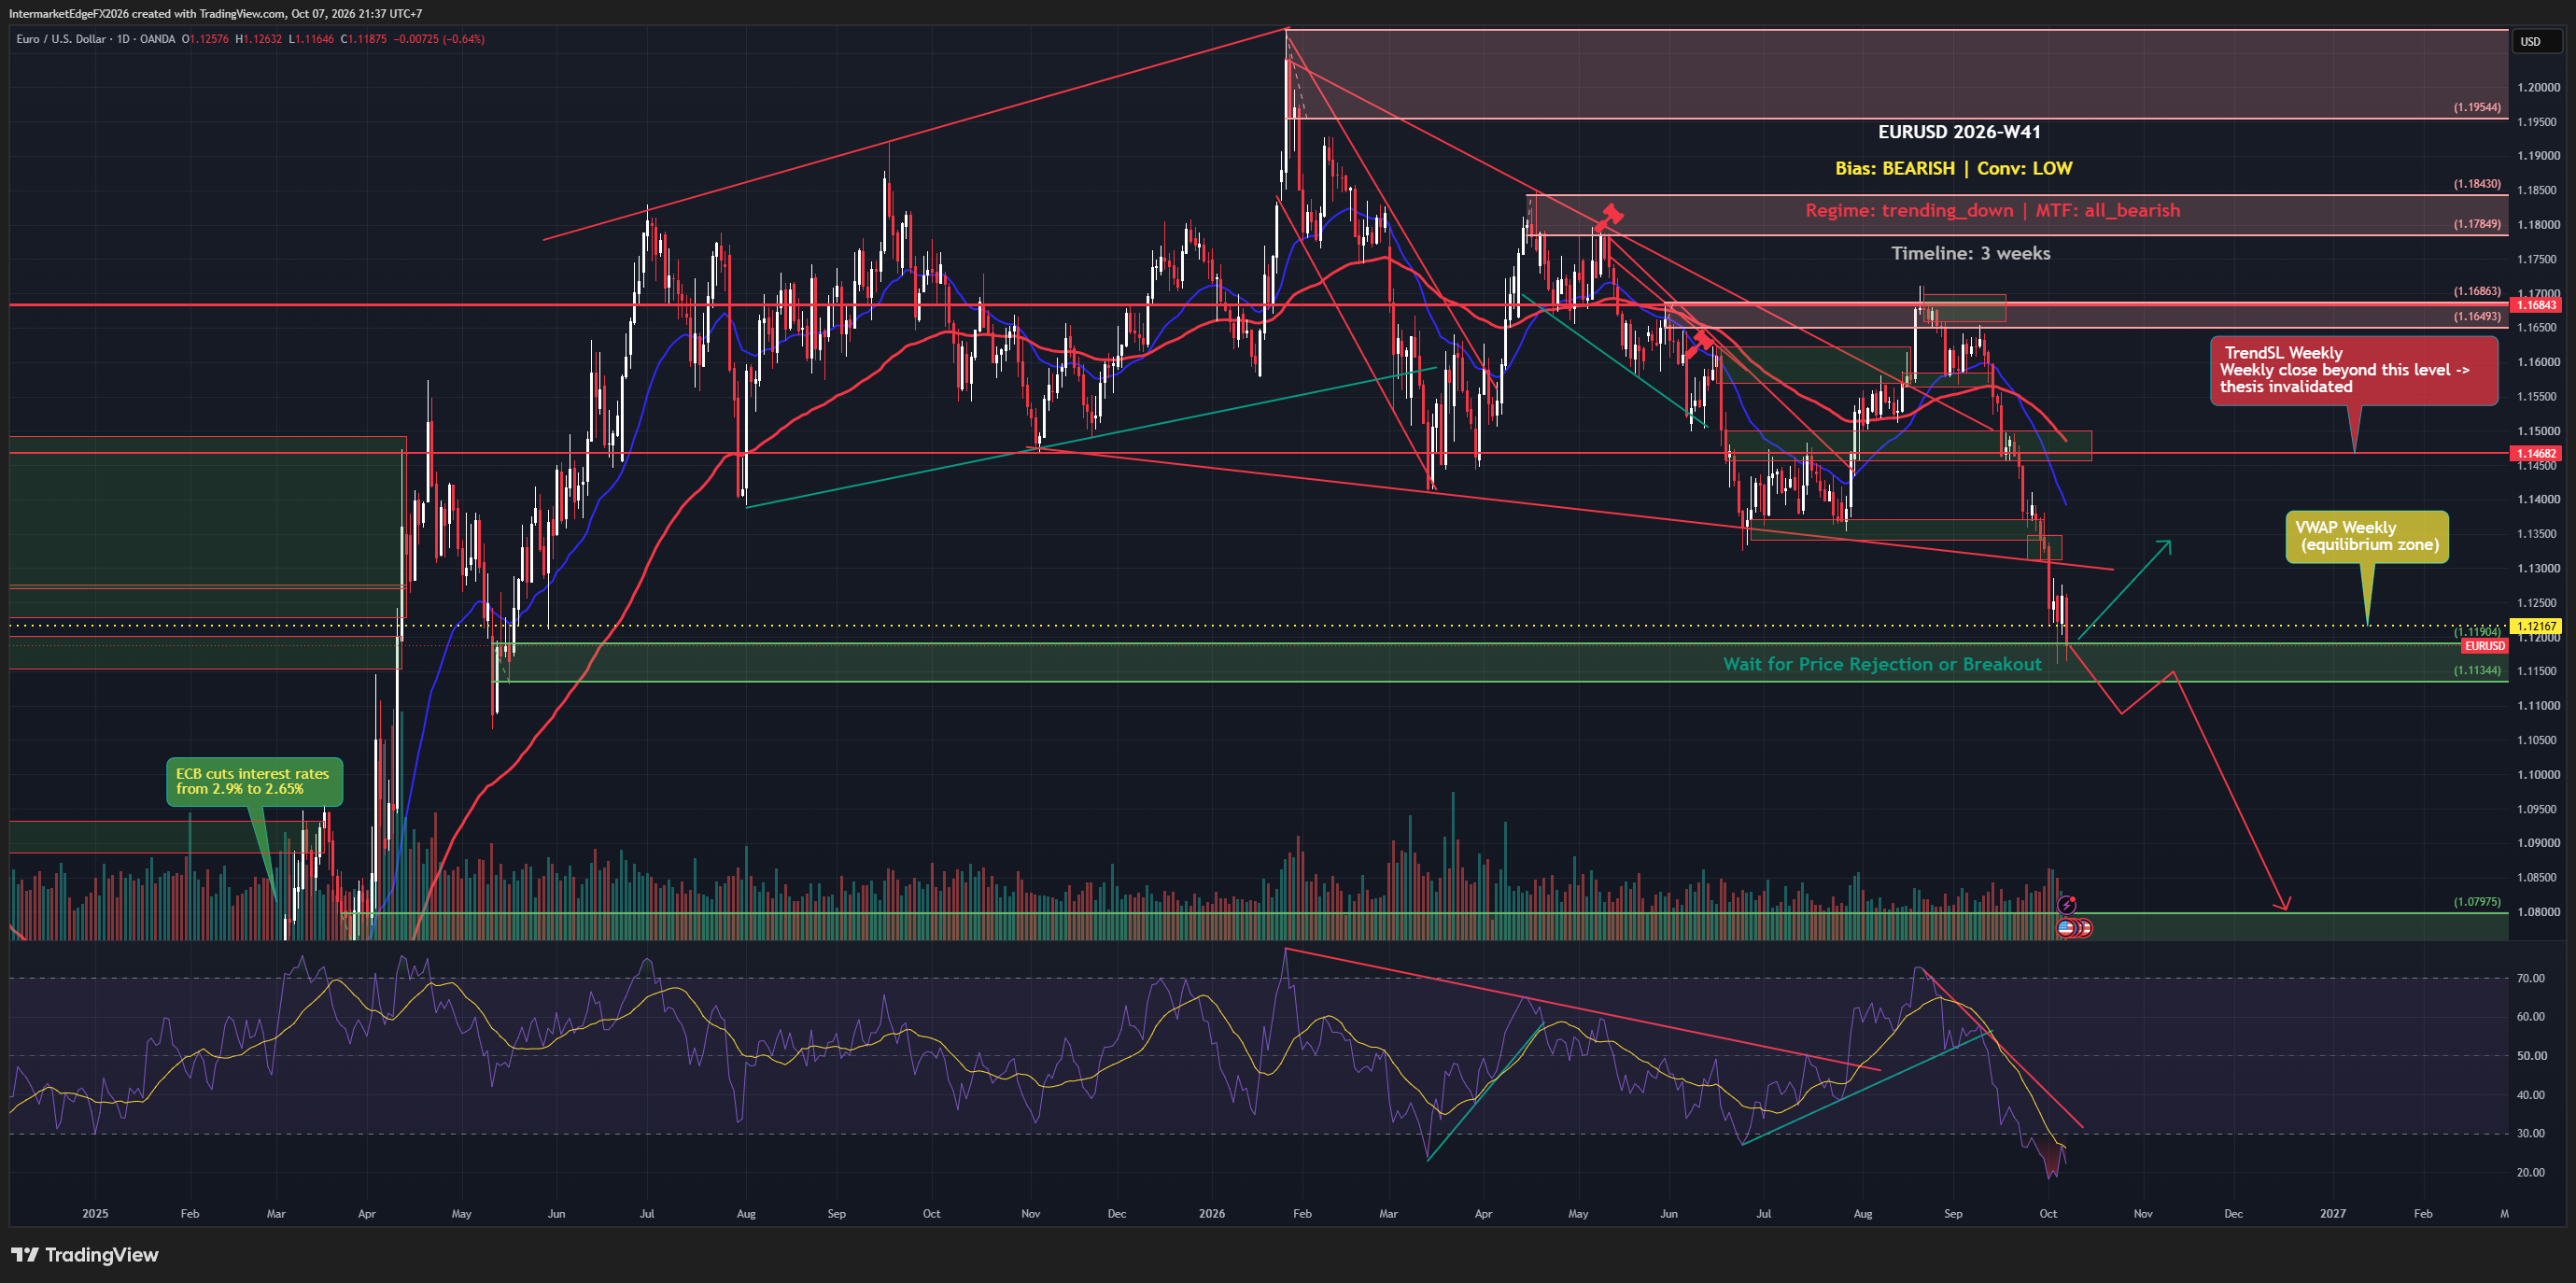
EURUSD W41 | Fiscal pressure, uncertain entry timing At 14:24 UTC on October 7, 2026, EURUSD was 1.11881 (MT5 EURUSD.sml:1m), below weekly VWAP 1.12167 and weekly TrendSL 1.14682. The broader trend points downward, but positive short-term signals reduce agreement. The bearish view has low conviction; standing aside avoids forcing a fresh entry. If price sustains above 1.12167, momentum would work against the bearish view and call for a short-side risk review. Only a completed weekly close above 1.14682 would invalidate the bearish structure. Both conditions remain pending at the quoted observation. FXSSI collected at 14:24:09 UTC on October 7: 77% Buy / 23% Sell. This is collection time. The broker retail sample does not represent the entire FX market or provide a standalone entry signal. Watch the dollar, comparable US-euro-area yields and French-German sovereign spreads. Related French fiscal headlines are not independent bearish confirmations. ForexFactory lists Fed minutes at 18:00 UTC on October 7 (01:00 GMT+7, October 8), after this snapshot. This secondary calendar is not officially verified. The minutes describe an earlier meeting, not its response to later data. Three weeks is a review horizon, not a target deadline. Prices are dated references, not live quotes. Intermarket Edge | Institutional Macro & Intermarket Analysis For informational purposes only. Not financial advice.
DXY W41: Softer US Jobs Meet a Weaker Euro

DXY W41: Softer US Jobs Meet a Weaker Euro

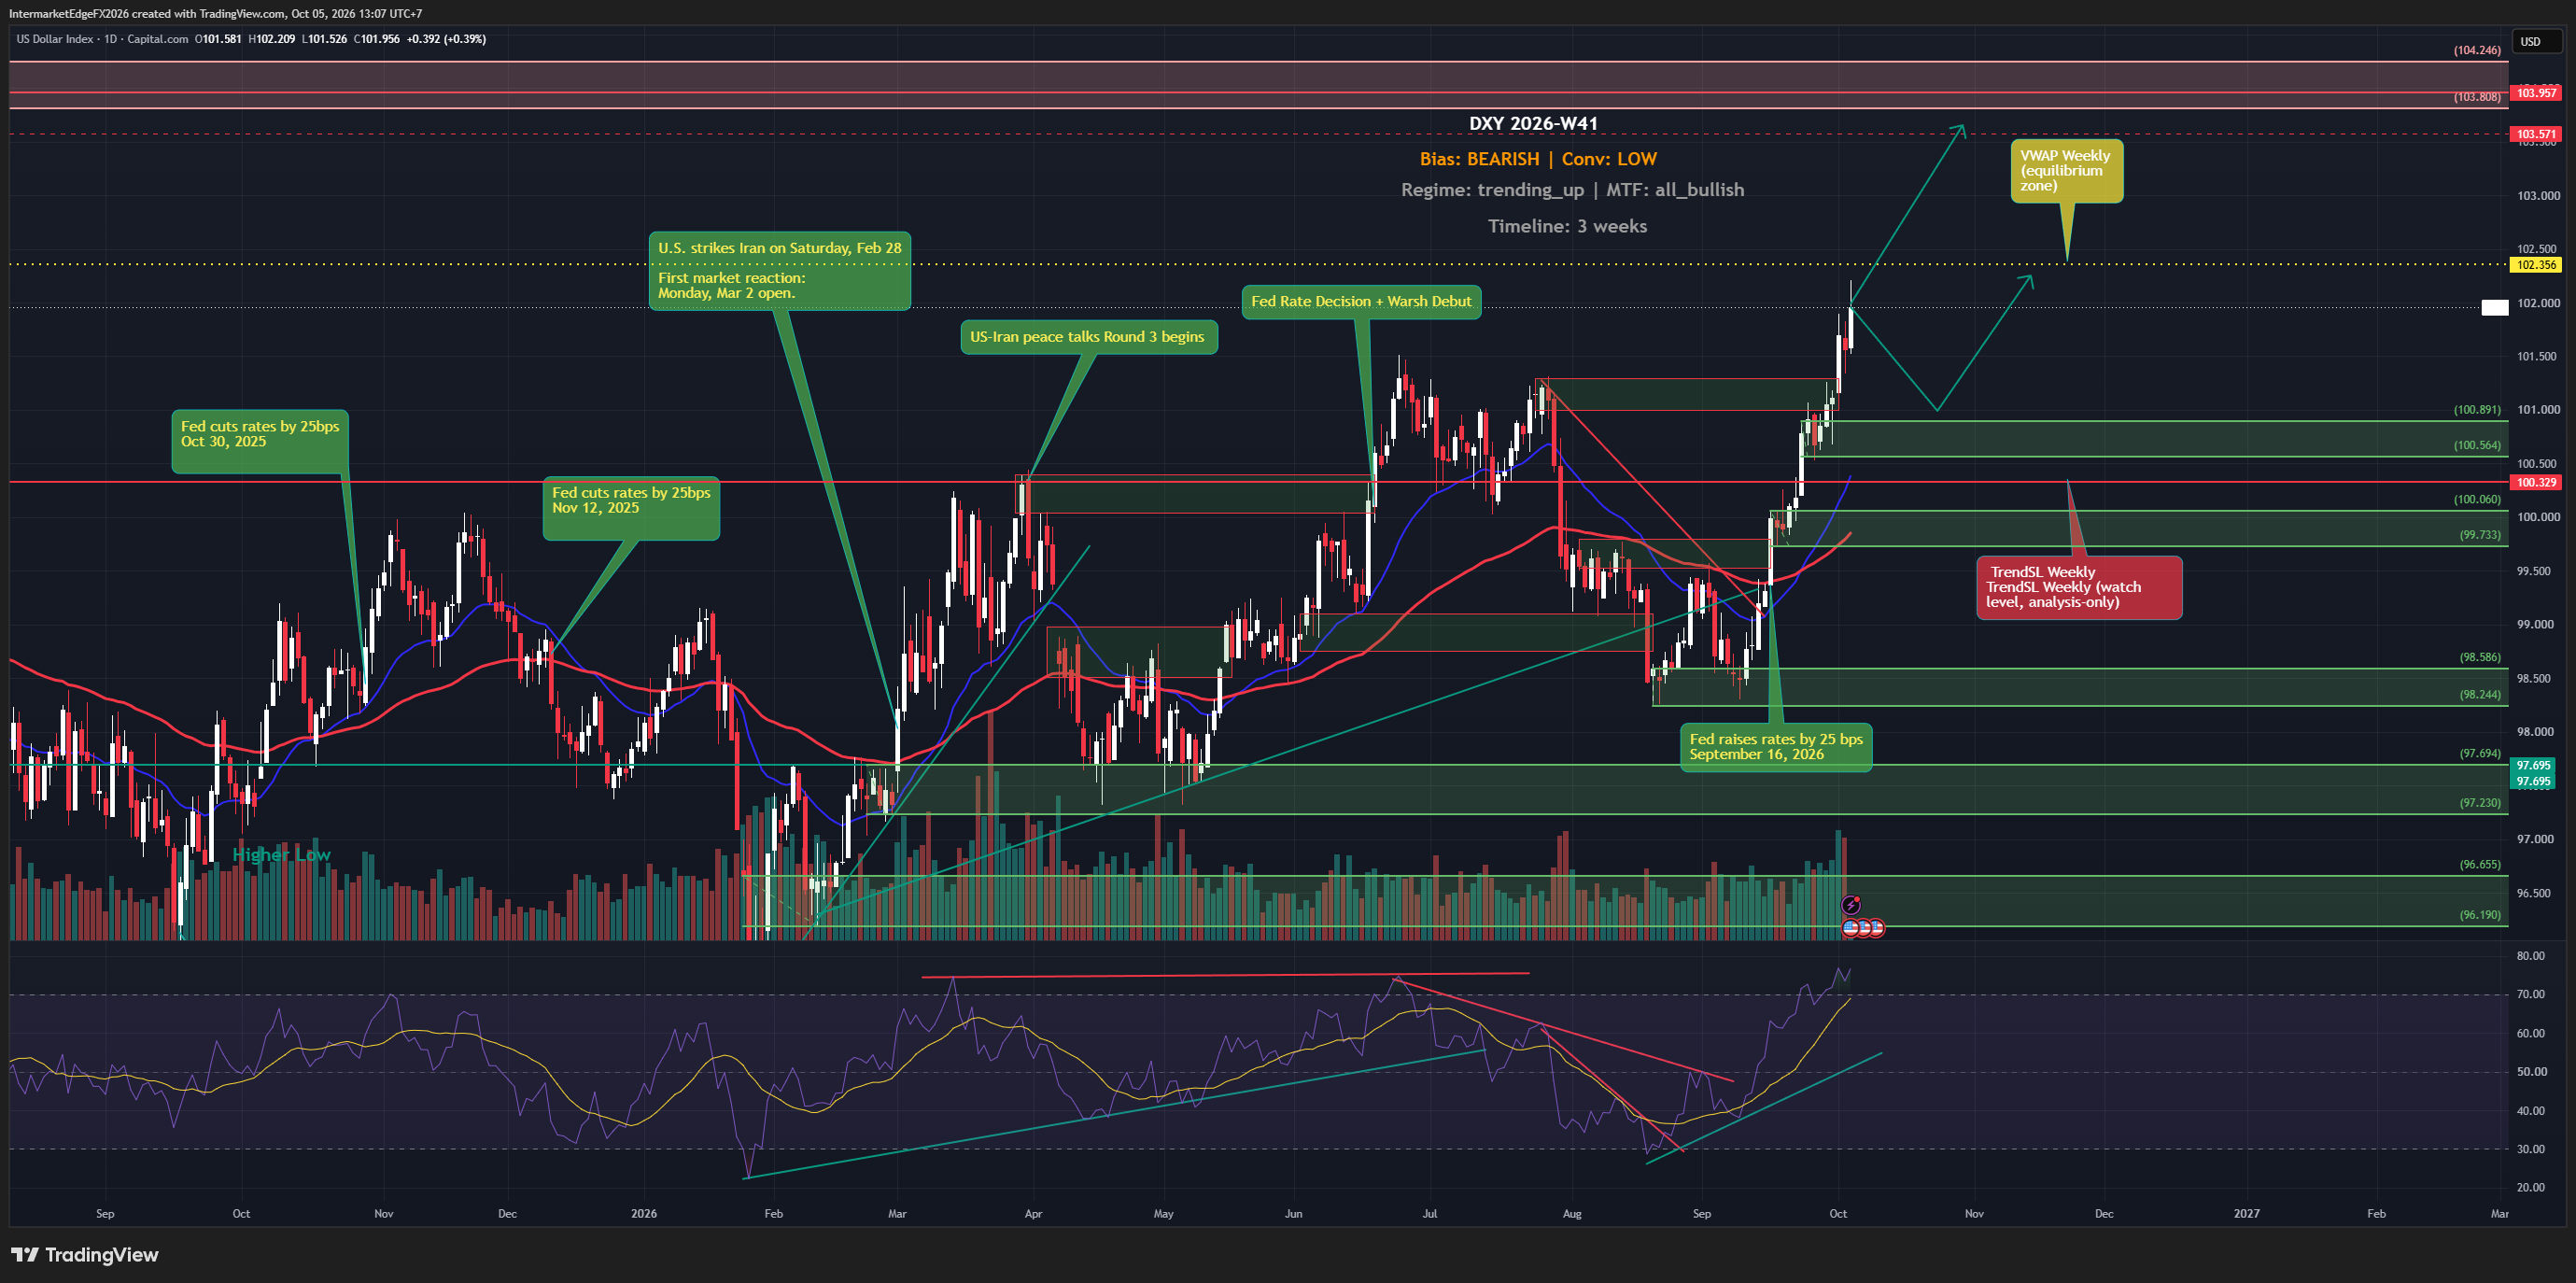
Weaker US hiring has reduced expectations of an October Fed increase, while French fiscal concerns are weighing on the euro. Those forces pull DXY in opposite directions: a less supportive US policy outlook versus weakness in the index's largest currency component. At 05/10/2026 05:55 UTC, DXY was 102.350 (source: yfinance:DX-Y.NYB:1m). Price was effectively at weekly VWAP 102.347 and above weekly TrendSL 100.329. Near-term momentum is balanced around the weekly average; a decisive move is not established. The broader trend assessment remains upward across daily, weekly and monthly charts at thesis generation. The bearish view therefore carries low confidence over the three-week horizon. Two references matter: • Weekly VWAP is a momentum reference, not an automatic structural break. A sustained recovery on its higher side would work against the bearish view. • Price is already above weekly TrendSL. A completed weekly close below 100.329 would provide bearish structural confirmation. That condition remains pending; an intraday move cannot activate it. -- Intermarket Edge

EURUSD Week W40-2026: Dollar Posts Its Largest September Gain at the Euro's Expense, But the Real Trap Is What Comes Next

EURUSD Week W40-2026: Dollar Posts Its Largest September Gain at the Euro's Expense, But the Real Trap Is What Comes Next

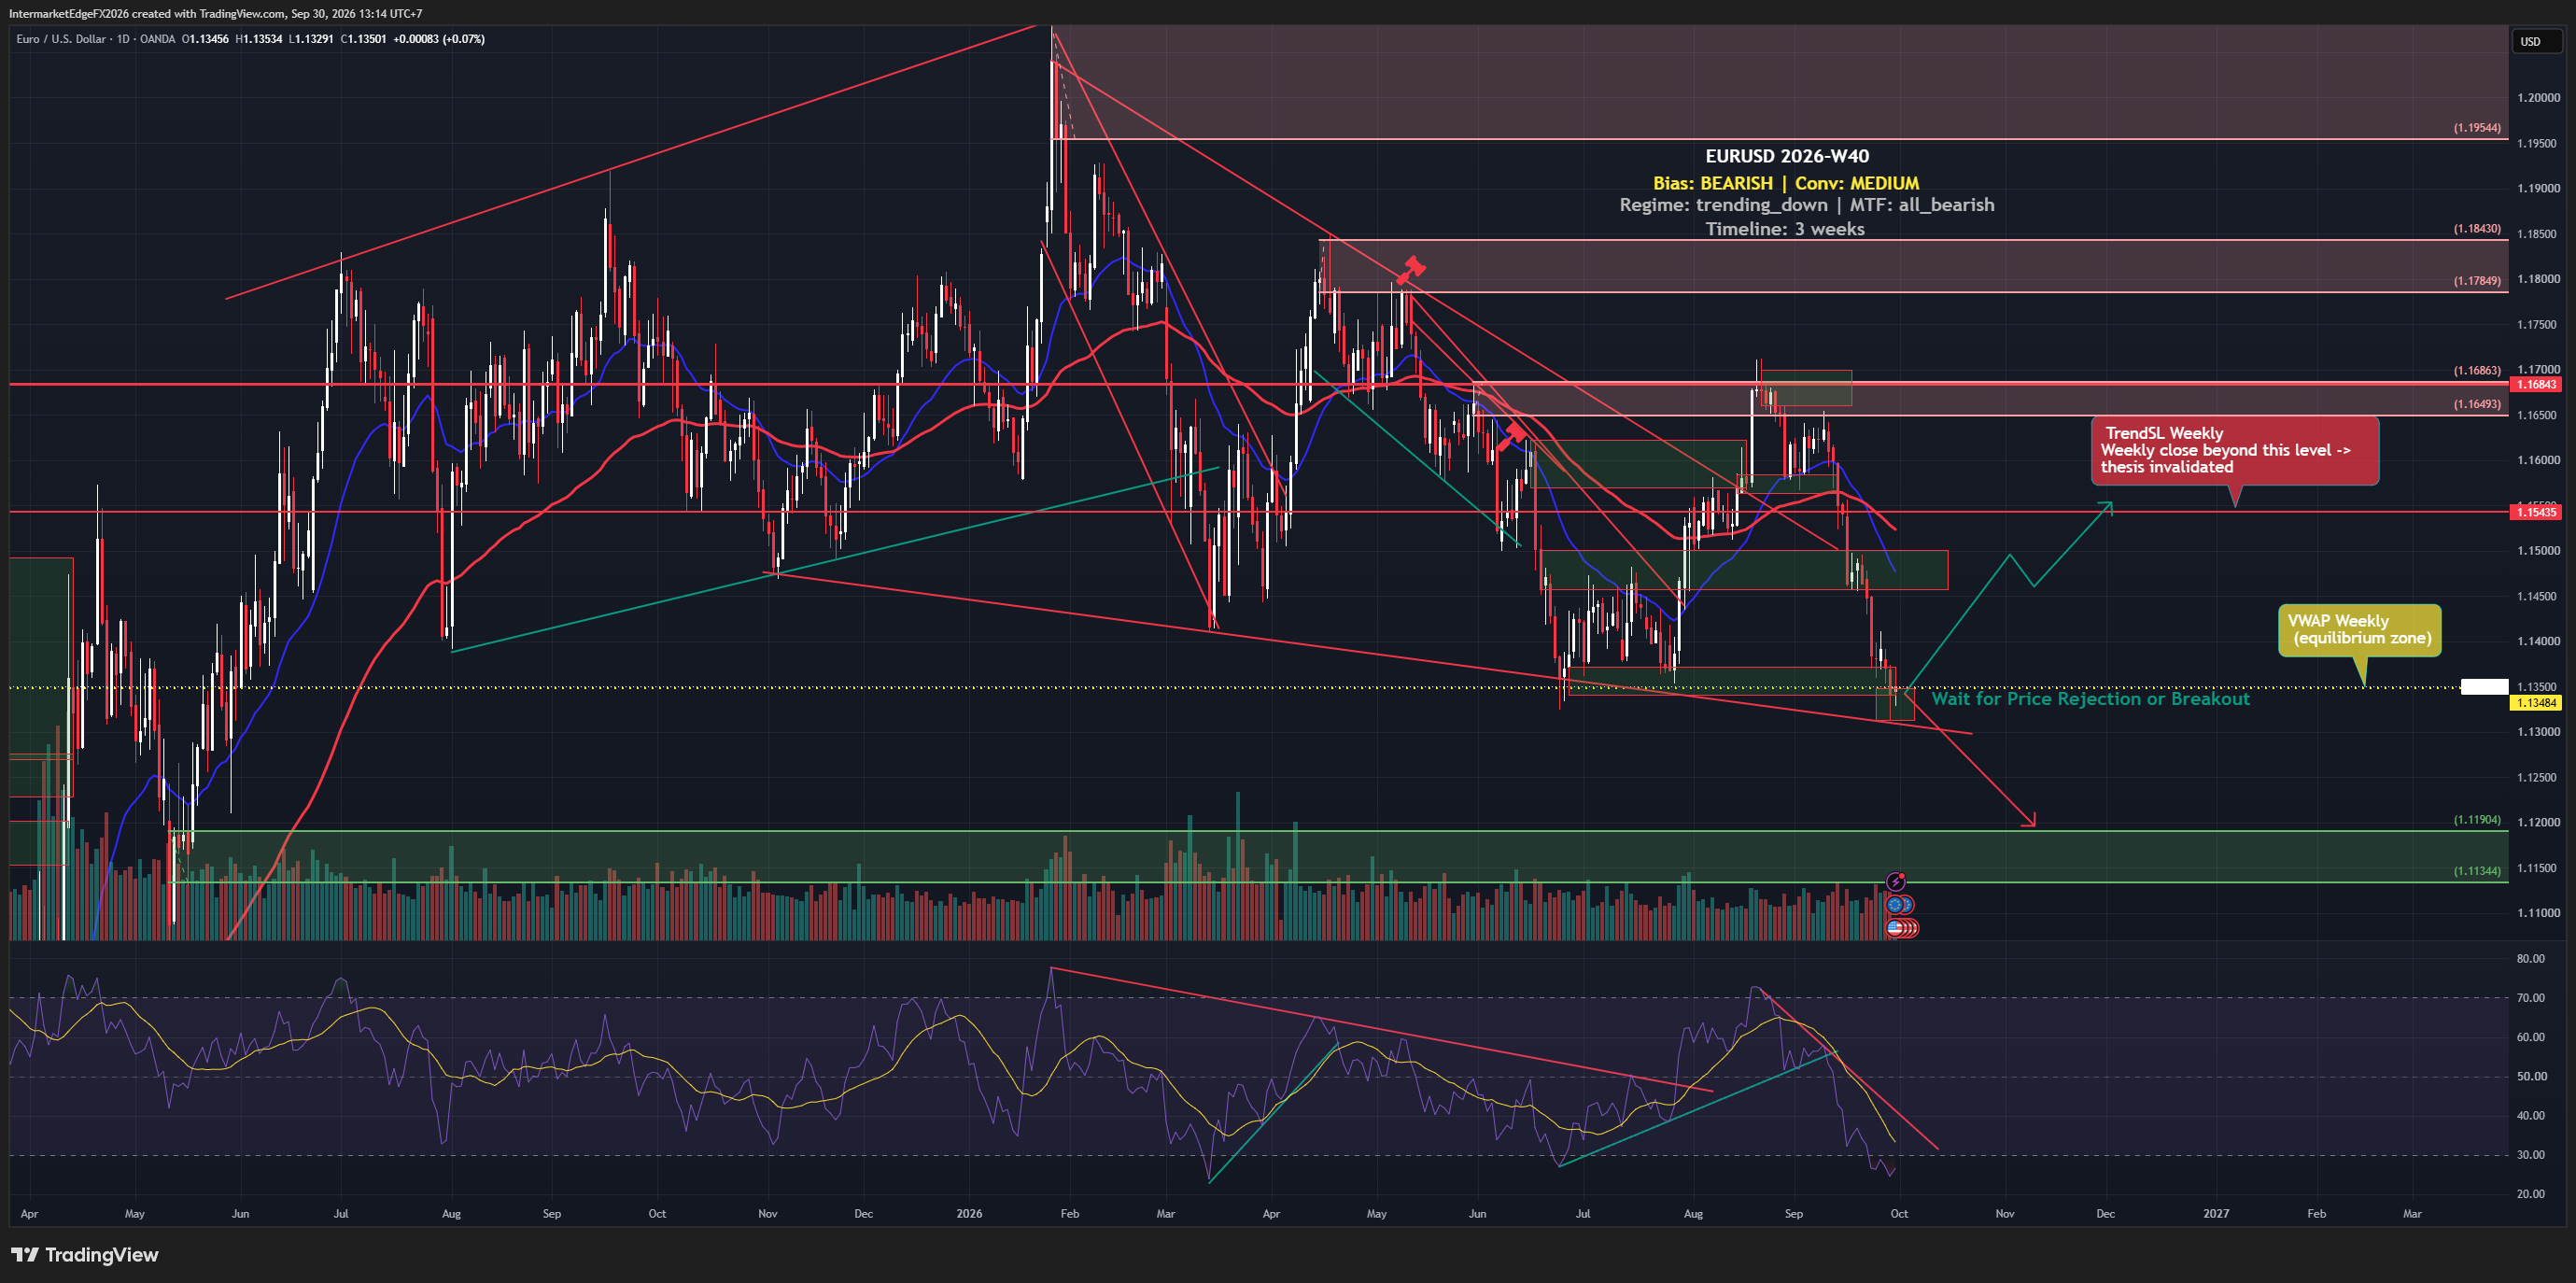
EURUSD is trading at 1.134 as of Wednesday, 30 September 2026, capping a month that Reuters confirms was the dollar's largest September gain, predominantly at the euro's expense. New York Fed President Williams has left the door open for one more rate hike this year, and with US 10-year real yields at 2.9%, the interest-rate math continues to favor the dollar structurally. The trend is down across every timeframe, but signal conflicts mean the path isn't as clean as the headline suggests. The bearish case on EURUSD rests primarily on the rate differential and the Fed's demonstrated willingness to keep it wide. When one central bank is signaling additional tightening while the other faces structurally slower growth and a different inflation profile, the currency on the higher-yield side tends to attract demand, and that demand compounds over weeks, not sessions. Reuters confirming the dollar's outsized September gain at the euro's expense is not just a data point; it's confirmation that the macro argument has already been expressing itself in price. That said, this is a medium-conviction view, not a high-conviction one, and traders should weigh that carefully. The conflict worth naming directly: price action signals and COT positioning, which reflects the aggregate stance of large futures traders, though the specific report week and net-position figures are not available here, so treat it as directional context rather than a precise citable stat, are both leaning bullish. When the macro framework points one direction and the market's actual positioning leans the other, the overall call carries more uncertainty than a clean trend setup would. The retail picture adds a contrarian lean: 72% of retail EURUSD accounts tracked by FXSSI as of 30 September are net long, and historically, when retail crowds are this lopsided on a major pair, it tends to lean against their position. -- Intermarket Edge

DXY Week W40-2026: Every Timeframe Points Up, Yet the Framework Calls Bearish — Who Is Wrong?

DXY Week W40-2026: Every Timeframe Points Up, Yet the Framework Calls Bearish — Who Is Wrong?

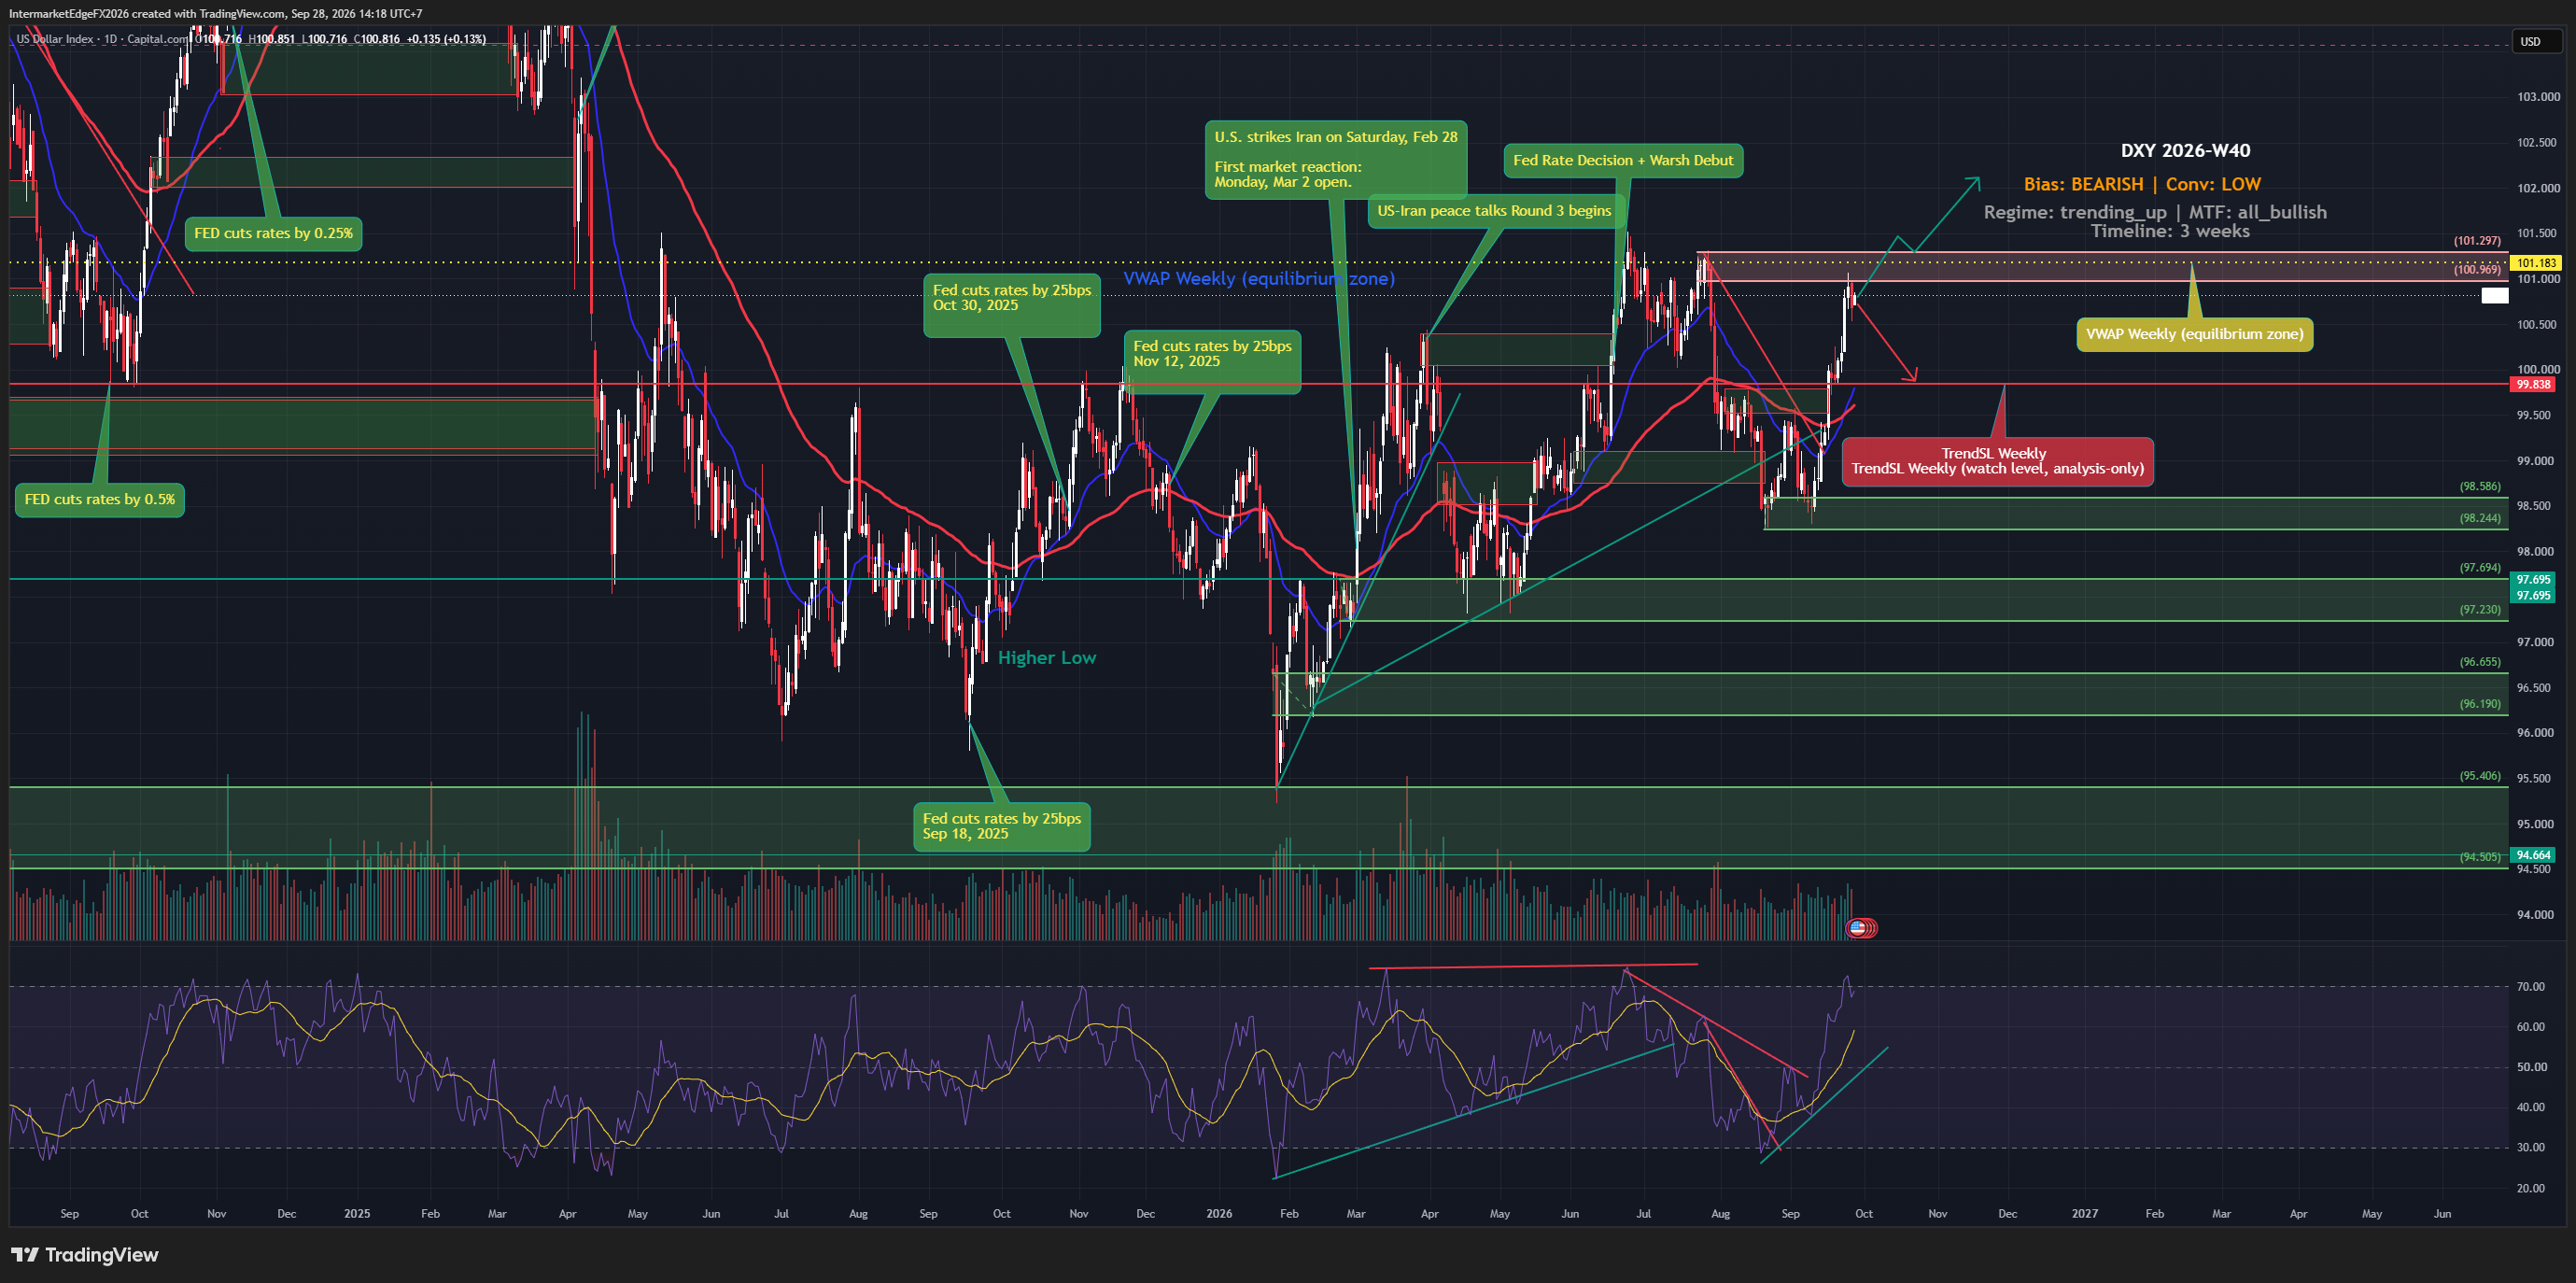
DXY W40: bullish structure challenges a low-conviction bearish bias. The framework remains bearish over a three-week horizon, but daily, weekly, and monthly technical signals are bullish. At 07:01 UTC on Monday, September 28, DXY was 101.188, testing the weekly VWAP area at 101.183 and remaining above the weekly TrendSL at 99.838. Reuters reports that US-Iran tensions are lifting oil while hawkish Fed expectations and Treasury yields are rising. That mix currently supports the dollar counter-case. The COT information in the brief lacks the report week, release date, CFTC code, and net-position figure, so it is directional context only and cannot confirm a current flow or trade trigger. A sustained reclaim of 101.183 would add near-term pressure against the bearish thesis. A completed weekly close below 99.838 would provide the first bearish structural confirmation; that condition remains pending. Core PCE and Final GDP are scheduled for September 30, followed by payrolls, earnings, and unemployment data on October 2, according to ForexFactory. These releases may change rate expectations, but their outcomes are still unknown. The practical decision is to wait for price or macro evidence to resolve the conflict rather than treat the bearish label as a standalone trade signal. Reference price: 101.188 at 07:01 UTC on September 28, 2026; source yfinance:DX-Y.NYB:1m. Educational content only.

DXY W39: Price Strength Challenges the Bearish Macro View

DXY W39: Price Strength Challenges the Bearish Macro View

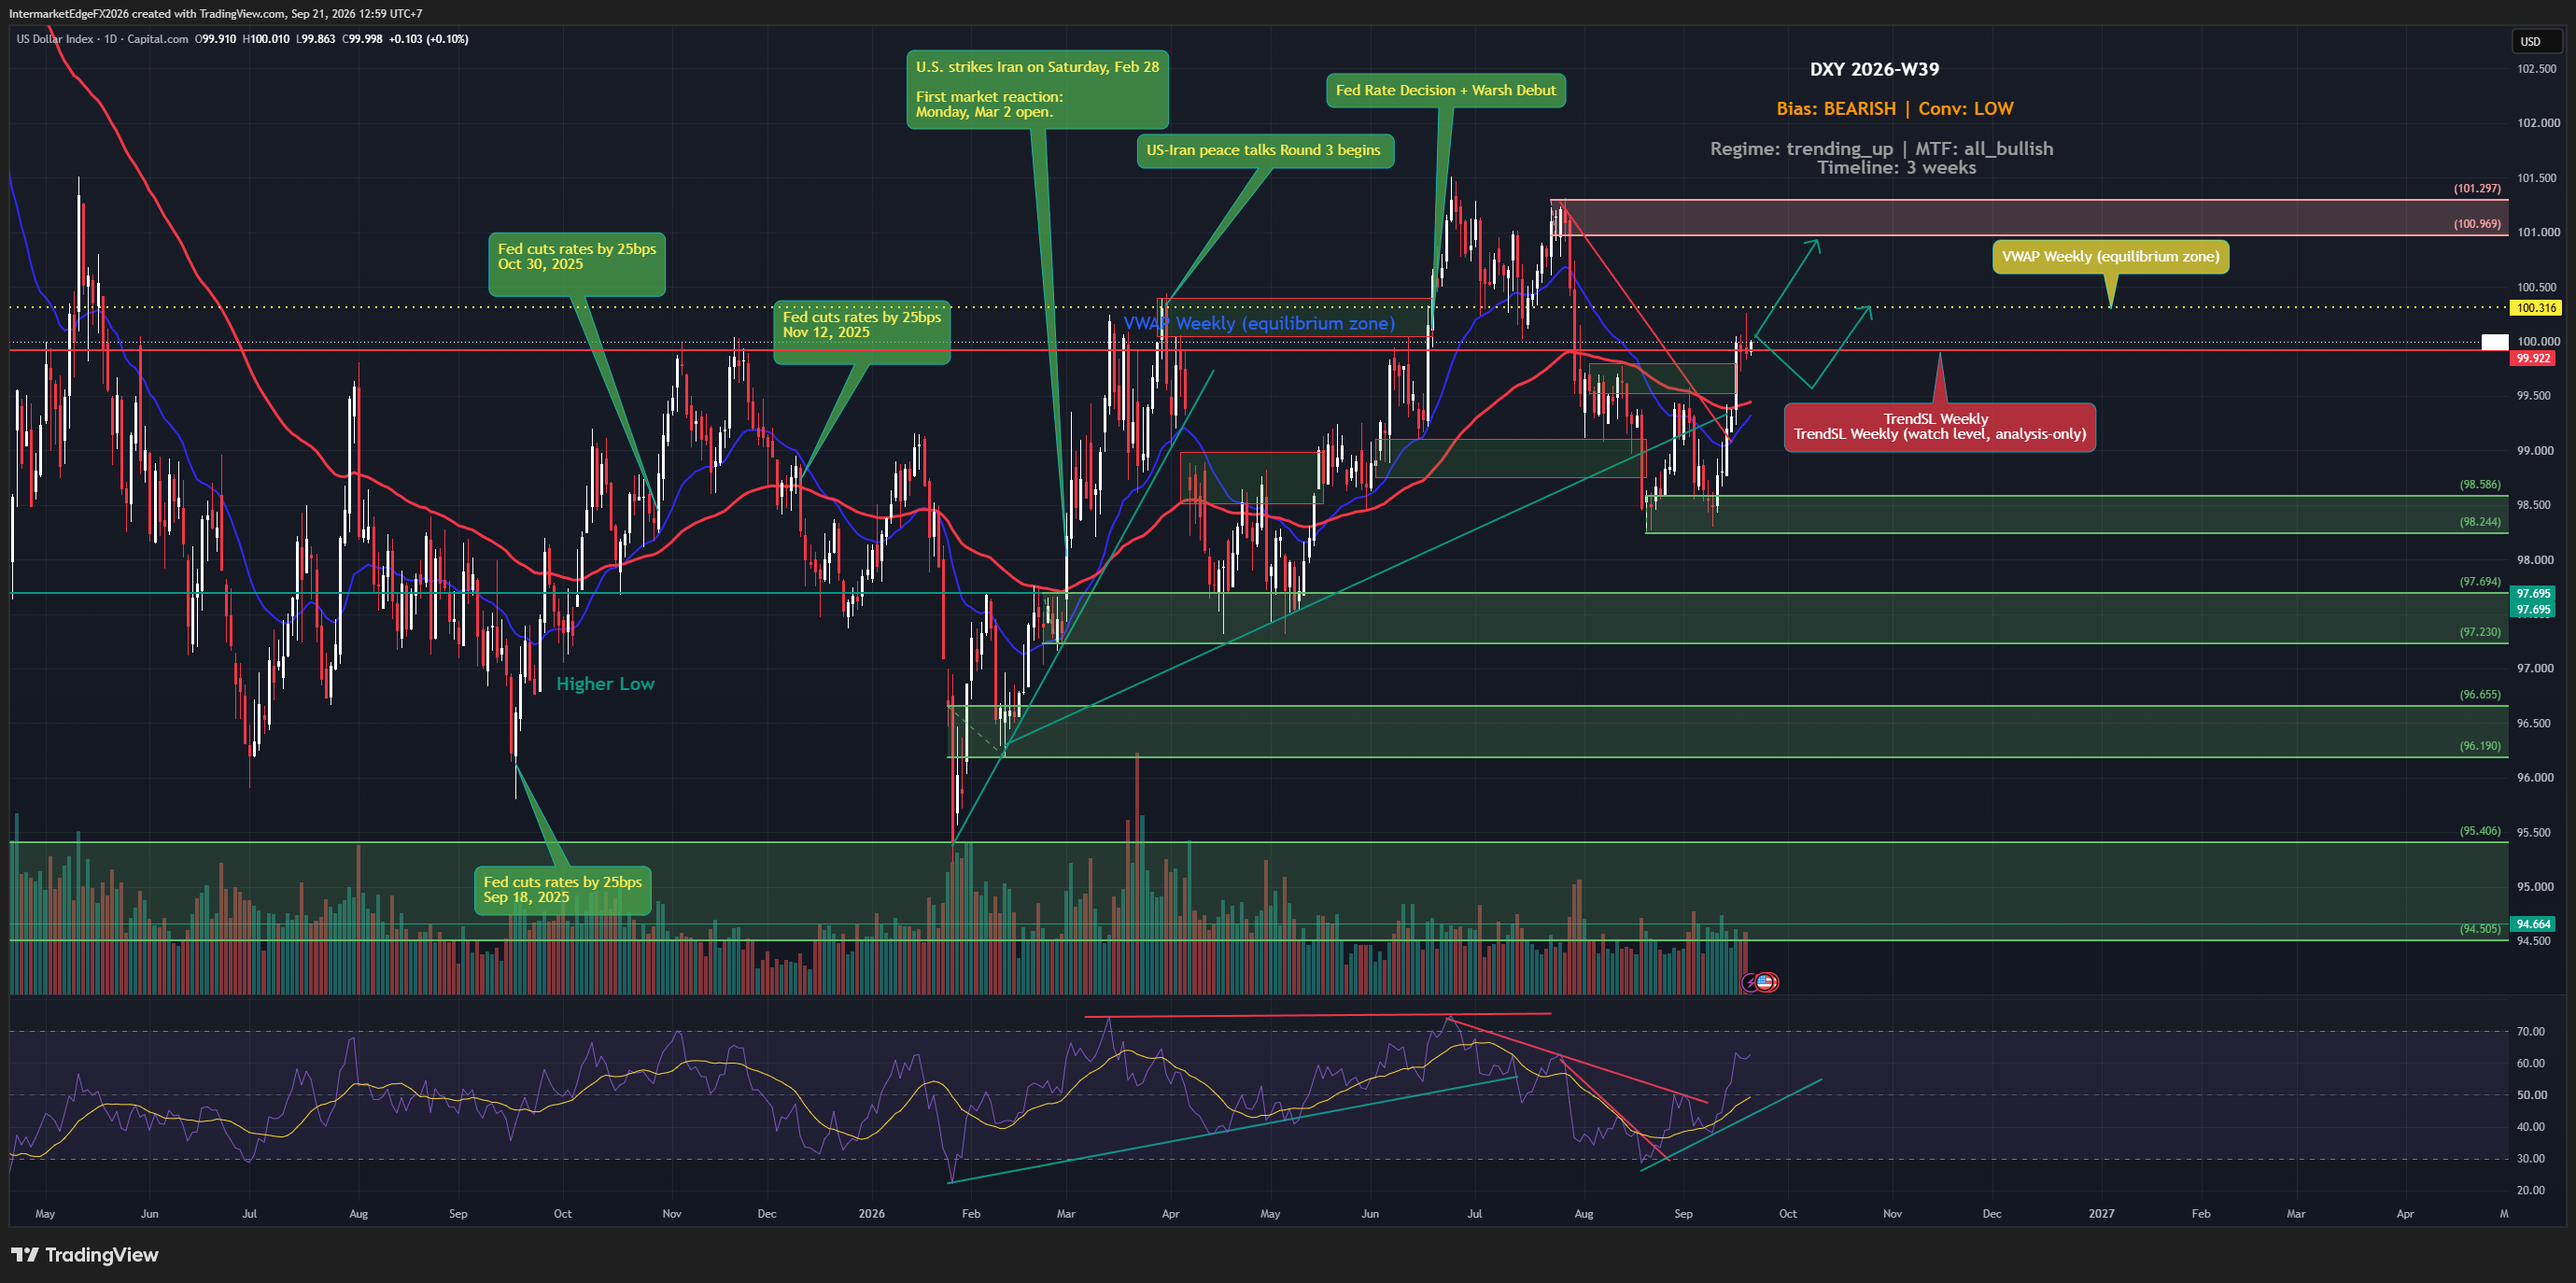
DXY W39: NEXUS leans bearish with low confidence over three weeks, while daily, weekly and monthly technical readings remain upward. At 100.344, price is above weekly VWAP 100.316 and weekly TrendSL 99.922. The watch condition against the bearish thesis is already active; one quote does not establish a sustained breakout. Schmid's inflation message supports policy restraint, while weaker US manufacturing provides a counterweight. The BOJ increased rates to 1.25% on 18 September. Reported Japanese rate checks are not confirmed intervention. Sustained oil-price relief could ease part of the inflation pressure. If DXY closes the week below TrendSL 99.922, that would provide bearish structural confirmation. It has not occurred. Continued strength above VWAP would challenge the bearish view. Wait for clearer evidence. Reference: DXY 100.344 at 05:46 UTC, 21 September 2026; source yfinance:DX-Y.NYB:1m. This is a timestamped reference, not a live quote at reading time. Weekly VWAP 100.316 and TrendSL 99.922 are the stored thesis levels. Intermarket Edge | Educational analysis.

DXY Week W38-2026: Inflation Data Pushes Fed Hike Bets Higher, But the Dollar Sits Trapped Between Two Levels

DXY Week W38-2026: Inflation Data Pushes Fed Hike Bets Higher, But the Dollar Sits Trapped Between Two Levels

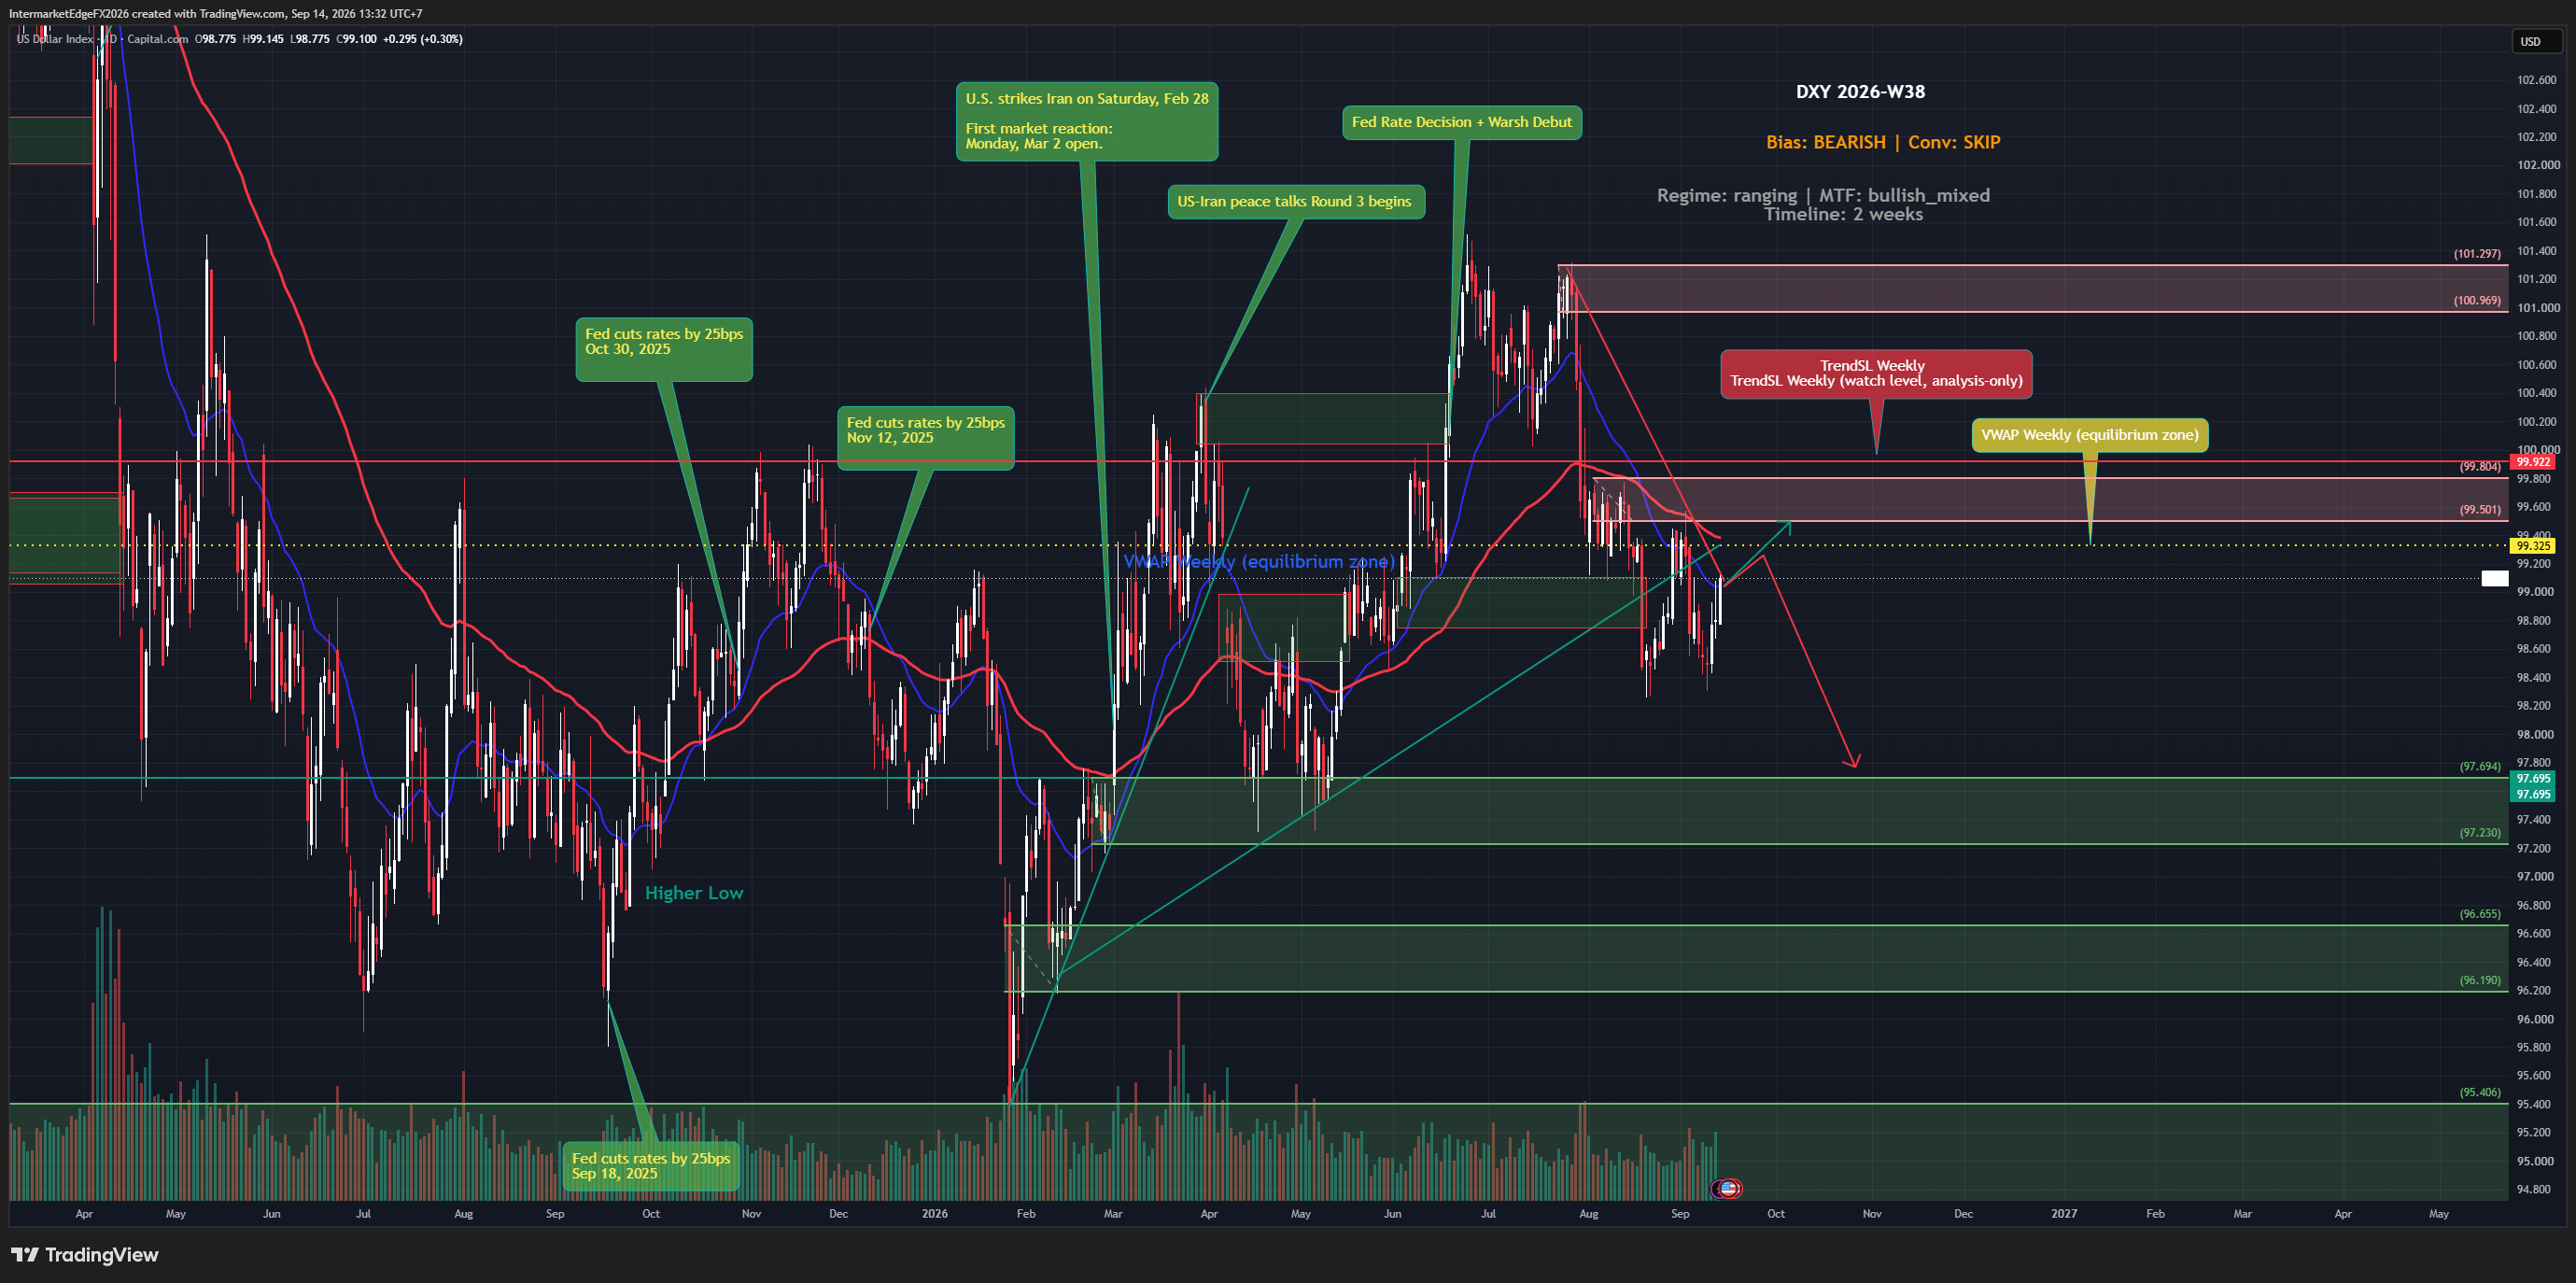
DXY is trading at 99.389 as of Monday, 14 September 2026 at 06:07 UTC. Price is above weekly VWAP at 99.325 and below weekly TrendSL at 99.922. Short-term momentum therefore runs against the bearish thesis, while the higher-time-frame bearish structure has not been invalidated. The macro picture is mixed ahead of the September 15-16 FOMC meeting. Inflation and a 2.55% US 10-year real yield support the dollar, but consumer sentiment at 47.8, rising inflation expectations and higher oil-shipping costs create a stagflationary policy problem. The US liquidity proxy increased by about $96.7 billion over four weeks, adding a modest structural headwind for USD. COT positioning points to stretched speculative dollar longs, although the brief lacks the exact report week and net-position figure. FXSSI retail positioning is balanced, with a derived DXY component reading near 53.5% long and 46.5% short. VIX and CNN Fear & Greed provide equity risk context rather than an FX signal. The weekly decision is to stand aside. A weekly close above TrendSL at 99.922 would invalidate the bearish framework. Price is already above VWAP, so sellers do not have short-term momentum confirmation. A sustained loss of VWAP support after FOMC would strengthen the bearish case. -- Intermarket Edge

EURUSD Week W37-2026: Price Reclaims 1.16274 VWAP as ECB and US CPI Collide, Bearish Case Loses Its Technical Footing

EURUSD Week W37-2026: Price Reclaims 1.16274 VWAP as ECB and US CPI Collide, Bearish Case Loses Its Technical Footing

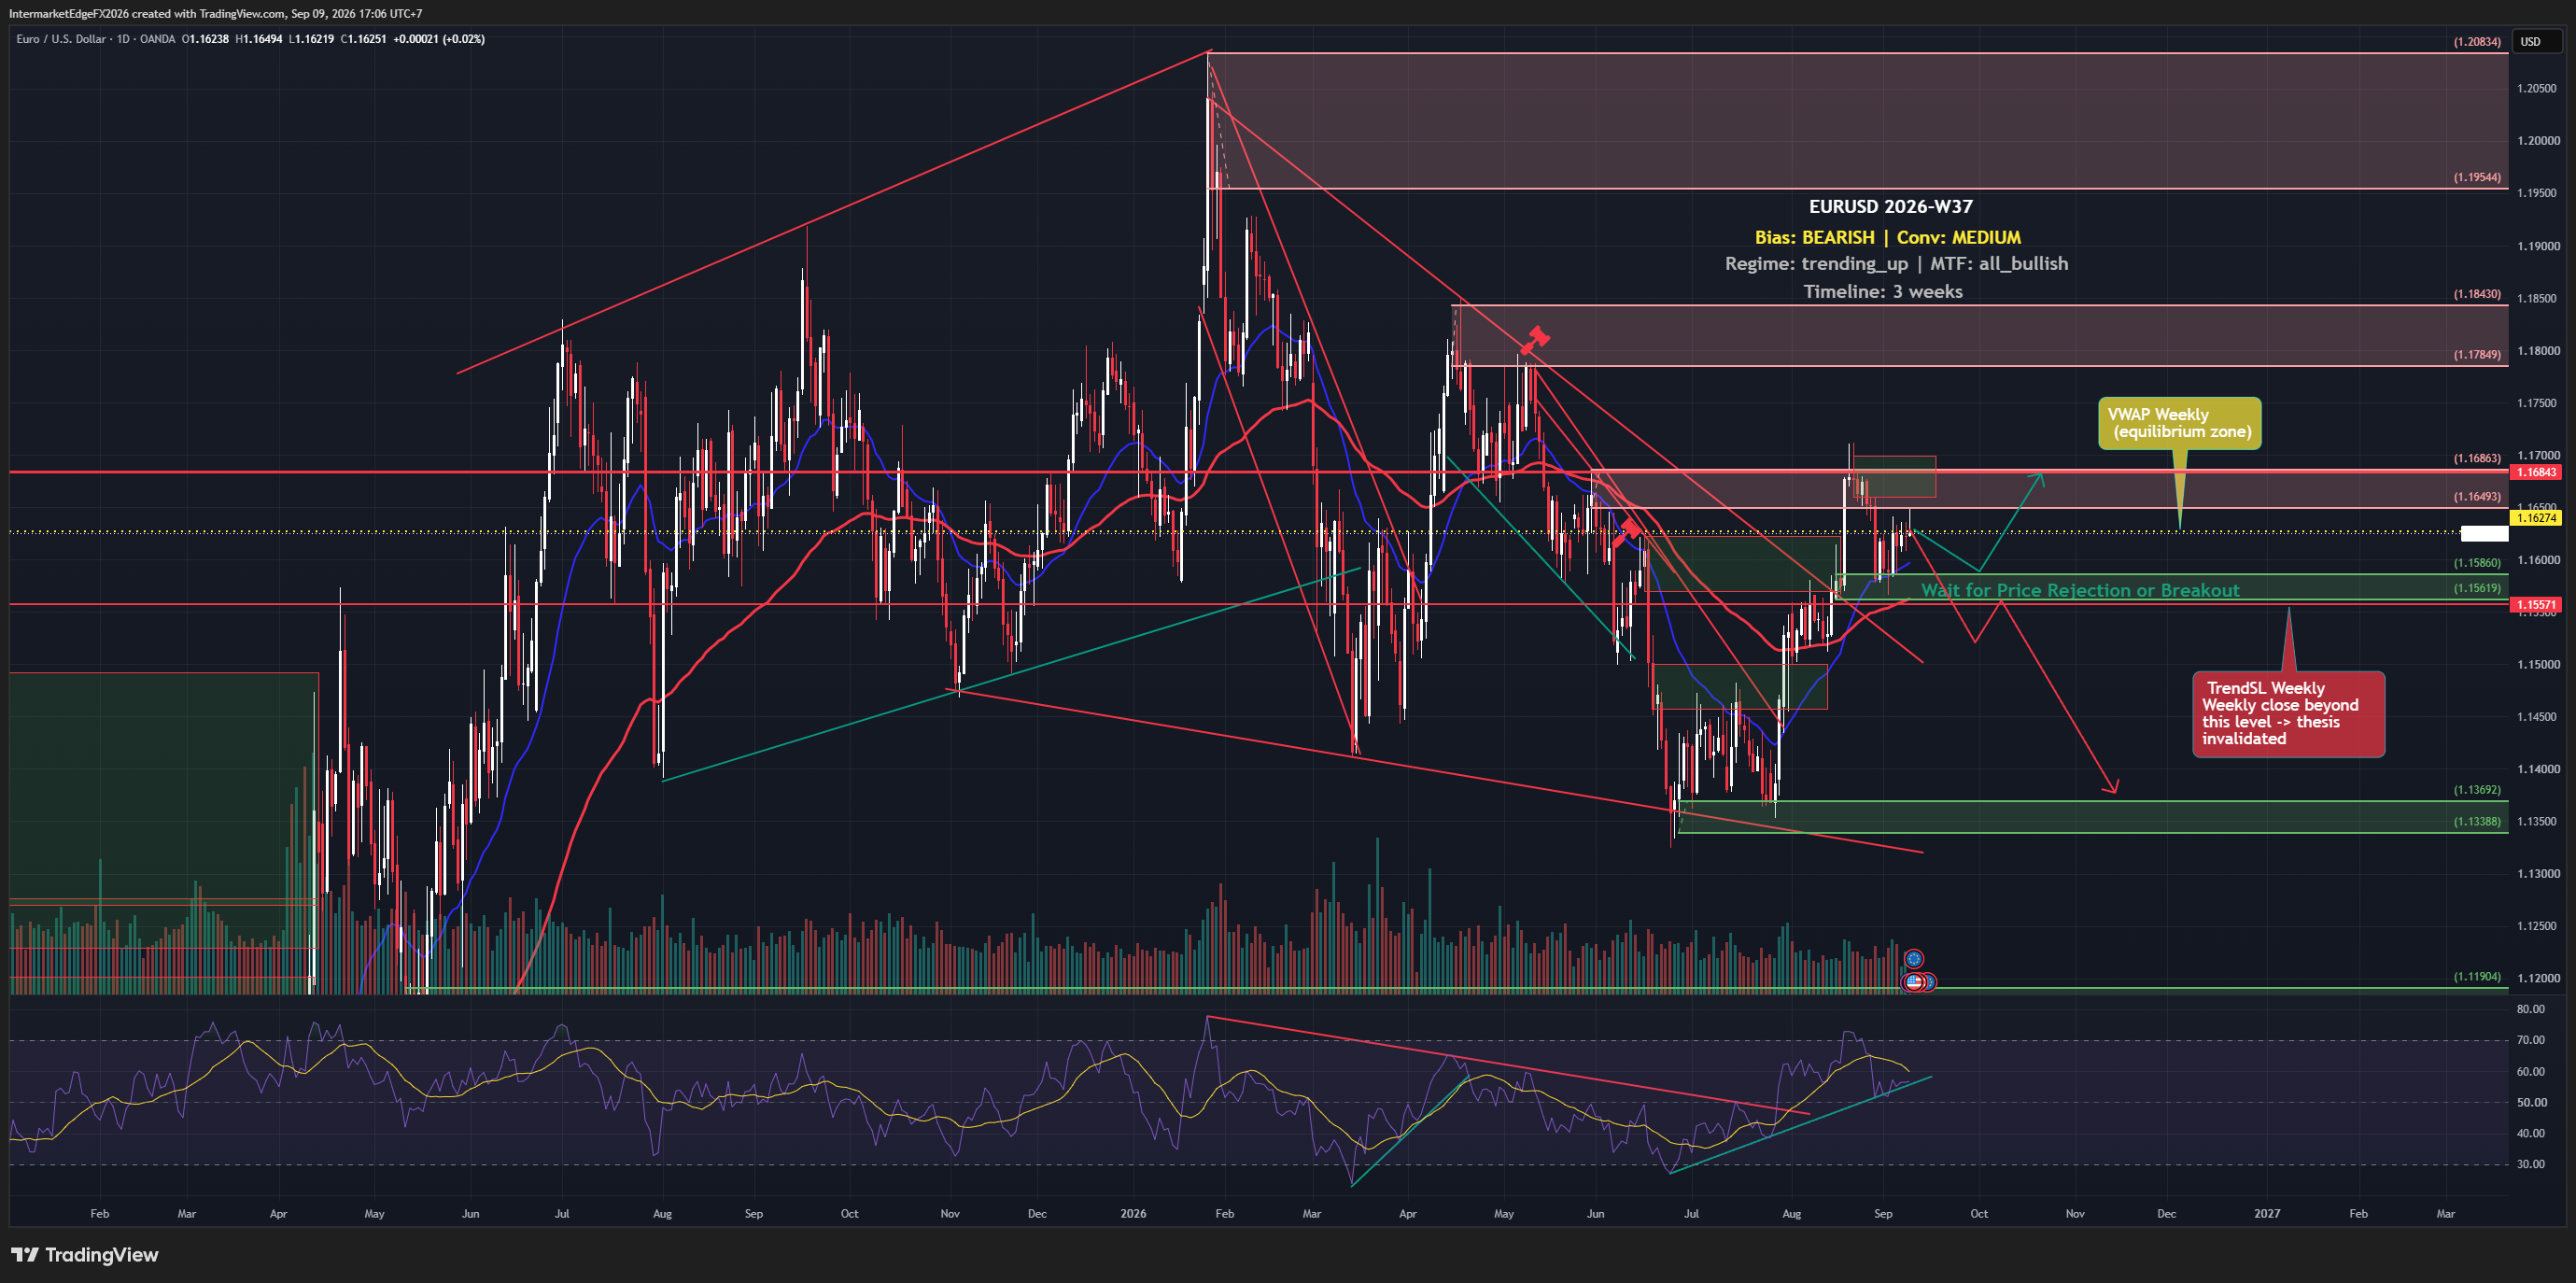
EURUSD is sitting at 1.16393 as of Wednesday, 09 September 2026, above its weekly VWAP at 1.16274 and well above the weekly trend support at 1.15571. The structural bias is bearish, driven by the Fed-ECB rate differential. But every technical and positioning signal points the other direction. When the chart, the COT data, and the price all contradict the macro label, the trade is rarely as clean as the thesis sounds. The bearish bias on EURUSD rests on one primary structural argument: the ECB versus Fed rate differential favors the dollar. When the Fed holds rates higher for longer while the ECB faces pressure to ease amid slowing European growth, the interest-rate gap widens, and wider differentials mechanically increase the cost of holding euro versus dollar, which tends to attract selling pressure on EURUSD. That logic is sound in principle. The problem is that virtually no other input this week agrees with it. The technical picture across daily, weekly, and monthly timeframes is uniformly bullish, the highest level of technical alignment available in this framework, meaning trend-following signals are pointing up, not down. COT positioning (which reflects the directional bets of large non-commercial traders in futures markets; note that this brief does not specify the report week, net-position figure, or release date, so treat it as directional evidence rather than a standalone data point) registers a bullish lean. Price itself, on a multi-timeframe basis, confirms the upward momentum. The result is an unusual configuration where the macro thesis and the market's actual behavior are pointing in opposite directions. Liquidity and sentiment indicators contributed no signal this week, which means the bearish case stands on the rate differential argument alone, without the support of positioning or price behavior to corroborate it. -- Intermarket Edge

DXY Week W37-2026: Strong Payrolls, but the Dollar Cannot Hold Its Gains

DXY Week W37-2026: Strong Payrolls, but the Dollar Cannot Hold Its Gains

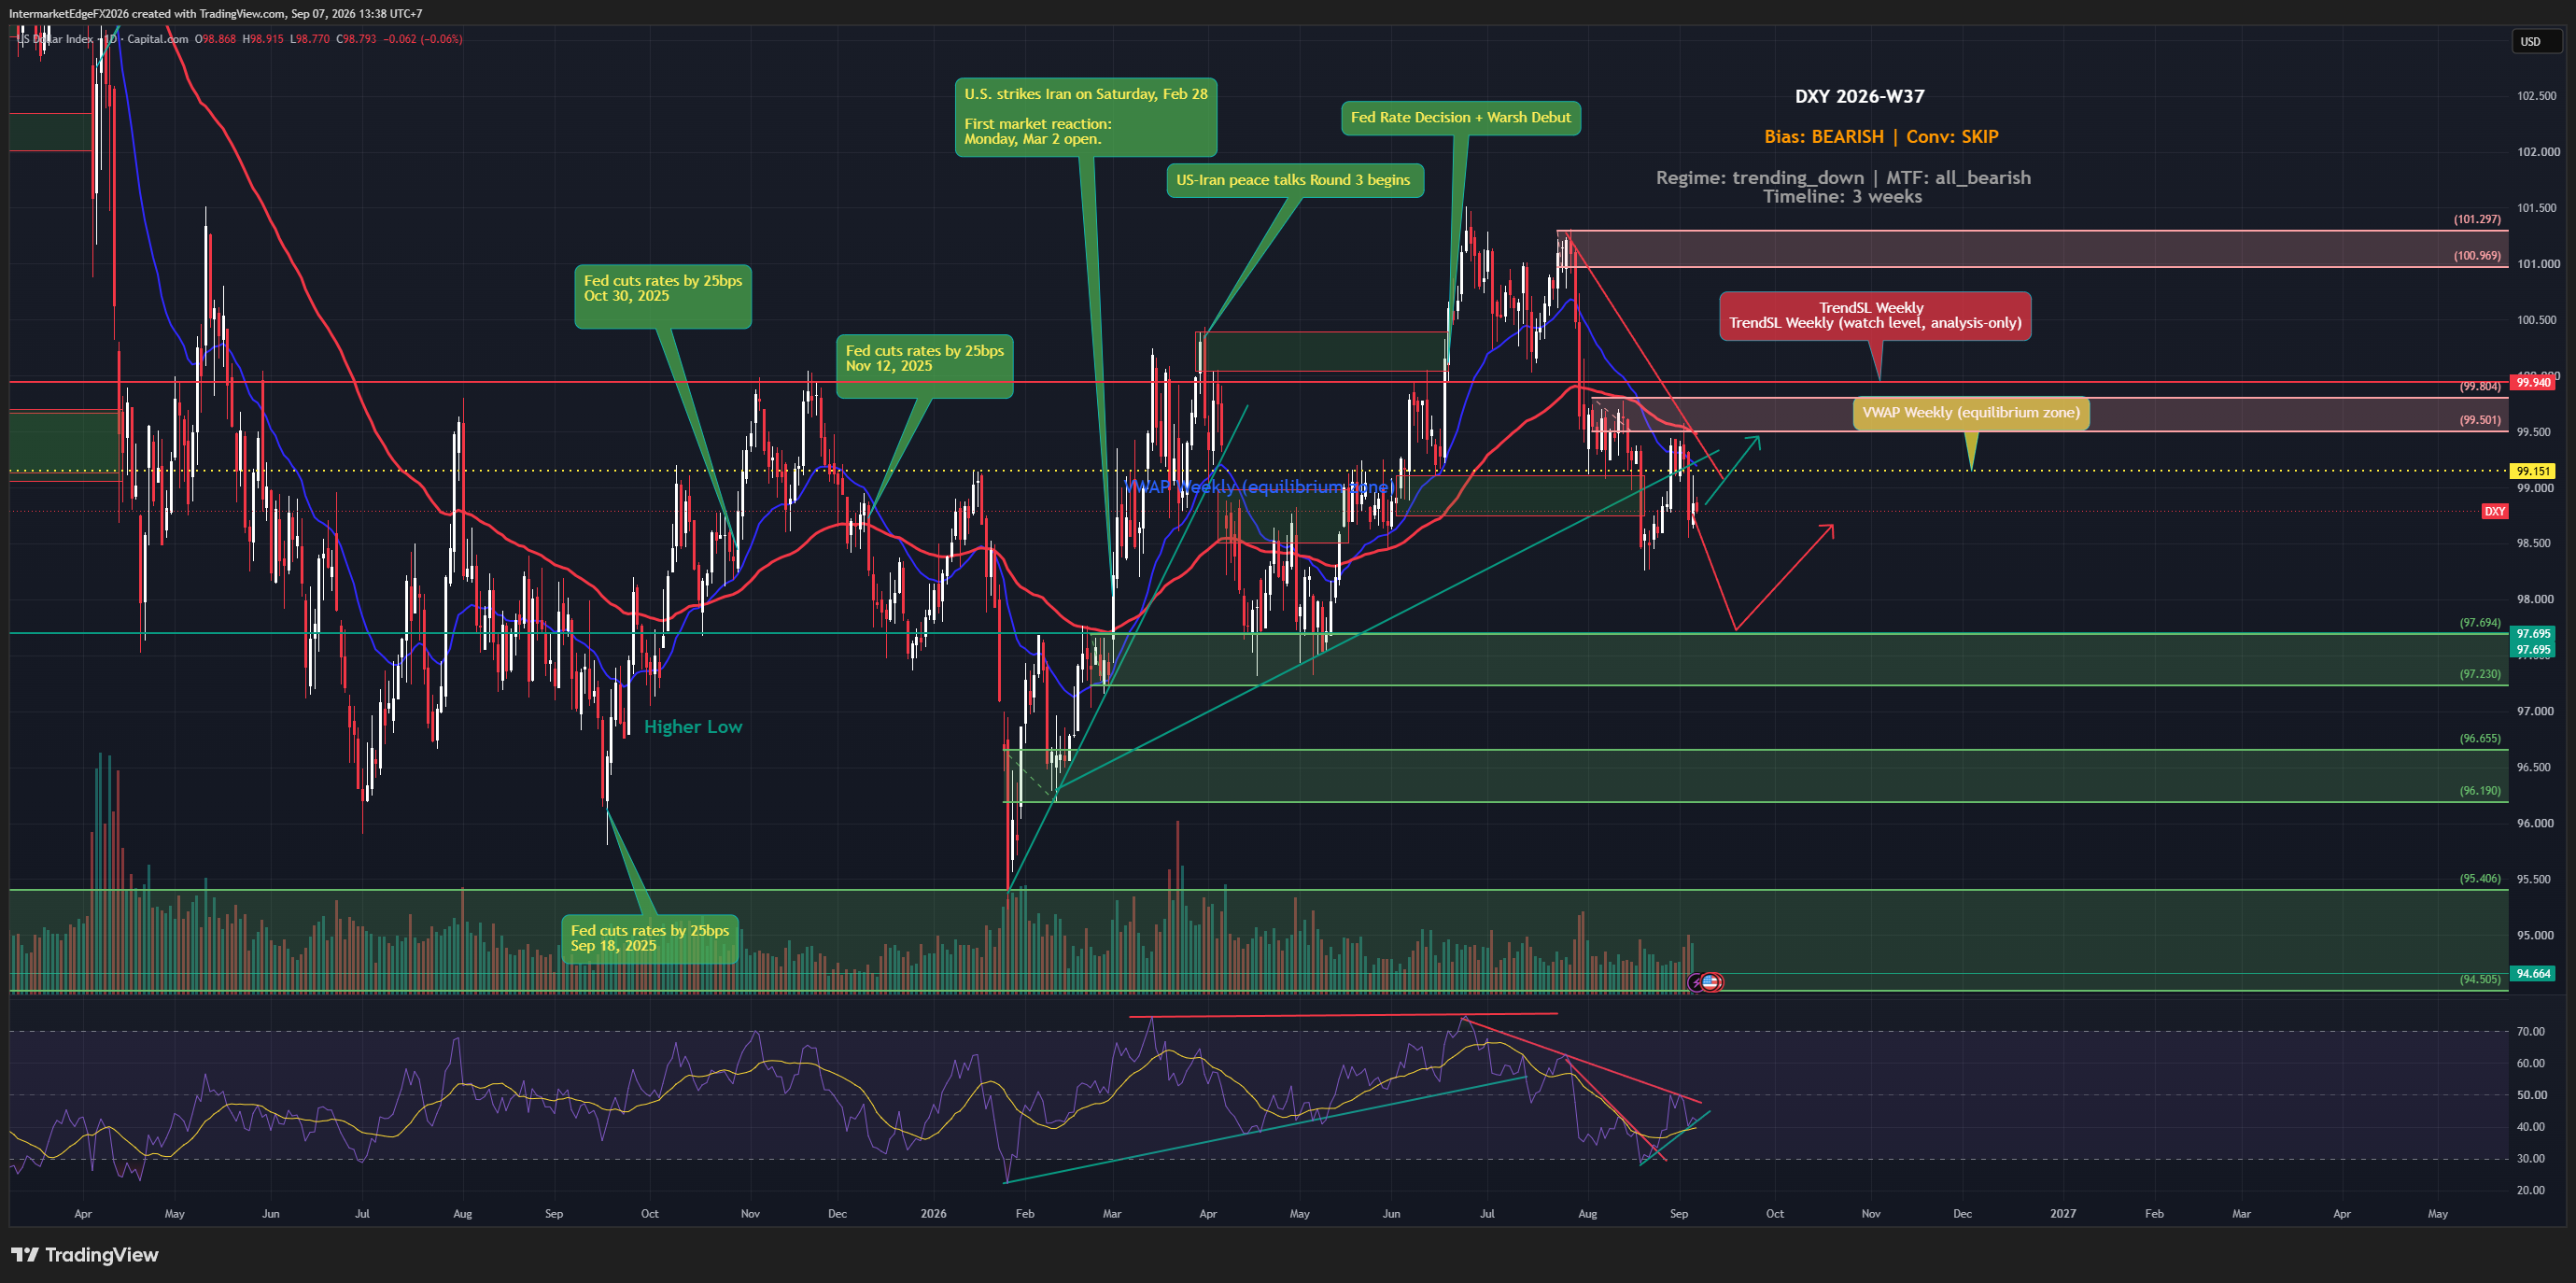
DXY Week W37-2026: strong payrolls, weak follow-through. August payrolls rose 162,000 against the Reuters consensus of 56,000, but the dollar pared its initial gains. Expectations of ECB and BOJ tightening can limit the relative US rate advantage; these remain expectations, not policy decisions. The locked quote is 99.165 at 03:58 UTC on Monday, September 7, 2026, from yfinance:DX-Y.NYB:1m. Price is ABOVE VWAP weekly at 99.151, testing from above by 0.014 points. That is an active short-term momentum conflict with the bearish view. Price remains BELOW TrendSL weekly at 99.94. The bias is bearish, the regime is a downtrend, and monitored timeframes are bearish. The horizon is three weeks. The action state is SKIP: stand aside. Neither the directional classification nor a later VWAP crossing is permission to enter a trade. A weekly close above TrendSL weekly at 99.94 would invalidate the bearish structure. This condition is pending; an intraday move would not be sufficient. August PPI is scheduled for September 10 and August CPI for September 11, both at 08:30 US Eastern / 19:30 Vietnam time, per ForexFactory calendar data. Outcomes are not yet known. For information and education only. Not financial advice.

DXY Weekly Outlook W36: Hawkish Fed, Bearish Structure

DXY Weekly Outlook W36: Hawkish Fed, Bearish Structure

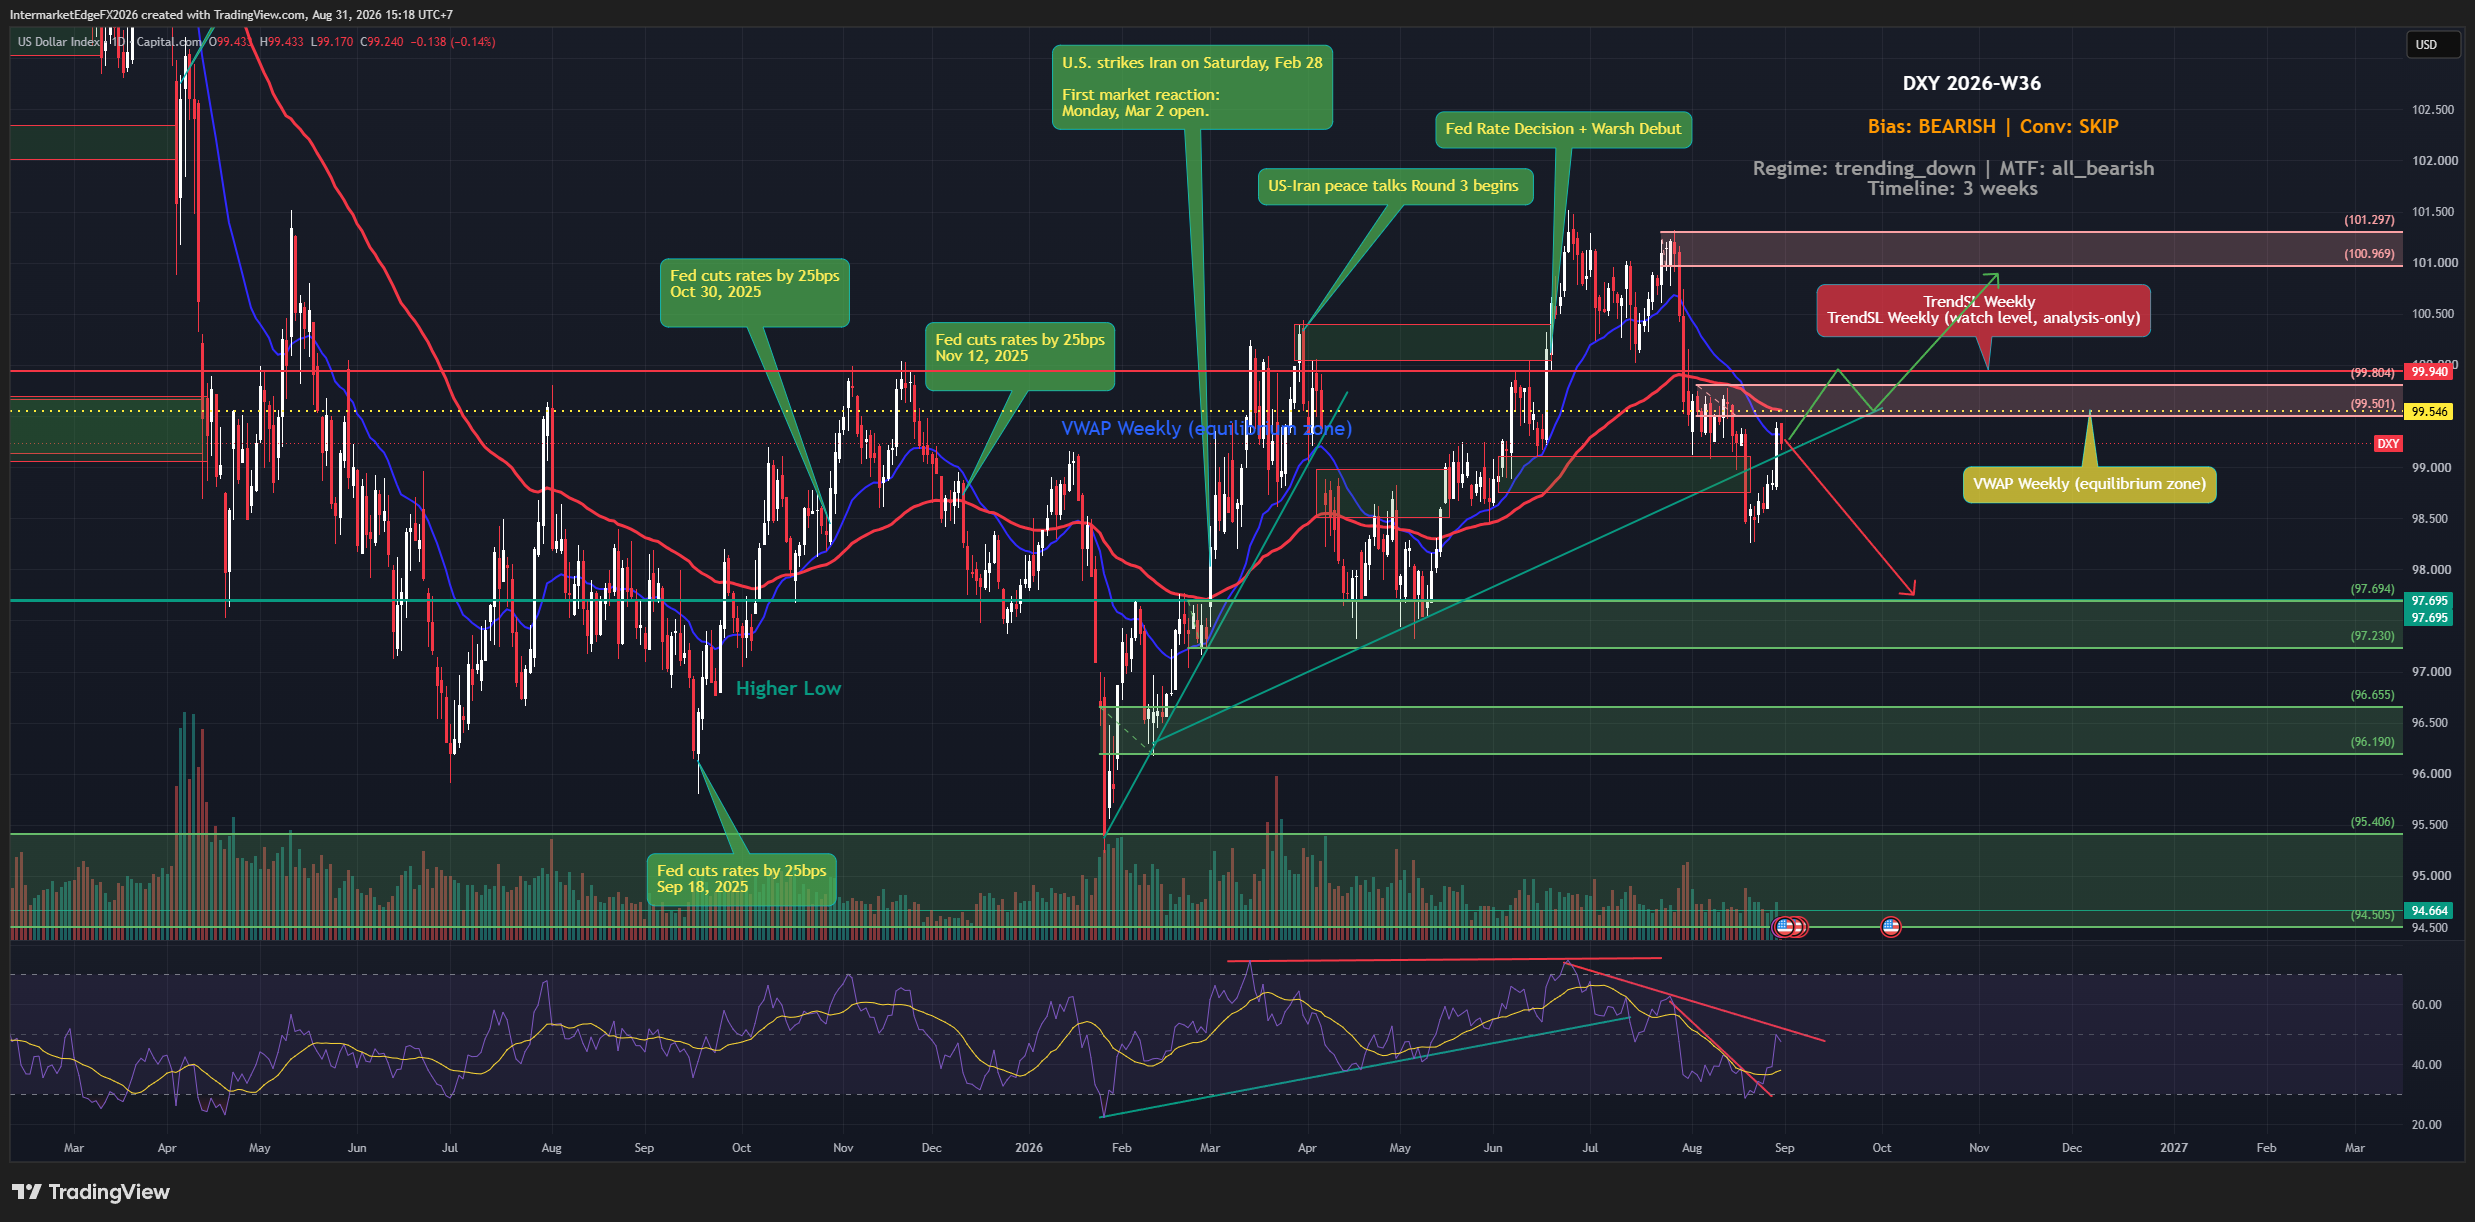
Fed Chair Kevin Warsh just opened the door to further rate hikes if inflation stays sticky, pushing the September hike probability from roughly 36% to around 58%, and the dollar responded, rising about 0.6% to the 99.6-99.7 range. That repricing sounds unambiguously bullish for the DXY. But leveraged funds are already sitting on extreme short positions in the dollar, which means the crowd most likely to fuel a sustained rally may already be largely offside. The payrolls report on September 4 is now the deciding test. The multi-timeframe structure on DXY remains bearish, with alignment across timeframes pointing in the same direction, the regime is trending down, and the framework's FX implication is to follow that trend rather than fade it. That said, the conviction behind this week's bearish read is deliberately low, and staying out of a full position is the rational response to the current evidence, not a failure of analysis. The reason conviction is suppressed comes down to a specific, unresolved conflict. Price action over the past week has been technically constructive, the dollar bounced, reclaimed short-term levels, and printed near a two-week high. Meanwhile, COT positioning data shows leveraged funds holding extreme short positions in the dollar. This is a meaningful divergence: if speculators are already heavily short, there is a contrarian question worth taking seriously, who is left to sell? A market where the bearish crowd is already crowded (crowding risk, meaning the position is so consensus that a reversal triggers forced covering rather than fresh selling) can squeeze sharply on any positive catalyst, and Warsh's hawkish signal plus the geopolitical oil spike are exactly the kind of catalysts that can trigger such covering. -- Intermarket Edge (Note: COT (Commitment of Traders) data is released weekly by the CFTC with a reporting-period lag -- it is not a real-time position feed. See cftc.gov for the exact release schedule.)

Stay in the loop

Get notified about new research, macro insights, and market analysis.

InterMarketEdge

© 2026 InterMarketEdge. Financial intelligence for inter-market traders.